

This article first appeared in The Edge Malaysia Weekly on October 26, 2026 - November 1, 2026
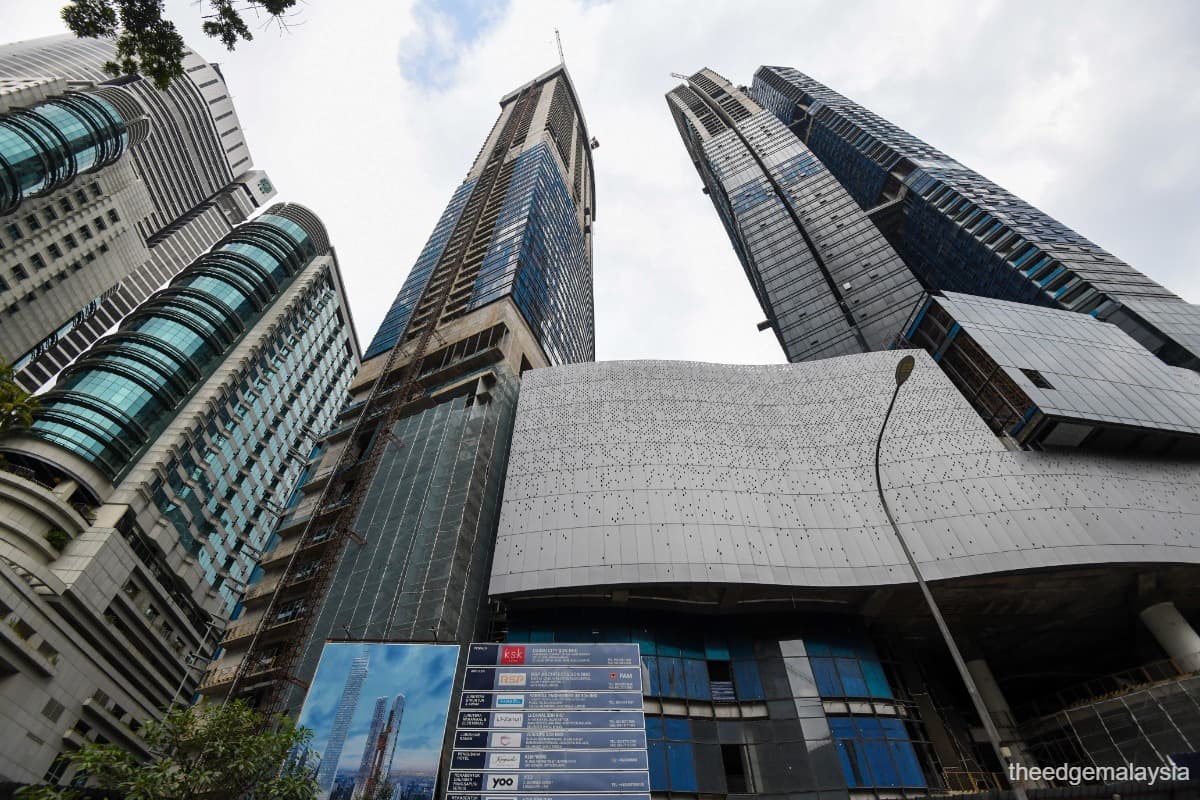
WHEN it was launched in 2015, 8 Conlay was pitched as one of Kuala Lumpur’s most glamorous addresses with three towers on a freehold site in the Golden Triangle, including a luxury Kempinski-run hotel, designer-branded residences and a development value of RM5.4 billion. Nearly a decade after the first units were sold, 8 Conlay is still a half-built shell. Now, a Bursa Malaysia-listed developer, Magna Prima Bhd (KL:MAGNA), via its wholly-owned subsidiary Permata Juang (M) Sdn Bhd, is offering to finish it, and the buyers who paid deposits and instalments years ago are being asked to agree to new terms.
The proposal was presented at a recent meeting between the receivers and managers (R&M) Adamprimus & Co and the purchasers, together with an explanatory statement for a court-supervised scheme of arrangement. Both documents show a way out of the current stalemate for the purchasers but only by giving up claims they have been accumulating for years.
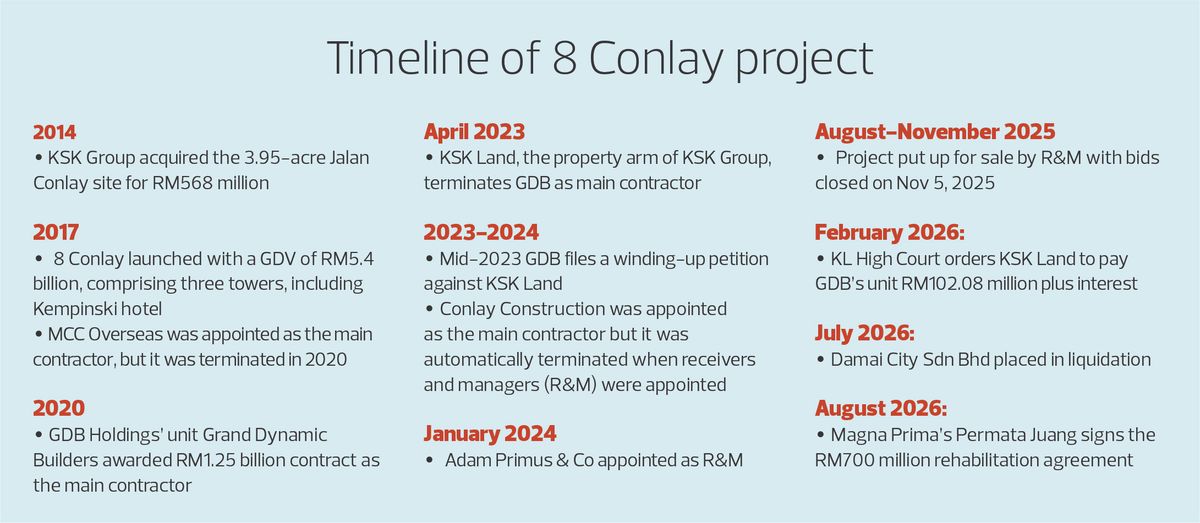
To recap, KSK Land Sdn Bhd, the property arm of KSK Group (formerly known as Kurnia Asia Bhd), had bought the roughly four-acre Jalan Conlay site in 2013 for RM568 million. Its subsidiary, Damai City Sdn Bhd (DCSB, now in receivership and liquidation), planned two residential towers branded YOO8 and serviced by Kempinski, plus a 68-storey hotel tower. Sales of Tower A, launched in late 2015, were reported to be strong with completion targeted for the end of 2020.
That target came and went but the purchasers have yet to receive the keys to their homes.
What went wrong?
According to the explanatory statement, work stopped after funding pressure, rising costs and disputes with contractors. Three main contractors came and went — MCC Overseas (M) Sdn Bhd, appointed in 2017 and terminated in 2020; then GDB Holdings Bhd’s (KL:GDB) Grand Dynamic Builders Sdn Bhd, appointed in late 2020 and terminated in 2023; and the third, Conlay Construction Sdn Bhd, appointed in mid-2023, but whose appointment ended automatically when the R&M came into the picture. Two of the earlier contractors have sued DCSB.
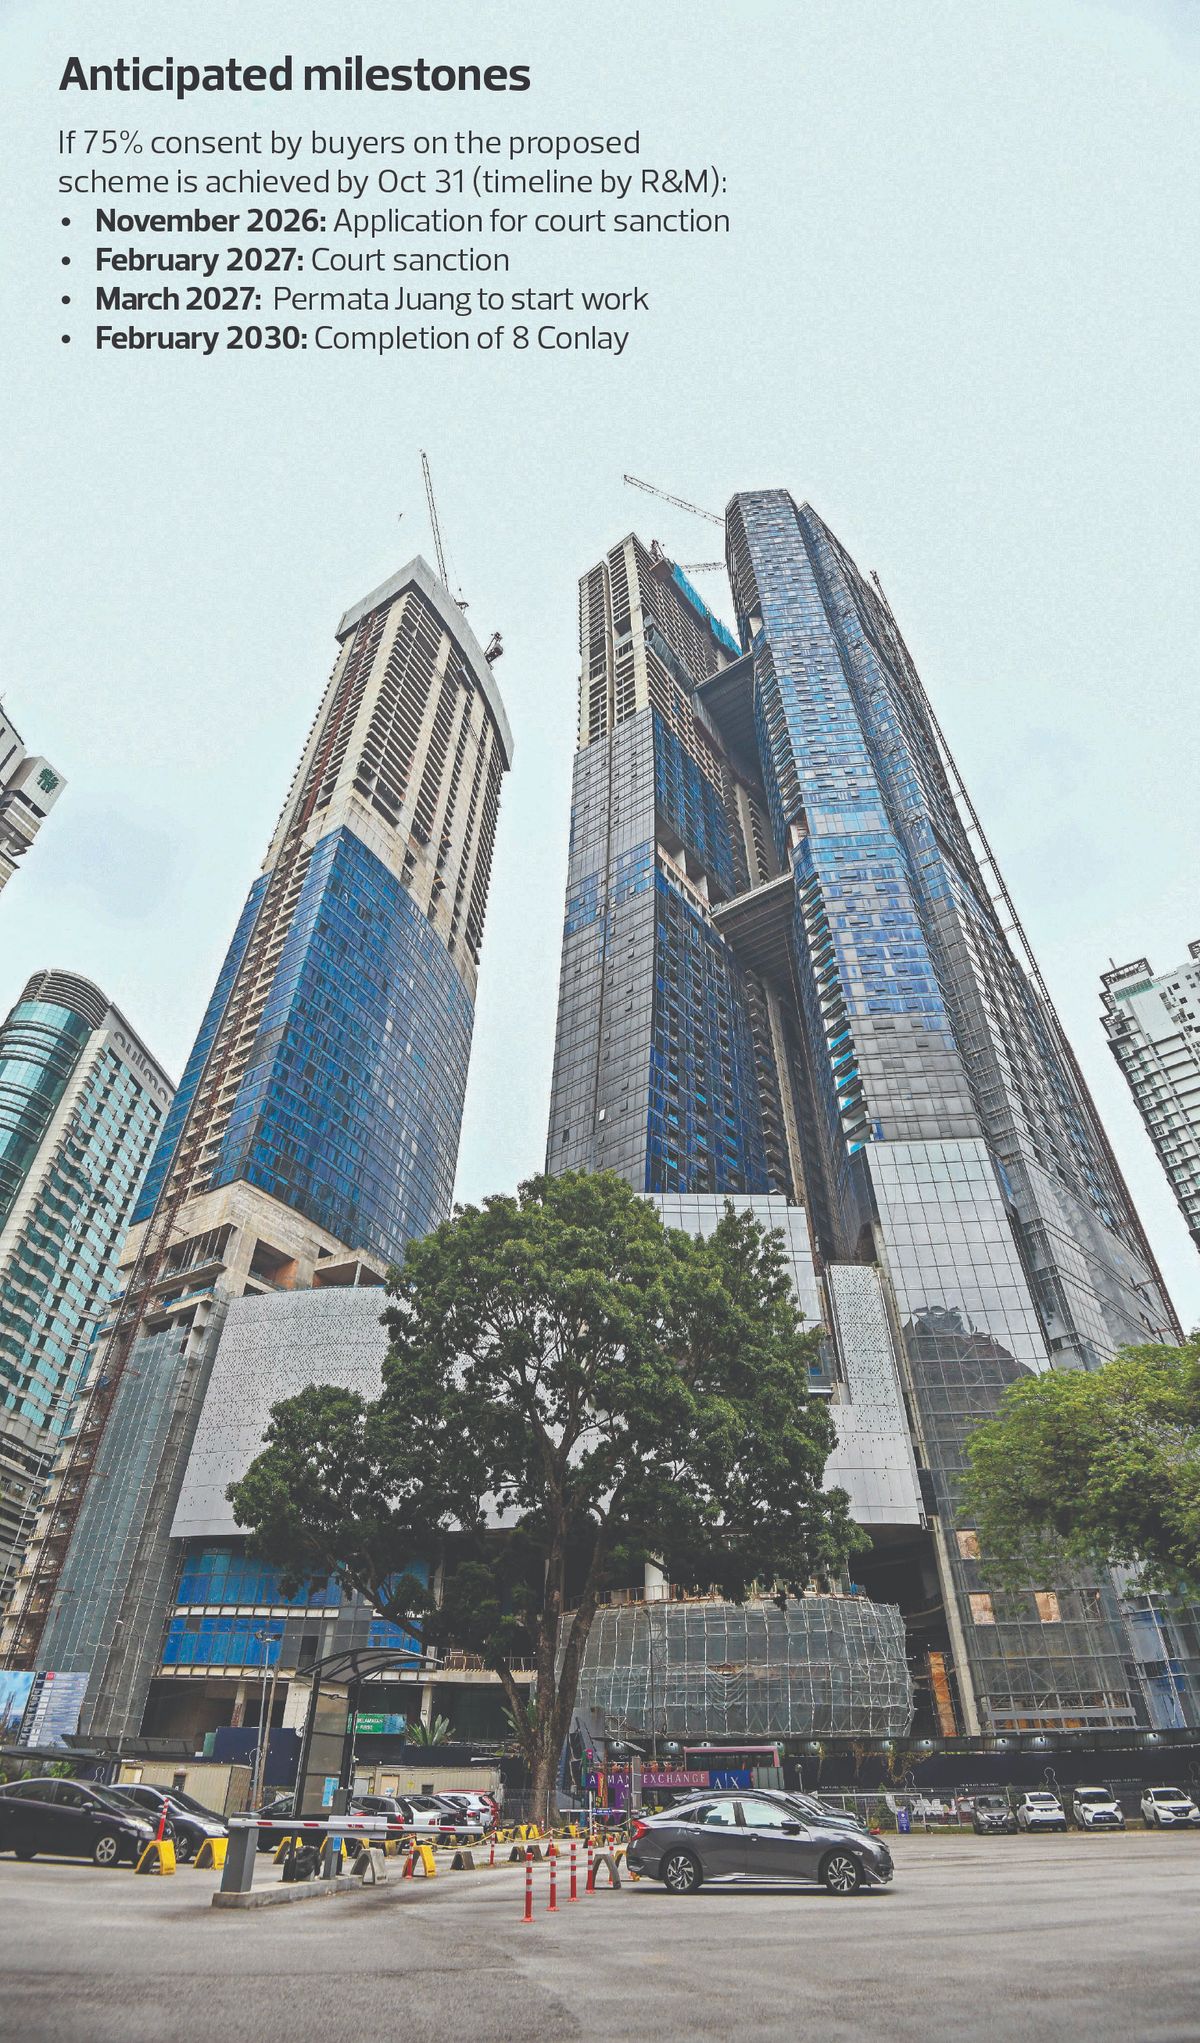
The progress in 8 Conlay, by cost incurred, stands at about 70% for the retail podium, 65% for Tower A, 50% for Tower B, 46% for the hotel and 22% for the hotel suites. Some 404 units in Tower A and 160 in Tower B have been sold.
In January 2024, Malayan Banking Bhd (KL:MAYBANK), the secured lender, appointed Datuk Adam Primus Varghese Abdullah and Macpherson Anak Simon of Adamprimus & Co as the R&M. KSK Group is said to have tried nine times to use corporate rescue mechanisms, including schemes and judicial management but these were set aside or struck out. Courts also required DCSB’s directors to seek leave before making further applications.
The R&M then ran their own process. An early bid led by Lecca Holdings (M) Sdn Bhd on behalf of a consortium proposed a RM700 million deal for the development rights and shares in the owner of Tower C — Infinite Holding Sdn Bhd — also a wholly-owned subsidiary of DCSB. The R&M said that collapsed for lack of funding certainty, and the High Court upheld the termination in February 2026. An open sale process launched in August 2025 drew offers that were for rehabilitation rather than a plain land sale, and the R&M chose Permata Juang as the rehabilitation developer.
The RM700 million restructure
The rehabilitation agreement was signed on Aug 13, 2026. DCSB’s land and business would move into a new continuation vehicle, Delta 8 Sdn Bhd, which grants Permata Juang exclusive development rights. In exchange, Permata Juang assumes liabilities of up to a RM700 million cap, which independent valuations put as the project’s residual value in its abandoned state. Those liabilities are to be settled by issuing redeemable secured loan securities with Maybank’s and the syndicated lenders’ existing charges released and replaced. Magna Prima would give a corporate guarantee, subject to its own shareholders’ approval.
The deal comes with a long list of conditions. These include court sanction of the scheme, Magna Prima shareholder approval, approval from the Controller of Housing, removal of private caveats and the unwinding of the arrangements that moved Tower C and the Kempinski management contract to Infinite Holding. If any of these fails, Permata Juang need not proceed.
In its Aug 13 announcement , Magna Prima said the development of 8 Conlay will be funded by internally generated funds and borrowings.
For the first half of the financial year ending Dec 31, 2026 (1HFY2026), Magna Prima recorded a profit attributable to shareholders of RM12.57 million, compared with a RM1.93 million loss a year earlier, while revenue rose to RM146.77 million from RM16.20 million. Its market cap, according to AskEdge, is RM223.5 million.
In its Bursa filing on Oct 20, Magna Prima had proposed to change its name to Hallson Group Bhd, subject to shareholders’ approval at an extraordinary general meeting to be convened. The proposed name is similar to that of Hallson Holdings Sdn Bhd, an investment vehicle controlled by the group’s largest shareholders, Datuk Seri Bryan Wong Sze Chien and managing director Eddy Seah Ley Hong. Both Wong and Seah hold an indirect 54.96% stake in Magna Prima.
What is being offered to existing buyers
Once the deal is completed, existing sale and purchase agreements (SPAs) are novated to Permata Juang, which becomes the developer for the remaining obligations, such as completing the units, delivering possession, fixing defects and obtaining strata titles. Each purchaser then has 60 days to choose one of three options — to keep the unit, swap the unit with selected Armani-branded developments or sell their unit. Anyone who does not choose is treated as having picked the first (see three options under the scheme for purchasers of 8 Conlay).
Ipoh-based Armani Group is the development partner of Magna Prima on the Armani Hallson KLCC project, with Magna Prima as landowner and Armani Group as developer, and both are controlled by the same key shareholders.
But the trade-off is stark. Claims for liquidated ascertained damages (LAD) and any other loss arising from delays or defaults before the novation date are compromised and cease to be payable. LAD would only start running again if the new completion deadline is missed. The scheme, once approved and sanctioned, binds every existing purchaser, including those who vote against or do not vote.
Branding changes too. The Kempinski name and operator arrangements fall away on novation, and the developer may appoint a replacement operator. Existing guaranteed rental or leaseback arrangements are excluded and must be terminated.
Ultimately, existing purchasers are the only class that vote. Approval needs at least 75% in value of those present and voting, in person or by proxy, at a court-convened meeting. The R&M has set a target of Oct 31, 2026, to obtain that approval, which leaves little time. The alternative to a deal is worse, and with the vote just days away, the pressure is now on the purchasers to decide.
While it is not clear whether this could turn out to be a stumbling block to the rehabilitation of 8 Conlay, GDB’s subsidiary Grand Dynamic Builders’ application to intervene in the R&M’s scheme of arrangement as disclosed in a Bursa filing on Sept 25, could be another moving piece to watch.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.