

KUALA LUMPUR (Oct 14): Kenanga Research has flagged that operational, regulatory and reputational risks have escalated at CTOS Digital Bhd (KL:CTOS), and that near-term earnings visibility has weakened amid the risk of customer attrition to rival bureaus.
The house downgraded the counter to 'market perform' from 'outperform' following a cybersecurity incident disclosed on Sept 23, 2026.
Kenanga noted that the outage affects about 35% of group weekly revenue, spanning roughly 55% of financial institutions and corporates segmental revenue, 10% of commercial revenue, and all consumer revenue, while international revenue is unaffected.
"Assuming services resume by the third week of October 2026 with a 30-day recovery, CTOS guides to an FY2026 (financial year ending Dec 31, 2026) revenue hit of about RM16 million and a Patami (profit after tax and minority interests) impact of RM12 milllion," said Kenanga in a note on Thursday.
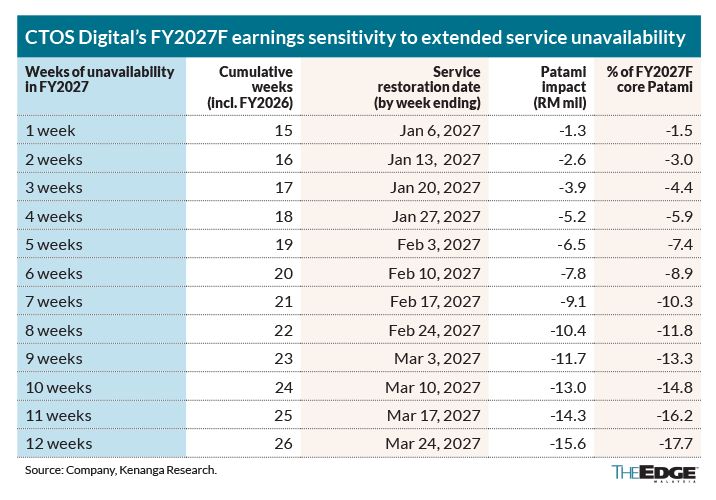
As two of four independent reviews remain pending, Kenanga prudently assumes services will stay offline until end-December 2026, raising the FY2026 Patami impact to RM22 million and pushing a RM3 million recovery drag into the first quarter of 2027.
Consequently, it cut its core Patami forecast by 22.6% for FY2026 and by 3.5% for FY2027, and lowered the discounted cash flow-derived target price to 48 sen from 83 sen.
Nonetheless, Kenanga views the incident as a temporary setback rather than a structural impairment, with longer-term growth drivers intact, including the Consumer Credit Act 2025, digital bank demand, and potential monetisation of associate stakes.
However, the stock is expected to trade sideways until there is greater clarity on service resumption timing and customer retention, with risks including a longer outage, regulatory penalties, weaker lending demand, and adverse regulatory changes.
More positively, RHB Research maintains its 'buy' call for CTOS, as it believes the company will strongly recover once its systems are back online.
The research house said the credit reporting agency still had the leadership and core solutions to recover through strong revenue for its current financial year.
RHB Research noted that a credit scoring agency within the financial ecosystem remains vital, and the company will recover once an independent assessment is completed under the requirements set by Bank Negara Malaysia and the systems are able to resume.
The research house believes that despite the incident, the company’s earnings for 2027 will be unaffected given this expected swift recovery, forecasting a revenue of RM373 million for 2027 and RM400 million for 2028, compared to its forecasted RM332 million revenue for 2026.
RHB Research has lowered its target price to RM1.06 from RM1.10 previously.
This suspension of its services has deterred potential new customers from the service, estimating damages up to RM12 million, with each week the service remaining closed adding about another RM1.3 million in cost.
However, RHB Research called this an isolated event and said the major sell-off in shares, which led to its share price plummeting to an all-time low of 47 sen on Wednesday, according to Bloomberg, was overblown.