

KUALA LUMPUR (Sept 17): Analysts say now is a good opportunity to buy and accumulate YTL Power International Bhd's (KL:YTLPOWR) shares, given the recent pullback and the company's reservation of four new gas turbines amid a global backlog.
CGS International Research said in a note that the company’s recent reservation of four new Siemens gas turbines back on Tuesday increased its current inventory to seven turbines, bringing strong profit potential if all planned energy plants go live by early 2031.
Though YTL Power only signed a reservation agreement, should the purchase go through, all seven turbines put together would have a capacity of around 5.25GW of new combined-cycle gas turbine (CCGT) power plant capacity.
CGS added that this reservation is important as these turbines are difficult to secure and typically have long waiting periods.
A single CCGT power plant, capable of around 1.4GW, can generate up to RM250 million in annual net profit. With all seven turbines in use, this could reach up to RM850 million, according to the house.
This energy capacity is essential to YTL Power’s ambitions to help meet rising demand from data centres, energy guzzlers that are in urgent need of more power, in Malaysia and the wider Southeast Asia region.
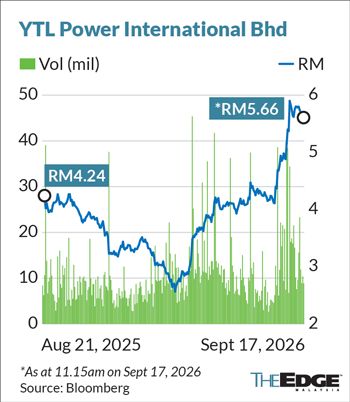
These potential profits, mixed with the company’s stock price staying within the RM5.51 to RM5.9 range since Aug 26 following a sharp rise from its data centre projects, have led CGS International to call this period an opportune time to accumulate stocks in YTL Power, maintaining its 'add' status and target price of RM6.50.
At the current share price of RM5.68, the target price implies an upside of over 14%. The counter gained 17 sen or 3.1% in early trade, valuing the group at RM49.6 billion.
Separately, RHB Research has also maintained its 'buy' call and target price of RM7 for YTL Power.
"In addition to its three gas turbine units on hand, this will enable YTL Power to build up to 5.25GW of new gas plants in the region. Assuming the group secures power purchase agreements for the total capacity, we estimate a 17% upside to our target price."