

This article first appeared in The Edge Malaysia Weekly on September 7, 2026 - September 13, 2026
ANALYSTS rate the corporate earnings performance for 2Q as “satisfactory” given the backdrop of a prolonged Middle East conflict. The relative resilience of corporate earnings was attributed to Malaysia’s position as a net gas exporter, robust commodity prices and the ongoing up cycle in the technology sector.
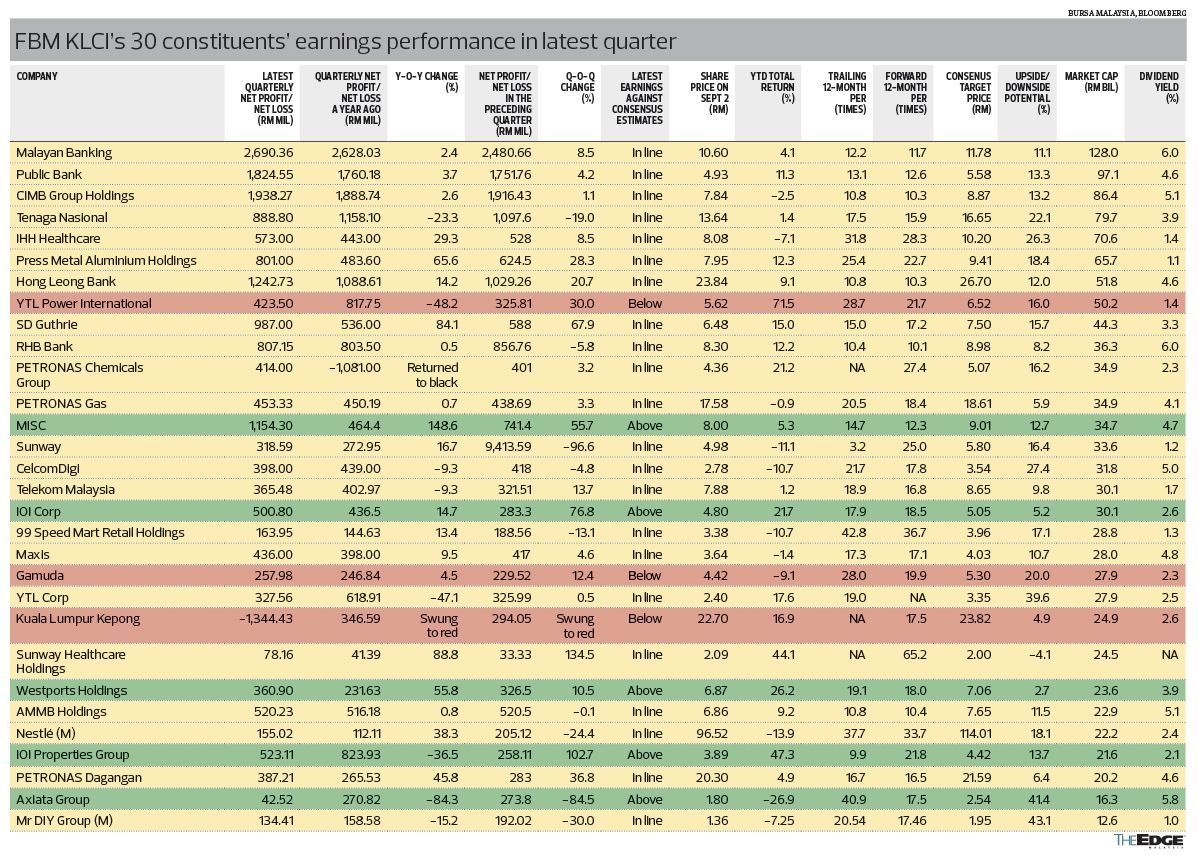
For the quarter in review, the aggregate earnings of FBM KLCI constituents came in at RM17.8 billion, representing a 33.2% quarter-on-quarter (q-o-q) decline and a 5.1% year-on-year (y-o-y) growth, according to MBSB Research.
After adjustment for extraordinary items — particularly a RM1.6 billion impairment by Kuala Lumpur Kepong Bhd (KL:KLK) to reduce the carrying value of its investment in its loss-making, UK-listed speciality chemicals associate, Synthomer plc — the aggregate normalised quarterly earnings of FBM KLCI constituents amounted to RM18.7 billion, 3% and 11.8% higher q-o-q and y-o-y, respectively.
The positive y-o-y normalised growth performance was mainly due to higher earnings for PETRONAS Chemicals Group Bhd (KL:PCHEM), Press Metal Aluminium Holdings Bhd (KL:PMETAL) and SD Guthrie Bhd (KL:SDG), though moderated by lower earnings for YTL Power International Bhd (KL:YTLPOWR) and its parent company YTL Corp Bhd (KL:YTL).
Sector-wise, total earnings of construction, energy, financial services, healthcare and transport and logistics recorded an improvement both q-o-q and y-o-y. However, consumer, plantation, telecommunications and media and utilities registered both negative sequential and y-o-y earnings growth in 2Q2026.
Among the FBM KLCI constituents, companies that came in below consensus expectations were Gamuda Bhd (KL:GAMUDA), YTL Power and KLK while IOI Corp Bhd (KL:IOICORP), IOI Properties Group Bhd (KL:IOIPG), Westports Holdings Bhd (KL:WPRTS), MISC Bhd (KL:MISC) and Axiata Group Bhd (KL:AXIATA) posted results that were above expectations.
Among the top 100 companies by market capitalisation, 68 reported y-o-y growth in net profit while 63 saw q-o-q expansion.
The FBM KLCI will be expanded to 50 constituents in its upcoming December review. The 20 newly added constituents will be included at 50% of their final index weight in the review while the remaining 50% of the weight will be implemented in the June 2027 review.
RHB Research highlighted that the June quarter reporting season was a sharp turnaround from the preceding quarter and slightly ahead of expectations. It said for the first quarter since December 2020, no sector had reported overall earnings that were deemed to have missed expectations while six sectors — automotive, O&G, transport, gaming, healthcare and rubber products —– beat expectations.
The research house attributed the relative resilience of corporate earnings to a combination of Malaysia being a net gas exporter, robust commodity prices and the technology sector’s up cycle. This was offset by a downgrading of the banking sector to “neutral” on valuation grounds and nascent funding and asset quality headwinds.
Hong Leong Investment Bank (HLIB) Research pointed to the automotive sector, which surprised on the upside with better-than-projected margins for firms like Sime Darby Bhd (KL:SIME), Bermaz Auto Bhd (KL:BAUTO) and MCE Holdings Bhd (KL:MCEHLDG).
TA Securities said sectors that broadly met expectations included banking, building materials, construction, consumer, gaming, healthcare, insurance, plantation, power and utilities, property, technology and telecommunications.
The research house projected earnings per share (EPS) for FBM KLCI component stocks to grow 8.3% in 2026 and 5.3% in 2027, versus Bloomberg consensus estimates of 6.4% and 6.9%, respectively. Key contributors to next year’s earnings growth are expected to be banks, power and utilities, construction, healthcare, and telecommunications.
“We maintain our end-2026 FBM KLCI target of 1,760 points, based on a 2027 PER (price-earnings ratio) of 14.6 times, as we see limited scope for multiple expansion until greater clarity emerges on geopolitical tensions, the US midterm elections and fluid domestic politics.”
While maintaining its end-2026 target for the FBM KLCI at 1,750 points, RHB Research noted that prevailing geopolitical and global macroeconomic challenges will cap the market’s absolute upside. That said, the market will remain focused on fundamentals as corporate earnings performance will be a key determinant of its fundamental upside.
“While earnings adjustments were positive, they were not enough to move the needle — the market will likely remain range bound with downside support from robust liquidity conditions.
“Our emphasis on trading remains valid and we continue to believe portfolio management should be anchored on a defensive bedrock even as inflationary conditions shift global interest rate conditions towards a more hawkish slant.”
Overall, RHB Research had “overweight” calls on the plantation, energy, property, construction, basic materials, technology, healthcare and transport sectors. “We expect to see continued rotational interest in laggard stocks and laggard sectors as investors maintain a trading mentality.”
Year to date, the FBM KLCI has gained marginally by about 2%, while the FBM ACE Index has risen by more than 6%, driven by strong interest in small caps that are linked to semiconductors, data centres and power infrastructure.
For the heavyweight banking sector, which delivered a mixed bag of results, MBSB Research observed that although valuations may be tighter than before, further positive share rerating is possible based on improved macroeconomic growth prospects, expectations of better earnings recovery and asset growth, confirmation of limited asset quality impact, as well as further likelihood of dividend upside via capital release and payout ratio increases.
Most banks are guiding for a stronger 2H2026 but headwinds include net interest margin compression and non-fee non-interest income weakness. Asset quality issues were confined to smaller banks as larger peers did not see much negative impact.
Meanwhile, AmResearch said the risk-reward profile of the banking sector had skewed to the upside as valuations sat at just 0.9 times price-to-book with about 6% dividend yield but institutional positioning was still light.
“Moreover, profit is set to accelerate, with FY2027 growth of 3.7% stepping up from 1.3% this year; positive 2Q2026 momentum keeps this trajectory on track. Also, Malaysian banks trade at a hefty 20% to 60% discount to Singapore and Thai peers despite sharing the same rerating DNA,” the research house pointed out.
Its top picks for the sector are Hong Leong Financial Group Bhd (KL:HLFG), CIMB Group Holdings Bhd (KL:CIMB), Hong Leong Bank Bhd (KL:HLBANK) and Alliance Bank Malaysia Bhd (KL:ABMB).
Also worth mentioning are the plantation, rubber gloves and transport sectors. Plantation players benefited from stronger fresh fruit bunch production, higher crude palm oil prices and robust downstream earnings. Similarly, stronger sales volume and average selling prices augured well for rubber glove makers while transport players were supported by stronger cargo volumes and petroleum shipping earnings.
CIMB Securities noted, however, that earnings disappointments were concentrated in the O&G, consumer and utilities sectors. Following the 2Q2026 results season, the research house upgraded the FBM KLCI’s core net profit growth to 7.6% for 2026 from 7.2% previously, driven mainly by higher forecasts for SD Guthrie, MISC and Maxis Bhd (KL:MAXIS).
At the same time, CIMB Securities marginally raised the end-2026 FBM KLCI target to 1,752 points from 1,745 points, based on an unchanged target PER of 15.1 times.
“We also upgraded the utilities sector to ‘overweight’ from ‘neutral’, following our upgrading of YTL Power to a ‘buy’ while keeping our other sector ratings unchanged. We refreshed our top picks, adding YTL Power, IHH Healthcare Bhd (KL:IHH), IGB Real Estate Investment Trust (KL:IGBREIT) and Westports while removing MR DIY Group (M) Bhd (KL:MRDIY), KPJ Healthcare Bhd (KL:KPJ) and Axis Real Estate Investment Trust (KL:AXREIT).
“Our top picks are largely companies that are relatively defensive against geopolitical risks, offer attractive valuations or have identifiable stock-specific catalysts. We remain constructive on the Malaysian equity market, supported by improving corporate earnings, attractive dividend yields and domestic catalysts, although geopolitical risks and higher global bond yields could temper near-term upside.”
Read also: Save by subscribing to us for
your print and/or
digital copy. P/S: The Edge is also available on
Apple's App Store and
Android's Google Play.
Cover Story 2: Tech stocks face high bar as AI boom lifts expectations