

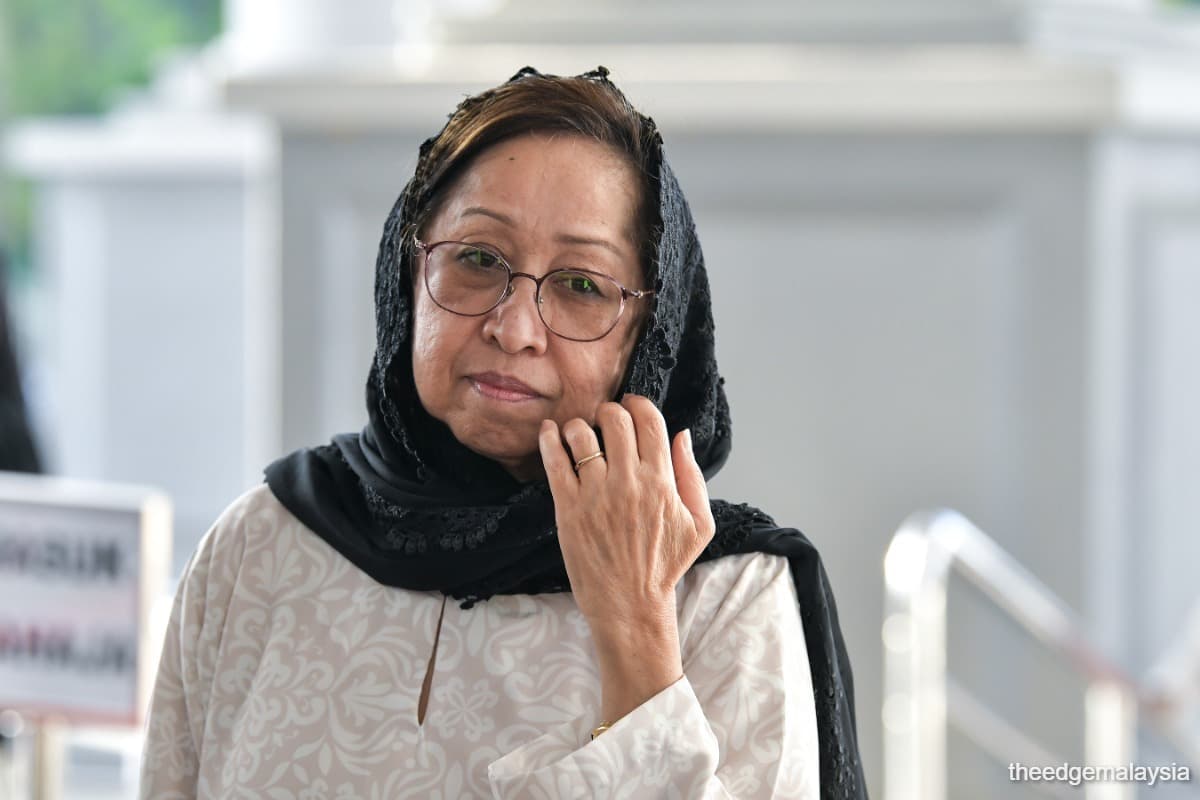
SHAH ALAM (Aug 6): Toh Puan Na’imah Abdul Khalid on Thursday successfully set aside an additional RM313.8 million tax claim, prevailing in her judicial review against the Inland Revenue Board.
High Court judge Evawani Farisyta Mohammad ruled that there was illegality and irrationality by the director general of the Inland Revenue Board to impose the additional tax for the year assessment of 2018 when the three foreign properties were acquired in the 1990s.
The law also only allows taxes on income gained in Malaysia while the assets were acquired by her late husband Tun Daim Zainuddin from the US, making it illegal for the government to tax the assets, Evawani Farisyta said.
The case rests on the Inland Revenue Board’s allegations that Na’imah had failed to declare income used to acquire and generated from three properties — Nantasket Beach Resort, Chauncy Place, and Hotel Buckminster — worth US$178 million or over RM700 million.
Daim and Na’imah, who had opted for joint taxation, had already settled additional tax of RM31.498 million for the 2017, 2018 and 2019 assessment years on Nov 2023.
The extra charge tacked on can be seen as double taxation following the disposal of the three properties, the judge noted.
Further, requiring Na’imah to produce documents on the acquisition of assets from the US which are 20-or-30 years is also illogical, illegal, and not rational, Evawani Farisyta said, as any tax payer is only required to keep their tax records or documents for seven years under Income Tax Act.
Evawani Farisyta allowed Na’imah judicial review and made no order as to costs.
Trust in the judiciary
Na’imah said she felt vindicated with today’s decision as she is a responsible taxpayer and she a law abiding citizen.
“The ruling today shows that the judiciary is a branch that taxpayer can rely on where there is an abuse of public authority,” she said in a statement issued through her lawyer Datuk S Saravana Kumar.
Na’imah obtained leave, or permission, on April 22 last year to proceed with the judicial review from High Court judge Shahnaz Sulaiman, who is now a Court of Appeal judge. The court then ruled that it was satisfied that there were legal issues to be considered.
The director-general was named as respondent, with Na’imah asking the court to cancel the order issued by the Internal Revenue Board on Aug 13, 2024 which she argued was illegal, beyond the Internal Revenue Board’s powers, and unreasonable.
She wanted the court to declare that the Income Tax Act is based on territorial taxation, meaning it only applies to income earned in or received in Malaysia. She argued that she shouldn't have to provide information on foreign assets if there’s no income received in Malaysia.
Na’imah also sought a declaration that Sections 78, 79, 80 and 81 of the Income Tax Act are not blanket provisions to collate information on the income of the taxpayers accrued outside Malaysia.
Further, she wanted the court to clarify that the Income Tax Act is meant to impose tax — not to require people to explain where they got the money for their investments.
The allegations
The government alleged that Na’imah had used assets linked to Ilham Baru Sdn Bhd, Ilham Tower Sdn Bhd and Wellberton Private Equity Corp as loan collateral, claiming these assets were acquired using unreported income.
Na’imah, however, asserted that the assets were overseas properties acquired more than 20 years ago, and no income from them was received in Malaysia. He also maintained that Daim’s wealth was legally earned.
Daim passed away in Nov 2024. The case also saw former prime minister Tun Mahathir Mohamad wanting to testify for his close confidant and two-time finance minister under his administration.
Mahathir said in an affidavit that Daim did not ask for the Cabinet appointments, but it was the nation that needed him more, and Daim unselfishly responded to the call to serve the nation. “That is the calibre of the man, the patriotism that he displayed as a proud Malaysian,” Mahathir said.
Na’imah was also represented by Amira Azhar while revenue counsels Marina Ibrahim and Fatimah Roslan appeared for the Internal Revenue Board.