


This article first appeared in The Edge Malaysia Weekly on July 6, 2026 - July 12, 2026
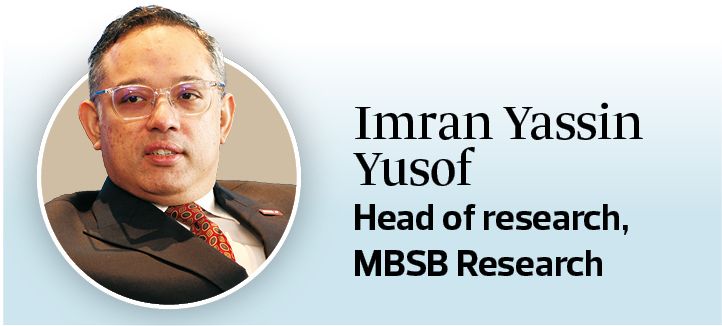
Tenaga Nasional Bhd
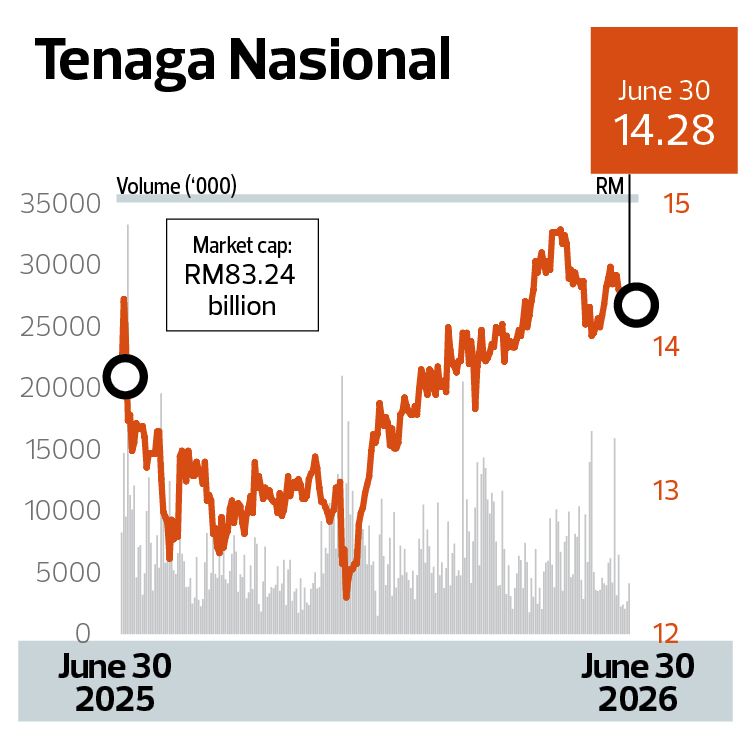
We like Tenaga Nasional Bhd (KL:TENAGA) as a core defensive anchor for 2H2026, particularly as markets may remain volatile amid the US Federal Reserve rate-hike risk, ringgit weakness and foreign fund flow uncertainty. Its regulated earnings profile, dividend support and lower earnings volatility make it suitable for an environment where investors may prefer stability and earnings visibility.
Beyond its defensive qualities, Tenaga also offers structural upside from electricity demand growth, grid investment and energy transition-related infrastructure, especially as Malaysia continues to attract high-value investments in data centres, cloud services and advanced manufacturing, all of which require reliable power supply. As such, the utility giant provides a combination of downside protection and long-term growth optionality.
CelcomDigi Bhd
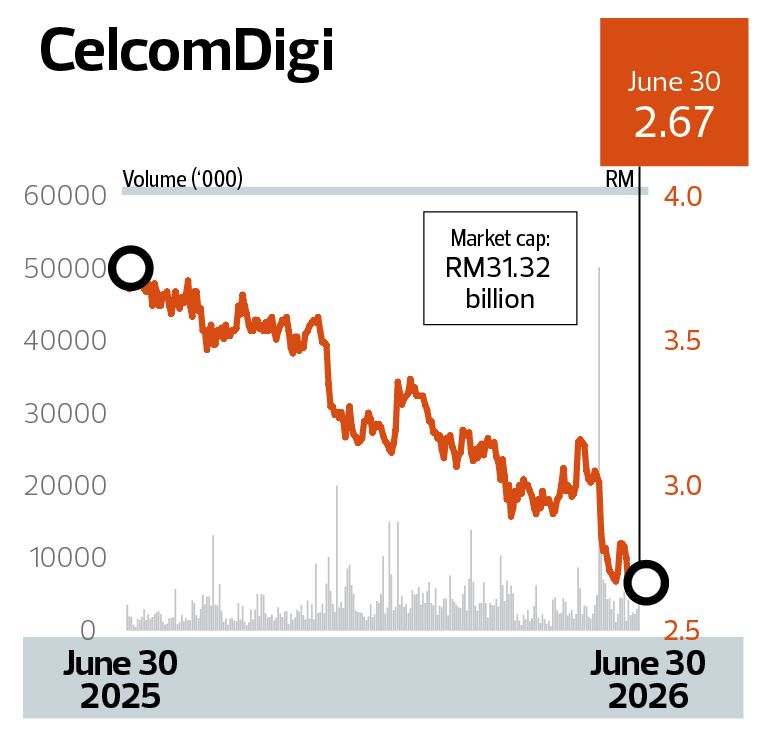
We favour CelcomDigi Bhd (KL:CDB) as a telco with defensive characteristics and recovery upside. The company offers recurring revenue visibility from mobile and connectivity services, which should help cushion earnings during periods of market uncertainty.
At the same time, CelcomDigi provides upside potential from merger synergies, cost optimisation and 5G monetisation, which could support earnings improvement over the medium term. In an environment where investors may gradually re-enter risk assets once the US Federal Reserve policy uncertainty clears, the telco offers a balanced profile — defensive enough for a cautious market, but with sufficient catalysts to participate in the recovery.
CelcomDigi is keeping its target for “low single-digit growth” in service revenue and earnings before interest and tax. In the first three months of 2026, its net profit rose nearly 9% to RM418 million from a year ago, thanks to lower operating expenses and device costs.
Hong Leong Financial Group Bhd
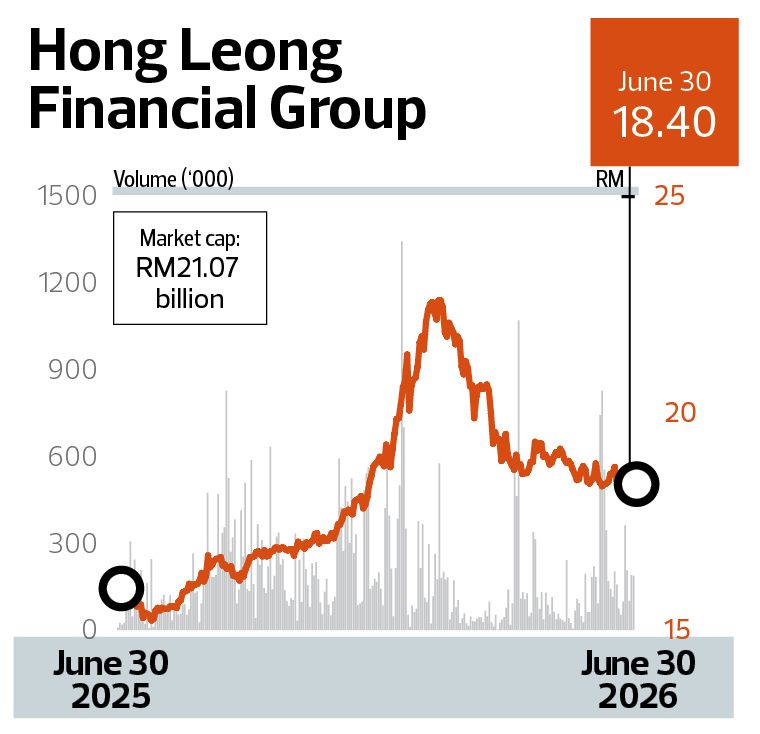
Following the share price retracement after hitting RM23.10 in February, Hong Leong Financial Group Bhd’s (KL:HLFG) share price has become more compelling, with its price-to-book value (P/B) declining to 0.6 times. It remains our top pick for the rest of the year, supported by the prospect of a higher dividend yield of about 6% arising from a corporate exercise involving its 64.23%-owned Hong Leong Bank Bhd (KL:HLBANK).
A potential sale of a stake in Bank of Chengdu Co Ltd (BoCD) by Hong Leong Bank could enhance shareholder returns. HLBB has indicated that it may eventually divest up to 5% shareholding in its 17.8%-owned BoCD as it looks to strengthen earnings contribution from its core business. Analysts expect a portion of the proceeds to be paid out as a special dividend, which will also benefit HLFG.
Duopharma Biotech Bhd
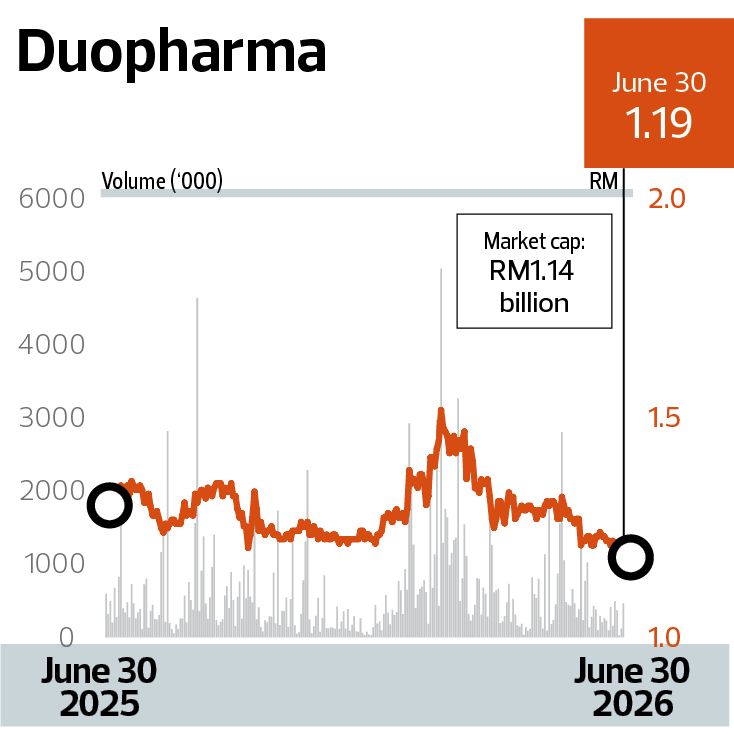
Duopharma Biotech Bhd (KL:DPHARMA) has been a key beneficiary of increased public and private healthcare spending. Last month, it secured a RM155.28 million contract to supply insulin products to public hospitals and clinics nationwide. This was followed by multiple new insulin contracts worth over RM225 million secured last Thursday.
The Middle East war led to disruptions in the supply chain and higher cost of active generic drug ingredients. With a resolution in sight for the conflict, prices of raw materials should come down.
However, its margins are also tied to ringgit movements. A weak ringgit will affect its status as an importer, given that most of its raw materials for generic drugs are imported.
Meanwhile, rising insurance premiums are expected to drive greater use of generic drugs in the private sector, further supporting demand.
UUE Holdings Bhd
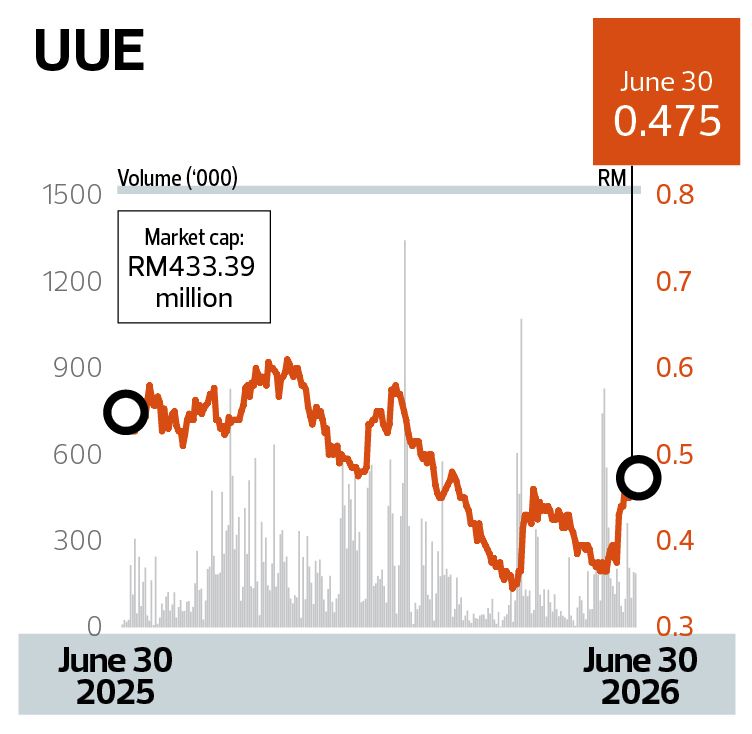
We are keeping UUE Holdings Bhd (KL:UUE) as the Johor-based utility engineering firm is expected to perform better with higher contribution from its Singapore operation. In addition, its share price appears to be more compelling now, after retracing about 10% in the first half of the year.
When announcing its latest financial results in February, the company said it had an order book of RM536.4 million. It secured RM362 million worth of new contracts in 2025 alone.
UUE is expected to continue to benefit from Tenaga’s massive power grid capital expenditure, driven by data centre expansion and rising energy demand.
Foodie Media Bhd
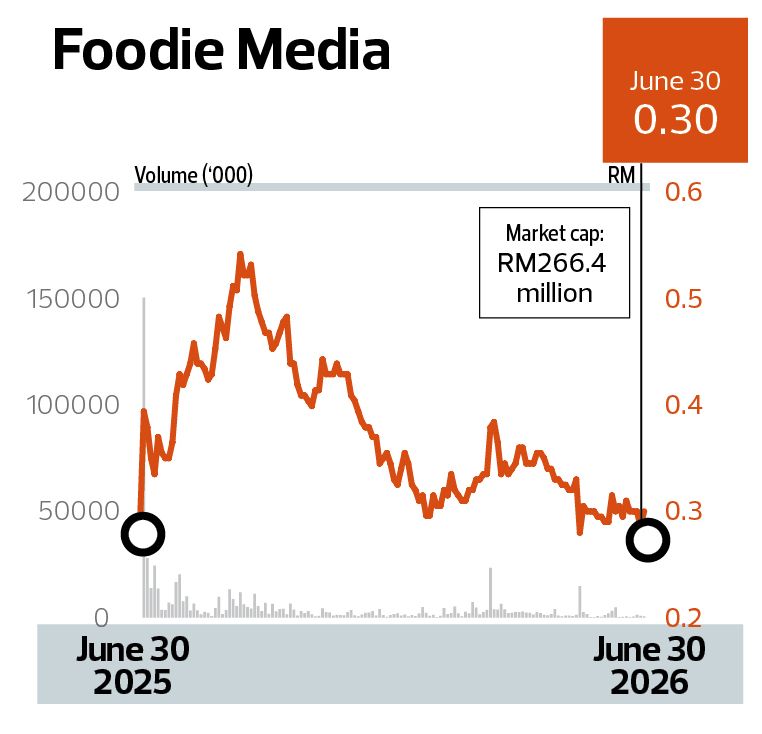
Listed in November 2025, Foodie Media Bhd’s (KL:FOODIE) share price is hovering near its initial public offering of 30 sen per share. Its price-earnings ratio (PER) of 25.8 times gives the counter an undemanding valuation.
The earnings of the digital content creator and distributor across social media platforms remain strong.
More traditional and big names are moving their adex to Foodie Media, which has 51 million followers across its brands. Through initiatives such as Monie Fest 2026, the company has been widening its vertical reach.
Sitting on a net cash position of RM51 million, Foodie Media in April declared its maiden dividend of 0.53 sen per share, which included a special dividend of 0.21 sen per share. Note that the Securities Commission Malaysia recently classified the company as non-shariah compliant, along with 17 other companies.
AirAsia X Bhd
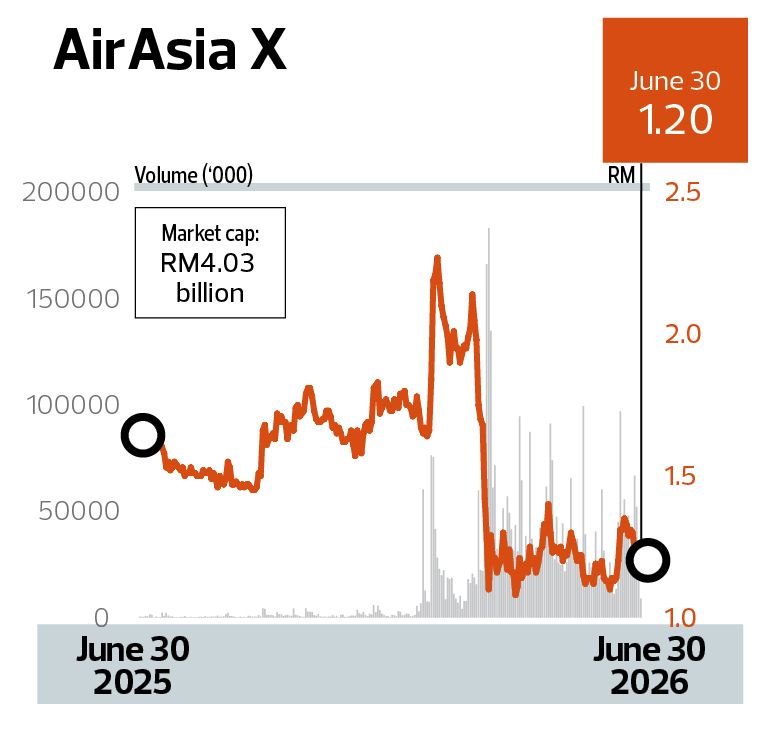
We prefer to maintain our position in AirAsia X Bhd (KL:AAX) as we believe its valuation has become increasingly attractive following the improvement in the Middle East geopolitical situation.
We expect the company’s profitability to recover in the second half of 2026 as energy prices moderate. Following the ceasefire agreement between the US and Iran, jet fuel prices have declined significantly from above US$200 per barrel to around USS$110, and are likely to fall further as concerns about supply disruptions continue to ease. Consequently, the company’s earnings outlook is expected to improve.
In the coming months, travel demand is likely to strengthen as the Northern Hemisphere enters the summer holiday season. In addition, we believe the Visit Malaysia 2026 campaign will continue to support stronger tourist arrivals in the second half of the year, providing a further boost to the company’s operating performance.
Samaiden Group Bhd
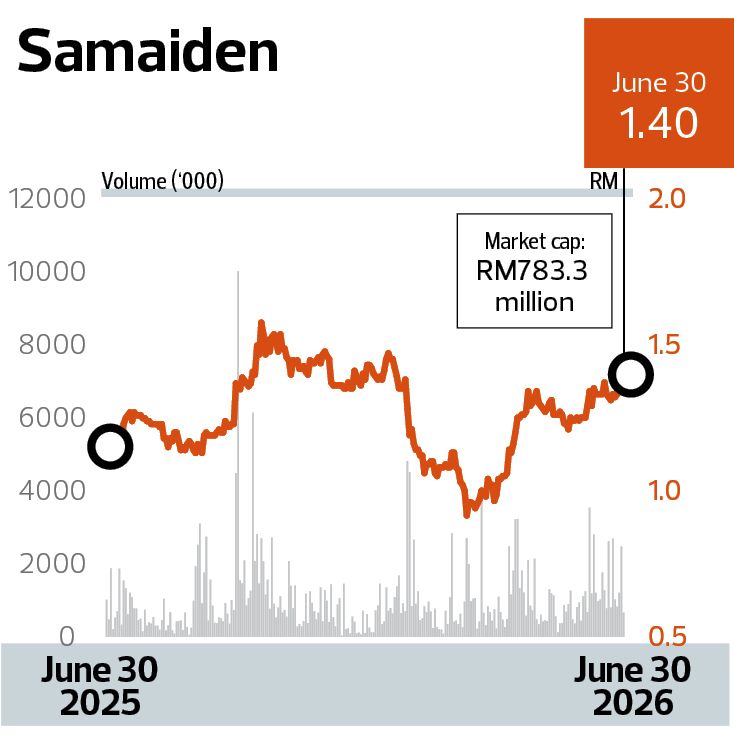
Leveraging the solar theme, Samaiden Group Bhd (KL:SAMAIDEN) is one of our preferred picks for the second half. In the first three months of the year, Samaiden posted its highest-ever quarterly net profit of RM9.12 million, driven by stronger margins from newly commenced projects as well as improved supply chain and cost management.
With an order book of close to RM500 million, this will provide sustained earnings visibility for the company. Of the orders in hand, 75% are from Large-Scale Solar projects, 20% from commercial and industrial clients and the remainder from other segments.
While engineering, procurement, construction and commissioning remains Samaiden’s primary revenue driver, the company has been expanding its renewable energy asset portfolio to enhance recurring income contribution over time.
CBH Engineering Holdings Bhd
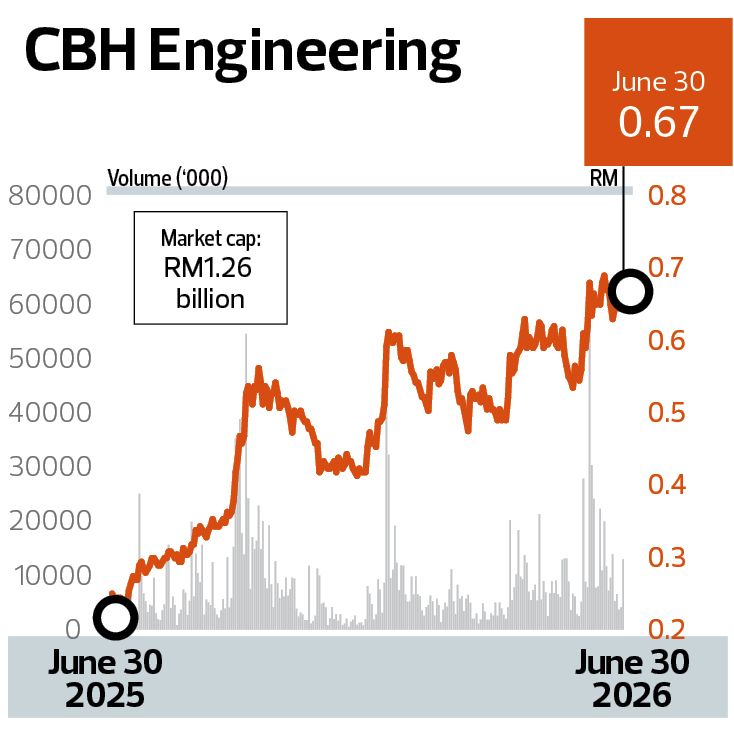
Listed in January 2025, CBH Engineering Holdings Bhd (KL:CBHB) is an electrical engineering service provider specialising in substations, power distribution systems and related infrastructure works.
The company is well positioned to benefit from Malaysia’s power infrastructure investment cycle, especially the rapid expansion of data centres. It currently has an outstanding order book of about RM580 million, providing it with healthy earnings visibility.
CBH has demonstrated strong profitability, with a net profit margin of 20.3% in the first three months of 2026, compared with 21.6% in the preceding quarter. Importantly, the company remains in a net cash position, with more than RM150 million at end-March this year. This strong balance sheet gives it greater financial flexibility and enhances its competitiveness when bidding for high-voltage substation contracts.
Southern Cable Group
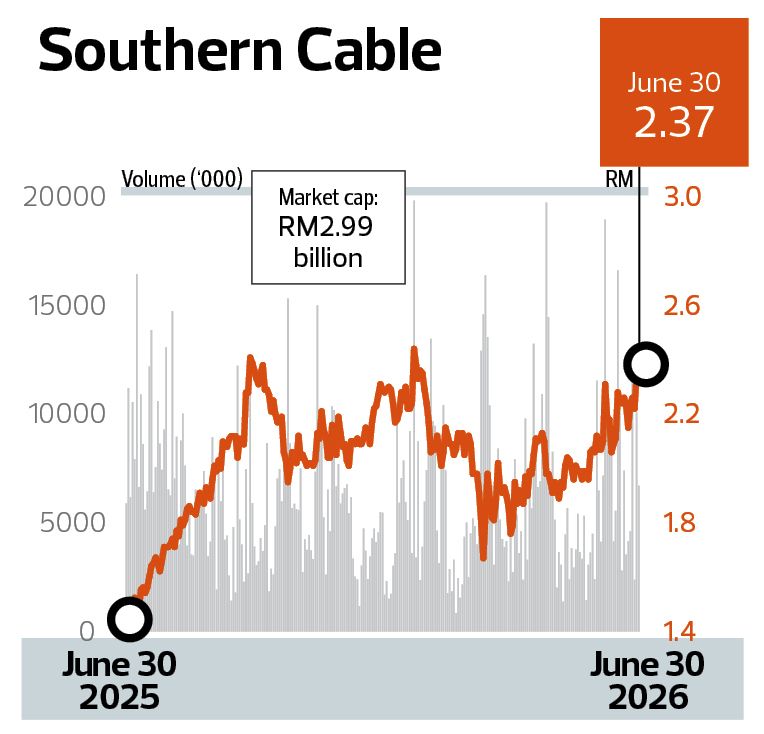
Southern Cable Group (KL:SCGBHD) is another beneficiary of the ongoing expansion in power infrastructure and data centre development. The power cable and wire manufacturer continues to benefit from the acceleration of renewable energy initiatives under the National Energy Transition Roadmap, alongside growing demand driven by data centre investments and national grid upgrades.
As at end-March, it had an outstanding order book of RM924.9 million. To meet growing demand, the company is ramping up its capacity expansion plans at its manufacturing hub in Kuala Ketil, Kedah. Upon completion, its annual cable and wire capacity is expected to reach 60,000km by end-2026 before reaching 65,000km upon full completion by end-2027, up from the current 54,980km.
Meanwhile, the fluctuations in raw material prices remain manageable, supported by the company’s existing cost-pass-through mechanisms and ongoing operational adjustments.
Read also:
Cover Story 1: Half-time reset: Repositioning for sustainable returns
Cover Story 1: The Edge’s picks
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.