


This article first appeared in The Edge Malaysia Weekly on July 6, 2026 - July 12, 2026
Able Global Bhd
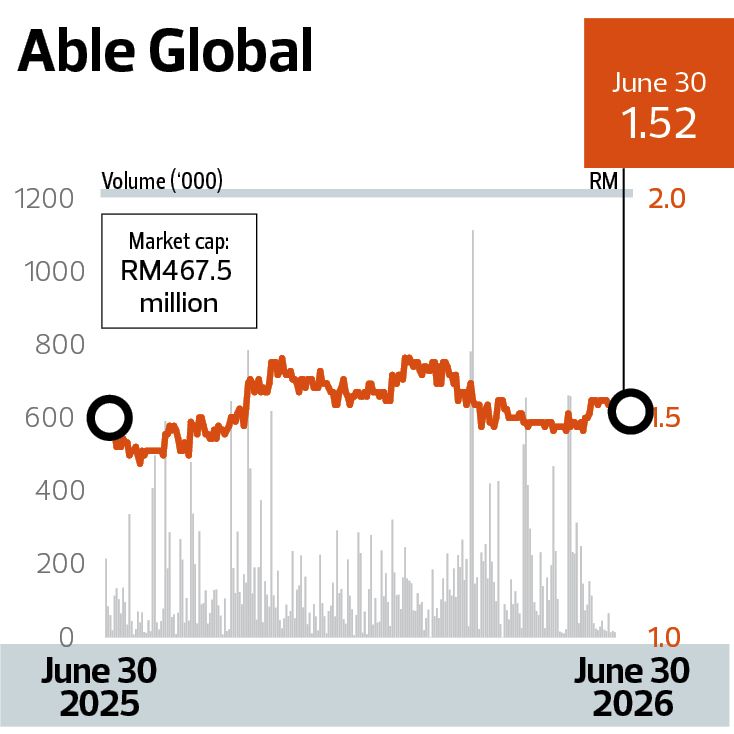
Able Global Bhd (KL:ABLEGLOB), which is involved in milk and dairy product manufacturing as well as tin can manufacturing, appears to be attractively valued at a price-earnings ratio (PER) of 6.38 times compared with the average PER of 28 times for companies in the beverage-related industry.
The group’s milk and dairy business manufactures sweetened condensed milk, evaporated milk, UHT full cream milk and flavoured milk. It is not as well known in Malaysia as its peers, given that about 80% of its dairy products are exported, mainly to West Africa, Southeast Asia and the Americas.
The group’s net profit has steadily increased over the past five financial years, rising from RM36.9 million in the financial year ended Dec 31, 2021 (FY2021) to RM71.3 million in FY2025. Its net profit margin also improved, from 7.4% in FY2021 to 10.4% in FY2025. For 1QFY2026, the group recorded a net profit of RM19.3 million on revenue of RM180.7 million.
Able Global has also increased its dividend payouts over the past three financial years, from 6.5 sen per share in FY2023 to 7.75 sen per share in FY2025, translating into a respectable trailing 12-month dividend yield of 5.2%.
PublicInvest Research is positive on Able Global’s outlook, supported by resilient demand for dairy products and improving contributions from its Mexico operations, which are expected to further boost the group’s earnings.
Sunway Real Estate Investment Trust
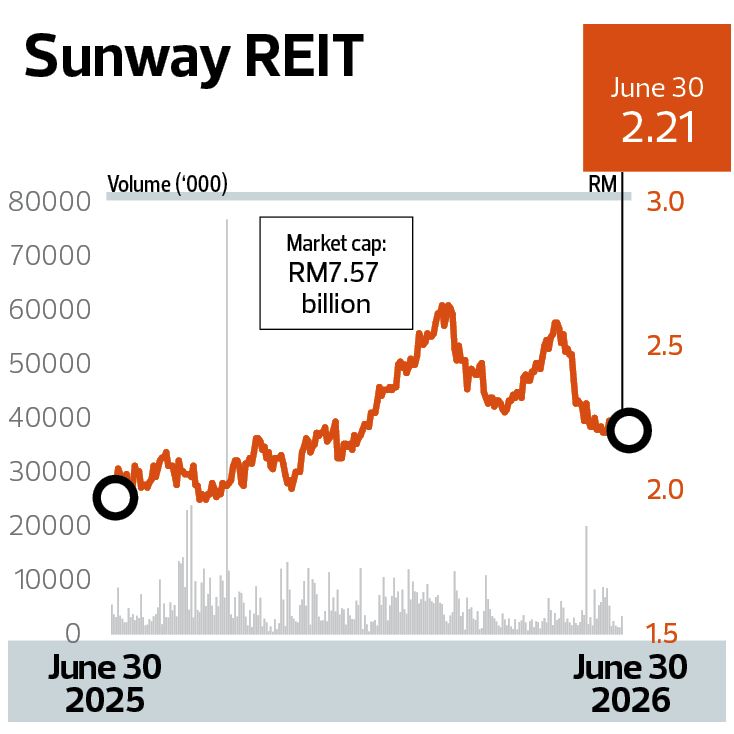
One of the most diversified real estate investment trusts (REITs) in Malaysia, Sunway REIT (KL:SUNREIT) has a portfolio comprising retail, hotel, industrial and office properties. However, the trust’s unit price has been on a downward trend, partly due to the expiry of the long-standing 10% preferential withholding tax rate on REIT distributions. Sunway REIT units have declined 5.4% year to date (YTD) to close at RM2.13 per unit on July 2. They are currently trading at a forward PER of 16.24 times.
The REIT’s first-quarter performance was driven by its retail segment, supported by resilient tenant sales and strong footfall. Occupancy improved to 98% in the three months ended March 31, 2026 (1QFY2026), from 97% in the preceding quarter, according to CGS International in a May 13 note to investors. For 1QFY2026, the REIT reported a net profit of RM114.7 million on revenue of RM223 million.
Its trailing 12-month dividend yield of 6.6% is well above the industry average of 5.6%.
Hong Leong Investment Bank Research expects Sunway REIT’s growth in FY2026 to be driven mainly by organic initiatives, with capital expenditure (capex) focused on asset enhancement initiatives (AEIs) and ongoing development projects. More meaningful earnings contributions are expected from FY2028 onwards, particularly from the new Seberang Jaya hotel in Penang and Sunway Pier Mall in Port Klang, Selangor.
AMMB Holdings Bhd
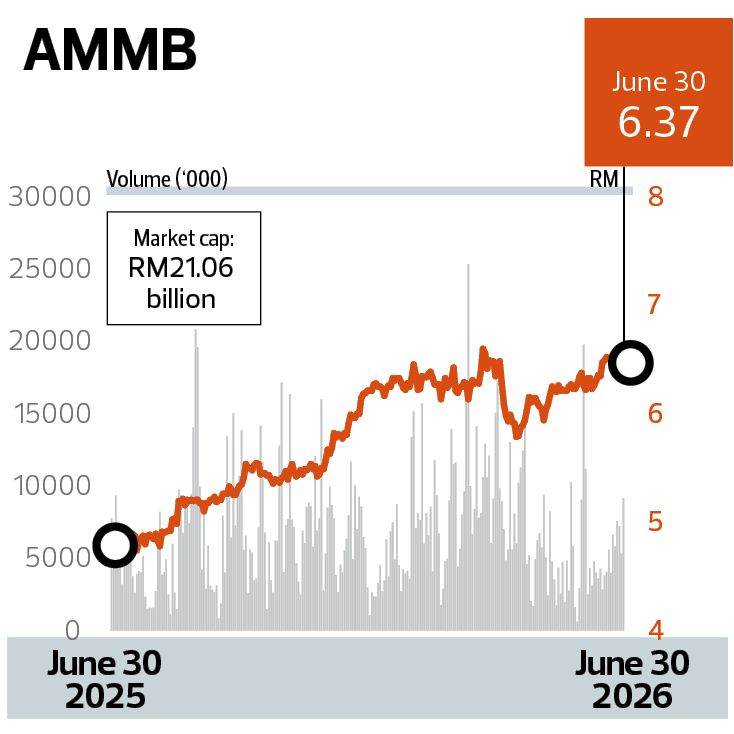
AMMB Holdings Bhd (KL:AMBANK) is one of the banking groups in the country with a relatively attractive price-to-book (P/B) ratio — it trades at one time, compared with most of its peers, which are trading above that.
Over the past year, AMMB’s share price has risen a substantial 33% to close at RM6.40 last Thursday. Over a five-year period, the stock has gained slightly more than three times.
Investors have been encouraged by the banking group’s commitment to dividend payouts. For the financial year ended March 31, 2026 (FY2026), AMMB declared a total dividend of 35 sen per share, representing a payout ratio of 55%, up from 50% in the previous financial year.
This came after it achieved a record net profit of RM2.1 billion in FY2026, driven by a 4.5% increase in net interest income and a 5.1% rise in non-interest income.
Analysts believe AMMB remains committed to rewarding shareholders through dividends. Under its Winning Together 2029 strategy, the bank aims to double its dividend per share by 2029, supported by earnings growth and capital optimisation.
In a June 15 report, CIMB Securities said that as AMMB’s earnings visibility strengthens and payout ratios increase, the group will offer one of the sector’s more attractive combinations of dividend growth, capital optionality and valuation upside.
Kerjaya Prospek Group Bhd
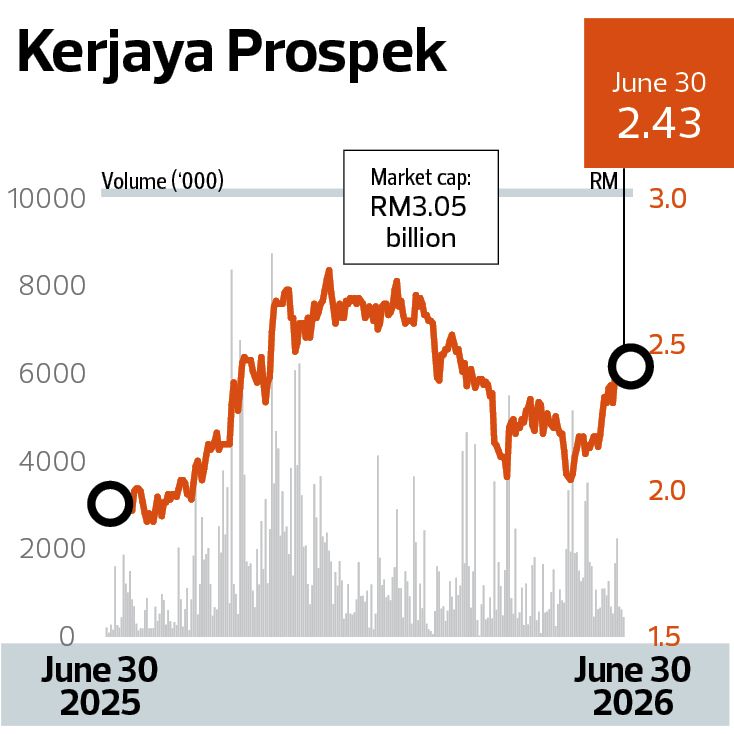
Among companies in the construction sector, Kerjaya Prospek Group Bhd (KL:KERJAYA) has one of the lowest PERs at 12.8 times and one of the most attractive trailing 12-month dividend yields at about 5%.
Although its share price has shed 8.3% YTD, closing at RM2.40 last Thursday, FY2026 is shaping up to be a strong year for Kerjaya Prospek. The group has secured RM2.1 billion worth of new projects YTD, exceeding its own FY2026 target of RM2 billion. This has lifted its total order book to RM5 billion as at June 30.
RHB Research said in a June 23 report that Kerjaya Prospek has three potential projects in the pipeline for the remainder of FY2026. The construction group also benefits from the support of its subsidiaries, Eastern & Oriental Bhd (KL:E&O) and Kerjaya Prospek Property Bhd (KL:KPPROP), which provide a steady stream of contracts.
Of the eight contracts secured in FY2026, five were related-party transactions, with four awarded by E&O and one by Kerjaya Prospek Property. As a result, between 70% and 80% of the group’s RM5 billion order book comprises projects from related parties.
A key catalyst to watch is whether Kerjaya Prospek will secure a package for the Penang Light Rail Transit project, which would further boost the group’s growth prospects.
Sarawak Oil Palms Bhd
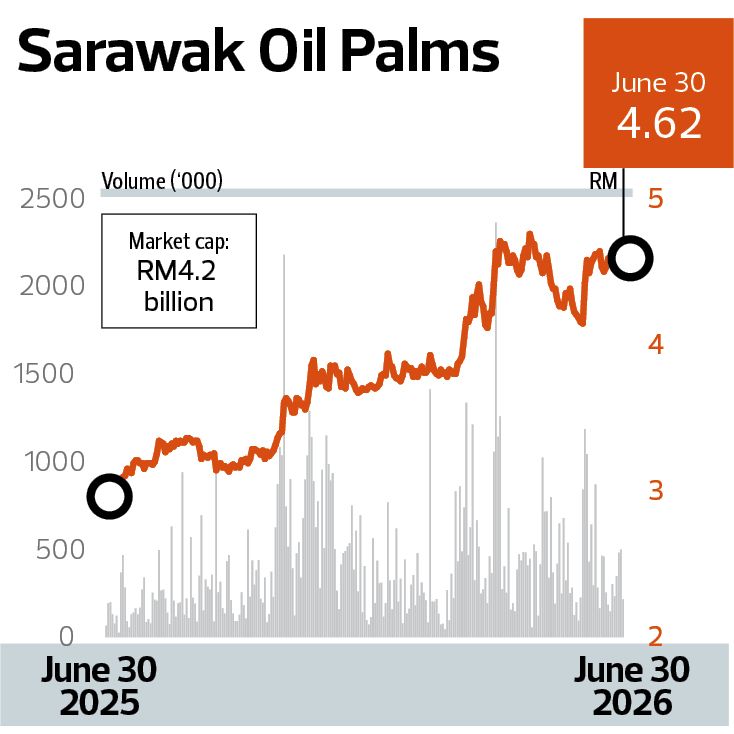
Expectations of a stronger El Niño have reinforced the positive outlook for plantation stocks, as weather-related supply concerns are likely to support the current elevated crude palm oil (CPO) prices.
Within the sector, we favour Sarawak Oil Palms Bhd (KL:SOP), whose valuation remains relatively undemanding. The stock trades at a PER of about 11 times, lower than those of its larger peers. As at end-March 2026, the company had a net cash position of RM1.36 billion, a substantial amount relative to its market cap of RM4.2 billion.
Another potential catalyst for CPO prices is Indonesia’s proposed natural resources export governance framework, under which all export transactions would be channelled through Danantara Sumberdaya Indonesia. Although the Indonesian government is reportedly considering scaling back the proposal, tighter export monitoring is still expected.
Sarawak Oil Palms also benefits from a favourable tree age profile. Prime trees aged between 11 and 20 years — the most productive phase for oil palm trees in terms of fresh fruit bunch (FFB) yield — accounted for more than 70% of its mature planted area in the financial year ended Dec 31, 2025 (FY2025).
Its trailing 12-month dividend yield of 3.8% is another positive, supported by the company’s track record of progressively increasing its dividend payouts.
KESM Industries Bhd
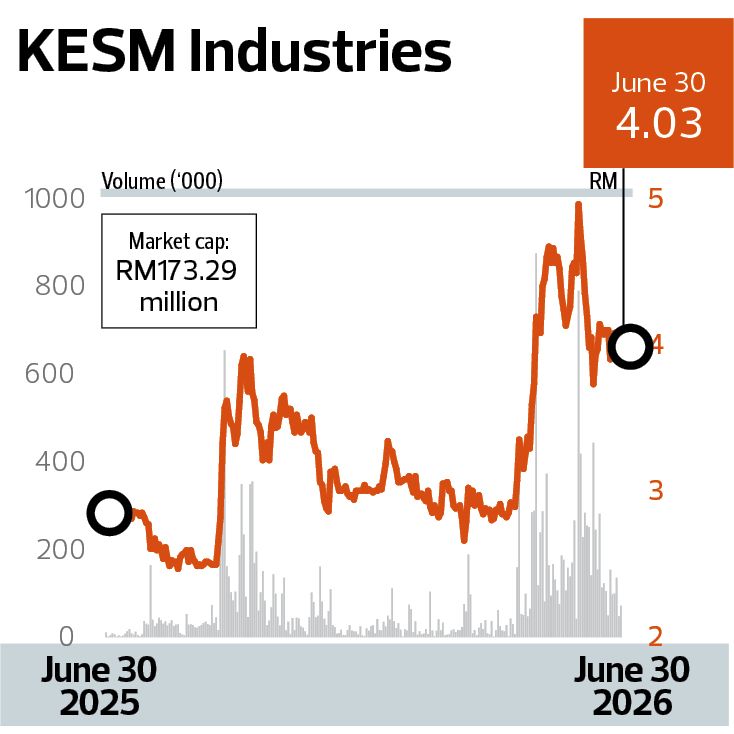
KESM Industries Bhd (KL:KESM), the world’s largest independent burn-in and test service provider, has seen its share price jump by more than 30% since the start of the year.
While KESM trades at a PER of below 30 times — a discount to many technology peers, which command valuations of more than 50 times — the lower multiple is partly justified by its relatively small market cap and history of core operating losses.
It is worth noting that KESM’s headline profits in recent quarters were boosted by one-off gains. The company recorded losses in two of the past five financial years. For the first nine months ended April 30, 2026, it reported a net profit of RM6.64 million compared with a net loss of RM8.41 million a year earlier.
Over the past three years, KESM has invested RM146.27 million to enhance its capabilities in providing burn-in and test services for more advanced applications, while expanding its portfolio and capacity to better serve the electric vehicle, power management and artificial intelligence (AI) markets.
Burn-in and testing are critical stages in semiconductor manufacturing, carried out before devices undergo comprehensive functional and electrical testing to ensure they meet stringent performance standards.
Should these higher-value segments begin contributing meaningfully, they could provide a significant boost to the company’s earnings. KESM also maintains a strong balance sheet, with a net cash position of RM184.4 million, slightly exceeding its market cap of about RM173.29 million.
MN Holdings Bhd
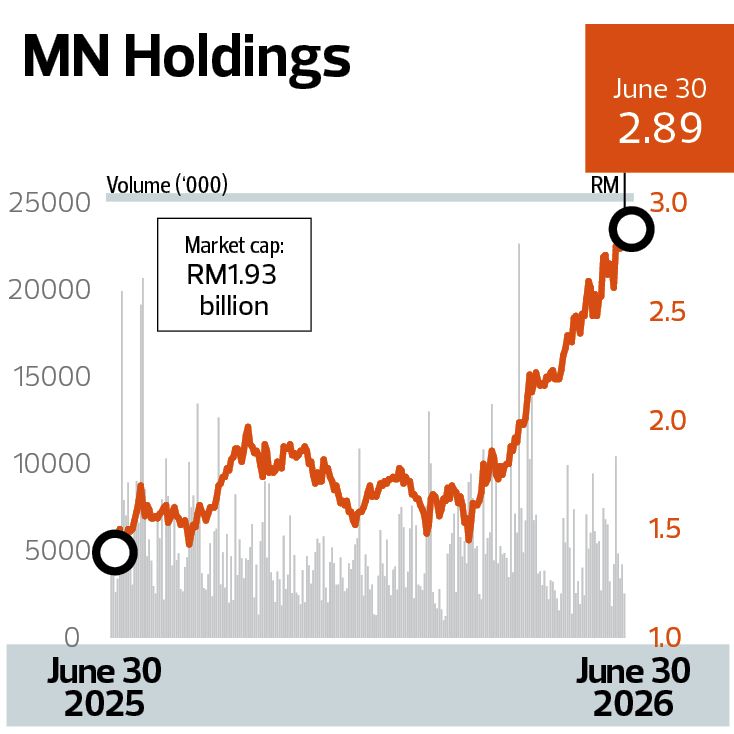
MN Holdings Bhd (KL:MNHLDG), which specialises in underground utility engineering and substation engineering services and solutions, is well positioned to benefit from Malaysia’s data centre boom, having secured sizeable contracts in the sector while continuing to win projects from Tenaga Nasional Bhd (KL:TENAGA).
Although the stock has gained more than 70% since the start of the year, its healthy order book and sustained momentum in securing data centre-related contracts could provide further upside.
Analysts expect MN Holdings’ net profit to double to nearly RM100 million in the financial year ended June 30, 2026 (FY2026), from a record RM48.22 million in FY2025.
The company has an outstanding order book of about RM1.6 billion, of which 70% is linked to data centre projects.
Furthermore, the potential listing of YTL Power International Bhd’s (KL:YTLPOWR) data centre business could serve as a rerating catalyst for the broader power infrastructure sector.
Beyond data centres, MN Holdings is positioning itself for growth in the renewable energy sector by preparing to undertake engineering, procurement, construction and commissioning (EPCC) works for solar projects, including battery energy storage systems (BESS), which could provide a recurring income stream over the longer term.
Tenaga Nasional Bhd
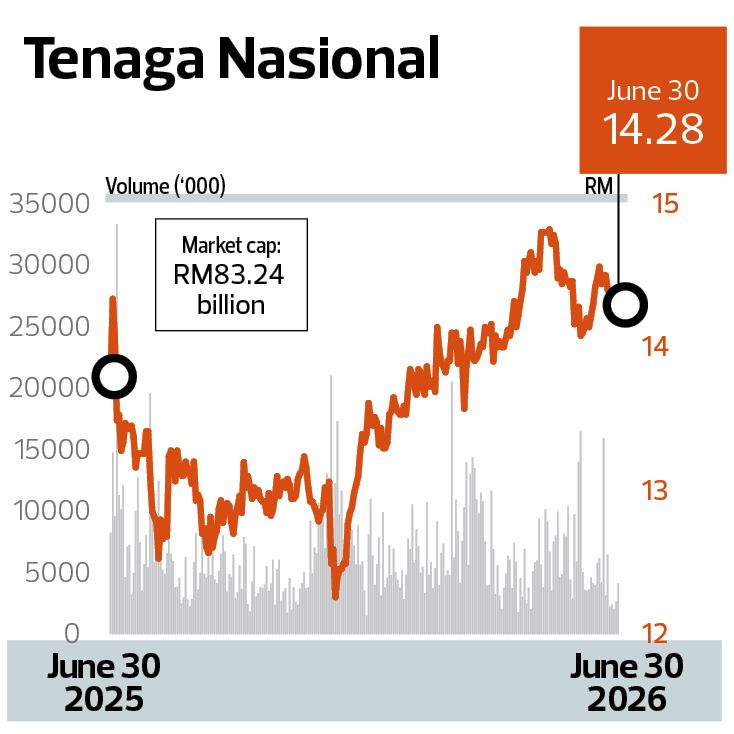
Tenaga Nasional Bhd (KL:TENAGA) is our preferred utility stock for the second half of the year, underpinned by the implementation of the National Energy Transition Roadmap (NETR) and its position as a key beneficiary of Malaysia’s energy transition through higher grid capex to support greater renewable energy penetration.
The utility giant plans to spend RM43 billion in capex between 2025 and 2027, and RM47 billion over the 2028-2030 period.
Tenaga is also expected to benefit from the country’s resilient economic growth despite uncertainty arising from geopolitical risks in the Middle East. Although electricity demand from the industrial segment softened in the first quarter of the year, analysts expect overall electricity demand growth to remain healthy in 2026, supported in part by continued data centre developments.
The consensus target price for Tenaga is RM16.50, implying a potential upside of about 15.7% from last Thursday’s closing price of RM14.26.
Read also:
Cover Story 1: Half-time reset: Repositioning for sustainable returns
Cover Story 1: Picks by fund managers and heads of research
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.