

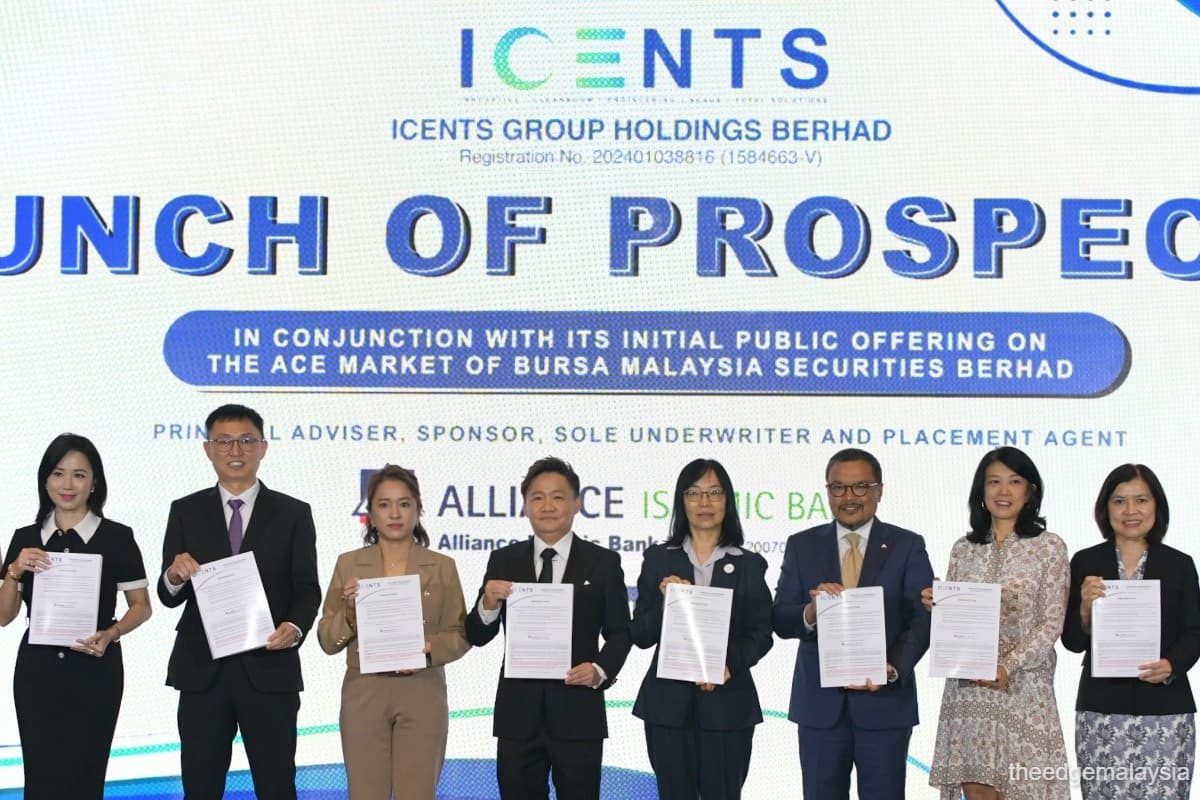
KUALA LUMPUR (July 1): iCents Group Holdings Bhd, en route to the ACE Market, offers capital upside of as much as 21% from its listing price from strong projected earnings growth, two research houses said.
The company, which builds cleanrooms for data centres and pharmaceuticals, would be valued fairly at 29 sen compared to its listing price of 24 sen, according to Apex Securities and TA Securities. Even at the target price, iCents would still be undervalued relative to its select peers, the houses noted.
“We believe this is fair” as iCents has a smaller market capitalisation despite its stronger return on equity relative to peers, said TA Securities.
Applications for the iCents’ initial public offering (IPO) shares will close on July 2 and the listing has been scheduled for July 17. The IPO aims to raise up to RM34.2 million for iCents and its shareholders.
iCents is mainly involved in providing cleanroom services, including engineering, procurement, construction and testing and commissioning of cleanrooms catering to semiconductor and electronics manufacturing, data centres, pharmaceuticals and life sciences sectors.
Beyond the niche services, the company also provides a range of facility services, including machinery and equipment hook-up, supply and installation of heavy-duty ceiling systems, construction works and maintenance services for various facilities.
Apex Securities is projecting a near-50% surge in net profit to RM10.3 million this year on the back of additional variation orders secured for cleanrooms at a semiconductor manufacturing plant in Kulim and the start of work for a cold room for a palm oil products manufacturing plant in Medan.
Margins are also expected to improve on better cost and quality controls, the house said, noting that once its new Mantin factory is operational by the end of 2025, iCents would be able to bring in new machinery and equipment to improve its in-house production capability.
Public Investment Bank, meanwhile, values iCents at 26 sen after taking into account an average annual earnings growth of about 20% over the next three years.
iCents is “positioning itself well to benefit from Malaysia’s emergence as a digital infrastructure hub”, supported by geographical market expansion as well as increasing investment for data centres, the house added.