

This article first appeared in Capital, The Edge Malaysia Weekly on November 9, 2026 - November 15, 2026
Renewable energy
Overweight
UOB KAY HIAN RESEARCH (NOV 3): Minister of Energy Transition and Water Transformation (PETRA) Datuk Seri Fadillah Yusof recently announced in Parliament that the government has approved a requirement for data centres (DCs) in Malaysia to source at least 30% of their energy from renewable energy (RE), based on their total installed capacity or energy consumption.
Against this backdrop, we expect a total addressable market of RM20 billion, based on a development cost of RM5 million/mw and 4gw of cumulative demand over the next five years. Tenaga Nasional Bhd (KL:TENAGA) expects a total of 13gw of power demand from DCs over the next three to five years. At 30% of the 13gw demand outlook, we believe at least 4gw-5gw of RE is up for negotiation in the next three to five years. Sizeable land bank is an important leverage when negotiating for Corporate Renewable Energy Supply Scheme (CRESS) projects.
PETRA previously disclosed that the CRESS programme has attracted 11 applicants representing a combined capacity of 3gw. We expect the pace of CRESS wins to accelerate by December 2026, considering that only about 50% of the identified CRESS projects have been publicly disclosed thus far. Against this backdrop, we believe Solarvest Holdings Bhd (KL:SLVEST), Pekat Group Bhd (KL:PEKAT) and Northern Solar Holdings Bhd (KL:NORTHERN) will have to finalise CRESS projects within the next two months. Based on the terms of the CRESS Acceleration Package, the plant must be commissioned by Dec 31, 2028. Construction period takes 18 to 24 months.
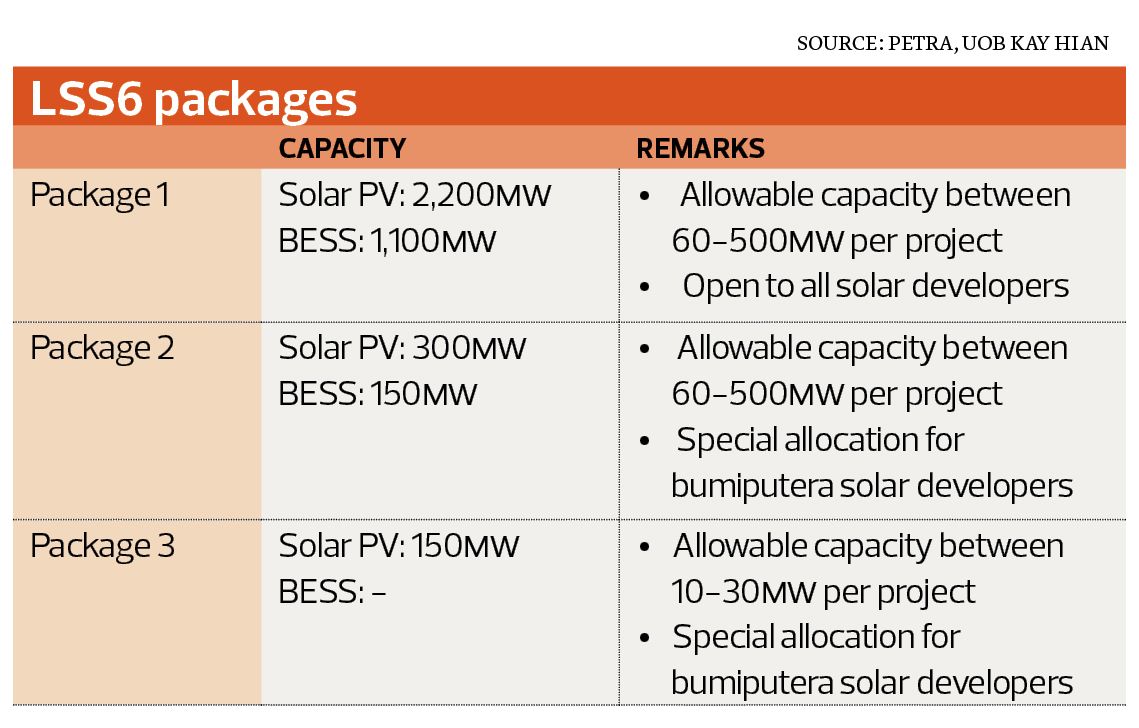
Tender submission for Packages 1 and 2 of the Large-Scale Solar 6 (LSS6) tender closed on Oct 27. We expect the government to announce the successful bidders in 1H27.
We expect LSS6 engineering, procurement, construction and commissioning (EPCC) contracts to be progressively dished out in 2H27, paving the way for construction activities to begin in 2028 and meet the targeted commercial operation date of Dec 31, 2029. Based on an estimated captal expenditure of RM4 million to RM4.5 million per mw for a solar-plus-battery energy storage system (BESS), we expect a total of RM10 billion to RM11 billion in EPCC jobs to be dished out under LSS6.
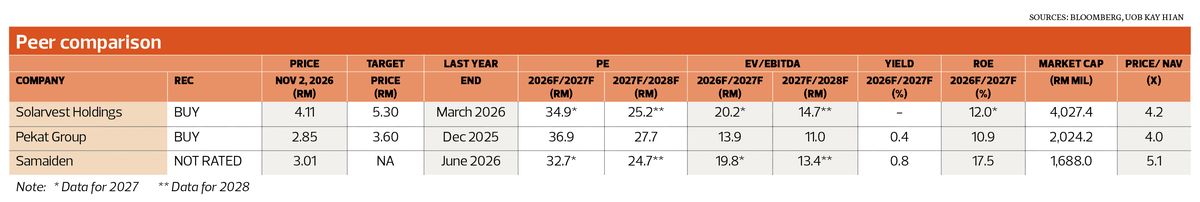
Solarvest is poised to remain a primary beneficiary, as the group aims to maintain 25% share of the utility-scale EPCC market. Our channel checks suggest that Solarvest and Pekat each possess the execution capacity to undertake 500mw of EPCC contracts, while Northern Solar is capable of delivering approximately 150mw of EPCC works.
We maintain an “overweight” call, top picks being Solarvest and Pekat.
IGB REIT
Target price: RM3.05 BUY
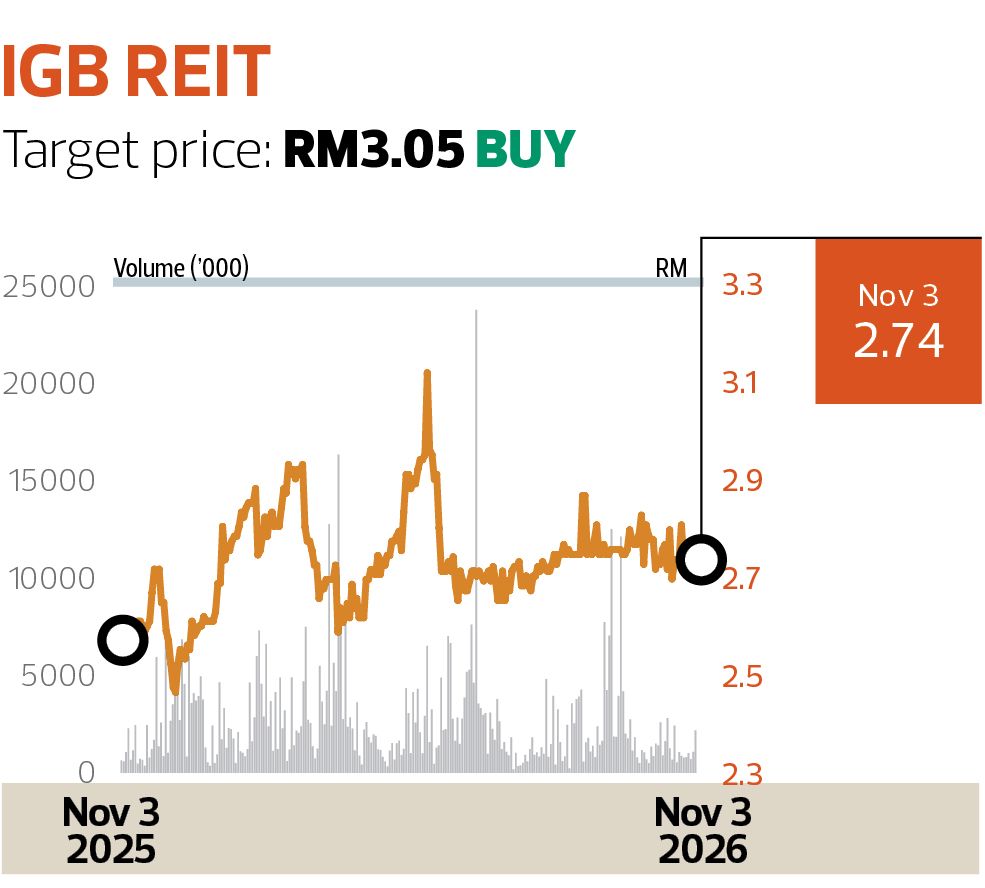
AMINVESTMENT BANK RESEARCH (NOV 2): We maintain our “buy” call on IGB REIT (KL:IGBREIT) and target price; it implies a gross target yield of 5.1% and a spread of 120 basis points compared to 10-year Malaysian Government Securities, where both are valued close to -0.5 Standard Deviation from their 10-year mean. The slight premium is warranted, given its stronger financial profile, with return on equity and interest coverage ratio improving about two percentage points. We continue to favour IGBREIT for its strong execution track record.
All three IGBREIT malls are bustling in 3Q26, with tenant sales rising across the board: luxury spending made a comeback at The Gardens Mall, Kuala Lumpur, The Mall, Mid Valley Southkey in Johor Bahru gained traction, while Mid Valley Megamall, KL, chugged along steadily. IGBREIT could be included into the proposed FBM KLCI expansion to 50 constituents (about 1% weight), which acts as a positive catalyst over the shorter term as well.
We view IGBREIT’s debt structure positively, seeing that 91% of its borrowings are on fixed rates, providing a strong buffer against interest rate volatility. Ahead of the RM1.2 billion medium-term note maturity in 3Q27, management continues to favour locking in long-term rates. That said, we believe IGBREIT has some flexibility should yields stay elevated, including tapping shorter-term instruments while awaiting more favourable refinancing conditions.
Infomina Bhd
Target price: RM2.40 OUTPERFORM
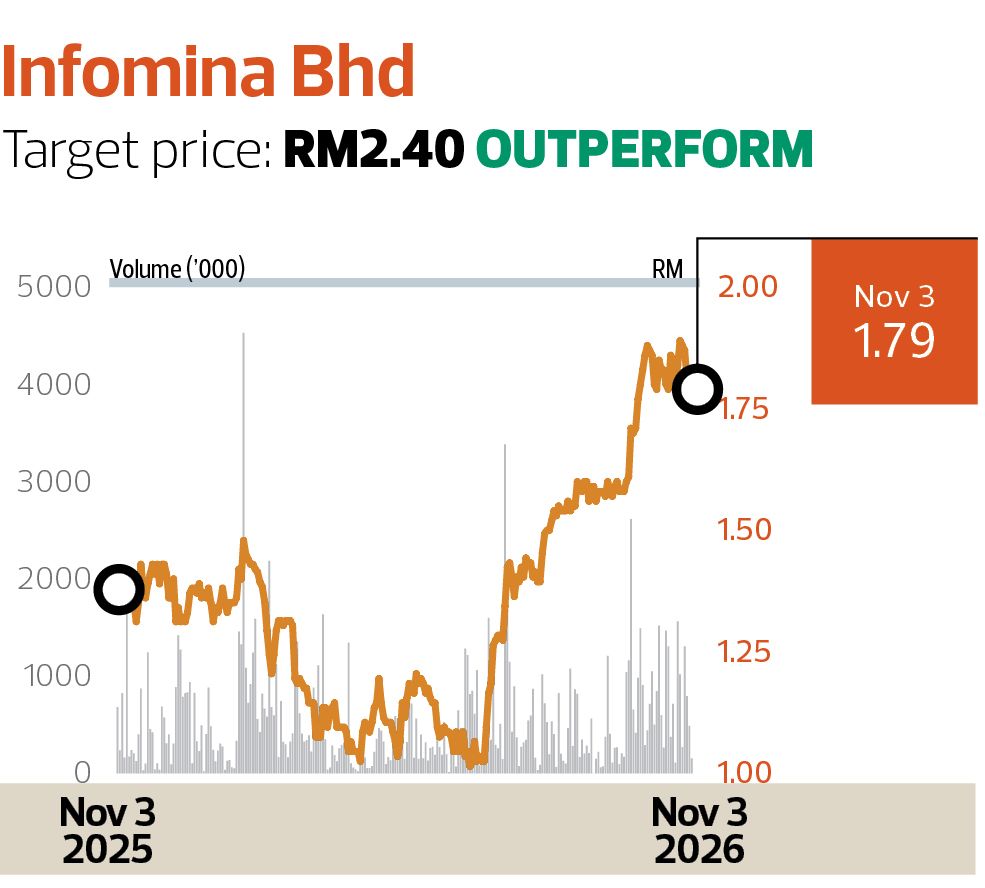
KENANGA RESEARCH (NOV 3): Infomina Bhd (KL:INFOM) has secured a five-year appointment from Broadcom to distribute and support its Agile Operations Division software portfolio across 13 Asia-Pacific markets, effective November 2026. The new appointment complements its existing mainframe software business, expanding its offerings into enterprise automation, network operations and value stream management. This further strengthens Infomina’s long-standing partnership with Broadcom and complements its existing mainframe software division distribution business.
We view this positively, as it broadens Infomina’s addressable market, enhances cross-selling opportunities and provides a potential new recurring revenue stream. The appointment also aligns with management’s strategy to develop a more diversified enterprise software business beyond traditional mainframe technologies. Nevertheless, we maintain our FY2027/28F (ended May 31) earnings forecasts pending clarity on the financial contribution. We reaffirm our “outperform” with an unchanged target price, based on 25 times FY28F PER.
This multiple is anchored to the three-year historical blended average PER of selected listed peers — Kronologi Asia Bhd (KL:KRONO), Cloudpoint Technology Bhd (KL:CLOUDPT) and LGMS Bhd (KL:LGMS) — and is broadly consistent with Infomina’s historical valuation, at approximately +1 Standard Deviation above its three-year mean.
Econpile Holdings Bhd
Target price: 24 sen ADD
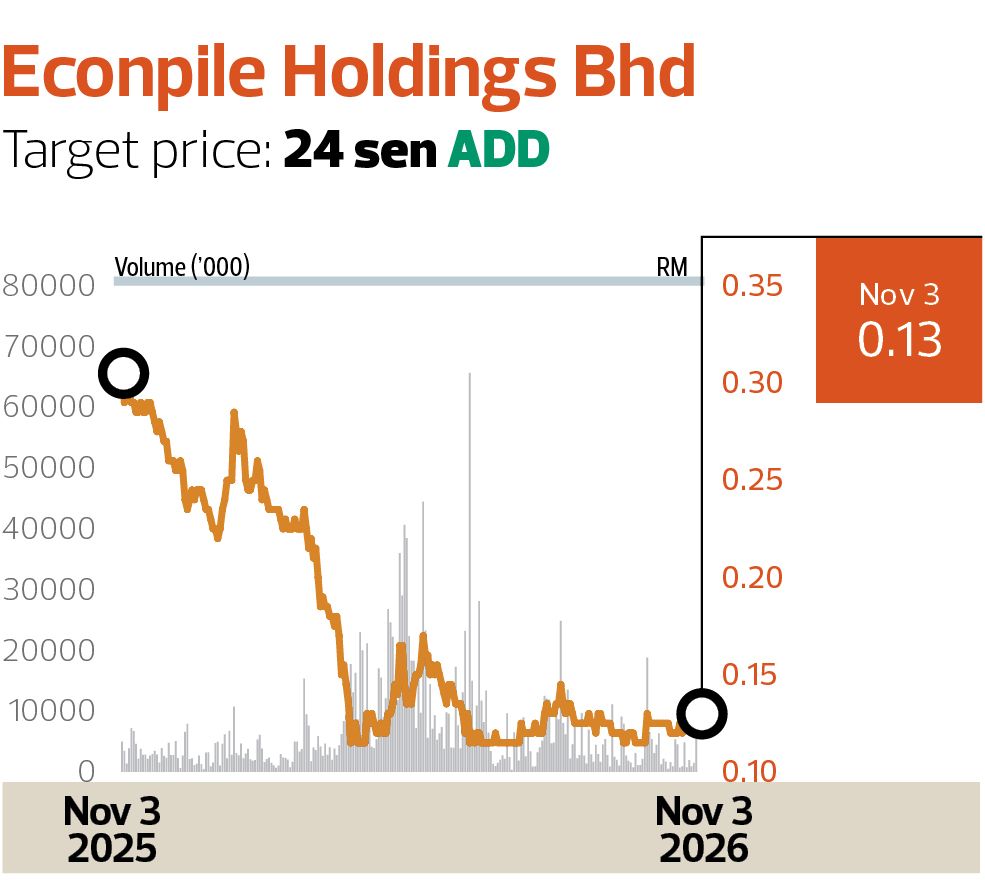
CGS INTERNATIONAL (NOV 2): Econpile Holdings Bhd (KL:ECONBHD) announced a RM73 million hospital demolition and piling project win. Its year-to-date wins for FY27 (ended June) amount to about RM165 million, bringing its order book to RM630 million as at November.
The gross profit margin (GPM) guidance for this hospital project is 9% to 10% despite the more complex nature of the works, as we understand that the tender was highly competitive. Econpile has set an official contract win target of RM450 million for FY27 (compared with RM405 million achieved in FY26), with an FY27F GPM target of about 9% to 10% (CGSI Research: 9%).
Econpile’s balance sheet remains strong, with net gearing of 0.08 times as at June 30, supported by robust operating cash flow. We believe this should put the company in a better position than its peers to weather the current high-cost environment. We reiterate our “add” and target price, based on 24 times CY27F PER (1 Standard Deviation above mean since FY22). We think the stock is grossly oversold, trading at an all-time low of just 0.5 times FY26F P/B ratio, at the lower end of its valuation range since FY22.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.