

This article first appeared in Capital, The Edge Malaysia Weekly on November 9, 2026 - November 15, 2026
POWER infrastructure contractor SKA Capital Bhd (KL:SKACAP) is positioning itself to capture a larger share of infrastructure projects by expanding its technical capabilities, particularly in engineering, procurement, construction and commissioning (EPCC) works and underground utilities.
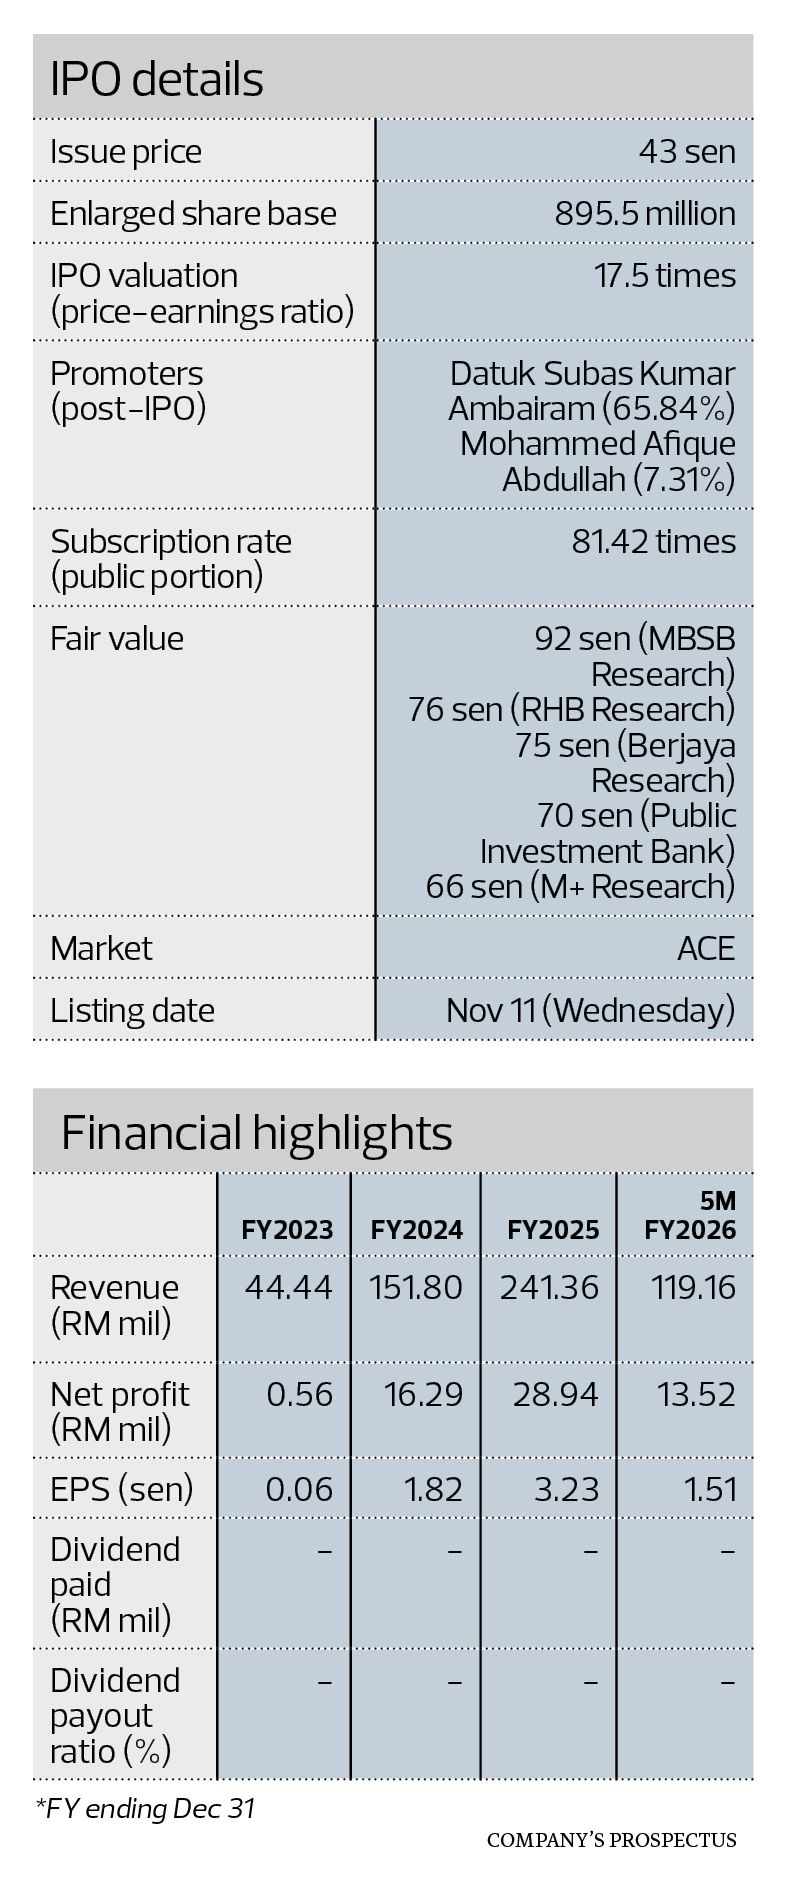
Slated to list on the ACE Market on Nov 11, its initial public offering (IPO) comprises a public issue of 168.08 million new shares and an offer for sale of 72.4 million existing shares, both priced at 43 sen apiece. Based on its enlarged share capital, the IPO price implies a trailing price-earnings ratio (PER) of about 17.5 times its core net profit for the financial year ended Dec 31, 2025 (FY2025).
The public issue is expected to raise RM72.3 million, of which RM32.7 million or 45.2% will be allocated to working capital. Another RM21 million will be used to secure performance bonds for future projects, while RM12.1 million has been earmarked for machinery and equipment, particularly five horizontal directional drilling (HDD) machines.
The investment will allow the group to undertake more underground cable-laying works in-house, reducing its reliance on rented equipment and subcontractors, and potentially improving cost efficiency and margins. The remaining RM6.5 million will go towards its listing expenses.
Founded in 2009 by managing director Datuk Subas Kumar Ambairam, SKA Capital provides power infrastructure engineering solutions through three main business segments — substation engineering, underground utilities engineering and the trading of electrical equipment and construction materials.
Its capabilities span distribution and transmission projects ranging from 11kV to 500kV. A significant step in broadening its technical capabilities was the acquisition of a 70% stake in Reltency Engineering Services Sdn Bhd for RM5 million in February 2025. The acquisition led the group to expand beyond its traditional civil and structural engineering (C&S) works, enabling it to secure larger-scale 500kV EPCC contracts.
Among the key projects it has won are the 500kV substation works for Tenaga Nasional Bhd and underground utilities for data centres. These include the RM55 million Kempas Lama data centre landing station in Johor, its largest contract to date, as well as several gas-insulated switchgear (GIS) substation projects, each worth more than RM40 million.
The group is also undertaking two projects in Elmina, Selangor, worth a combined RM81.1 million, involving underground utilities for a data centre and substation.
As at Oct 26, 2026, the group had an outstanding order book of RM402.7 million, equivalent to about 1.7 times its FY2025 revenue. Underground utilities engineering projects accounted for 78% of the order book, while C&S and EPCC works made up 11% each.
Of the total, RM79.6 million is expected to be recognised in FY2026, with the rest scheduled for FY2027 and FY2028, providing up to three years of revenue visibility.
Looking ahead, SKA Capital aims to tap opportunities in higher-voltage transmission substations and larger underground utilities packages. Its CIDB Grade G7 contractor registration allows it to tender for projects of unlimited value, while its registration as a Tenaga supplier and service contractor strengthens its credentials in the utility sector.
Underground utilities emerging as key growth driver
SKA Capital is also stepping up its focus on underground utilities engineering, a segment it entered in 2025 after securing its first RM50 million project involving the installation, testing and commissioning of 11kV underground cables and accessories.
Although the segment contributed only RM9.5 million or 3.9% to group revenue in FY2025, it has since expanded rapidly. Segment top line rose to RM25.7 million in the first five months of FY2026 (5MFY2026), accounting for 21.5% of group revenue. It has also become the group’s largest order book contributor, making up 78% of outstanding contracts as at Sept 21, 2026.
The segment’s growing contribution has also supported an improvement in the group’s margins. The segment recorded a gross profit margin of 33.3% in 5MFY2026, compared with the group’s overall gross profit margin of 24.3% during the same period.
Overall, SKA Capital’s revenue expanded 59% year on year to RM241.4 million in FY2025, from RM151.8 million in FY2024. The growth was supported by contributions from Reltency’s EPCC and electrical and mechanical engineering businesses, alongside the maiden revenue contribution of the underground utilities engineering segment.
Reported net profit rose from RM16.3 million in FY2024 to RM28.9 million in FY2025, although the latter included a one-off reversal of impairment on related-party balances amounting to RM7.2 million. Excluding that, core net profit increased 24.6% to RM21.7 million.
The positive momentum continued into 5MFY2026, with revenue surging 45.4% year on year to RM119.2 million, while profit after tax and minority interests increased 163.2% to RM13.5 million. Gross profit margin improved to 24.3% from 15.6% a year earlier, reflecting the higher contribution from the underground utilities segment and improved margins in substation engineering.
Based on the consensus estimates of five research houses, SKA Capital’s core net profit is projected to grow 43.4% to RM31.54 million in FY2026, followed by a further increase of 32.3% to RM41.74 million in FY2027.
Among the research houses, MBSB Research has the most optimistic earnings projections, with a forecast core net profit of RM30 million in FY2026 and RM48.3 million in FY2027, compared with RM22 million in FY2025. At the other end of the spectrum is M+ Research, which expects core net profit to reach RM31.3 million in FY2026 and RM35.8 million in FY2027.
Most research houses have adopted a forward PER of about 17 times in arriving at their respective fair value, which ranges from 66 sen to 92 sen, implying capital upside potential of 53.5% to 114% from the IPO price. MBSB Research has the highest fair value of 92 sen, based on 17 times its FY2027 forecast earnings, while M+ Research has the lowest at 66 sen, based on 16.5 times its FY2027 forecast earnings.
According to its IPO prospectus, SKA Capital intends to maintain a dividend payout ratio of at least 30% of its annual profit attributable to shareholders.
Customer concentration and execution risks
Among the risks the group cited in its prospectus, despite its growth prospects, is its reliance on a relatively small group of customers.
Its top five customers collectively contributed more than 98% to group revenue between FY2023 and FY2025. Transgrid Group alone accounted for 54.1% of FY2025 revenue, while Tenaga contributed another 17.8%.
Any reduction in project awards or delays in securing new contracts from these customers could therefore affect the group’s financial performance.
Its project-based business also exposes it to execution risks, including construction delays, cost overruns and fluctuations in raw material prices. The group continues to rely on subcontractors for certain works, with subcontractor fees accounting for 50.4% of total cost of sales in 5MFY2026.
Working capital management is another area to watch as the group takes on more projects. Its trade receivables turnover period lengthened to 98 days in 5MFY2026, from 53 days in FY2025, reflecting the working capital requirements of its expanding project activities.
The group also depends on foreign labour, with 72 foreign workers out of its total 148 employees as at Sept 21, 2026. This exposes it to potential labour shortages and changes in foreign worker policies.
TA Securities is the principal adviser, sponsor, underwriter and placement agent of the IPO.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.