

KUALA LUMPUR (Nov 11): The recent sell-off in YTL Power International Bhd (KL:YTLPOWR) appears excessive as its colocation data centre business continues to support the group's valuation, said CGS International.
CGS kept its ‘add’ rating and RM6.50 target price on YTL Power, staying bullish despite pressure from Nvidia-related concerns and tighter scrutiny of artificial intelligence (AI) chip supply chains.
The research house cited improving near-term earnings and longer-term growth prospects that it believes are not fully reflected in the share price.
“We believe it is important to distinguish YTL Power’s contracted colocation business from its broader AI data centre ambitions.
“Our RM6.50 target price does not attribute any material value to a successful ramp-up of the AI data centre business, with our data centre valuation primarily based on 850MW of assumed colocation capacity.
“As such, any hiccups in scaling up the AI data centre business would have limited direct impact on our current earnings forecasts and valuation,” it said in a note on Wednesday.
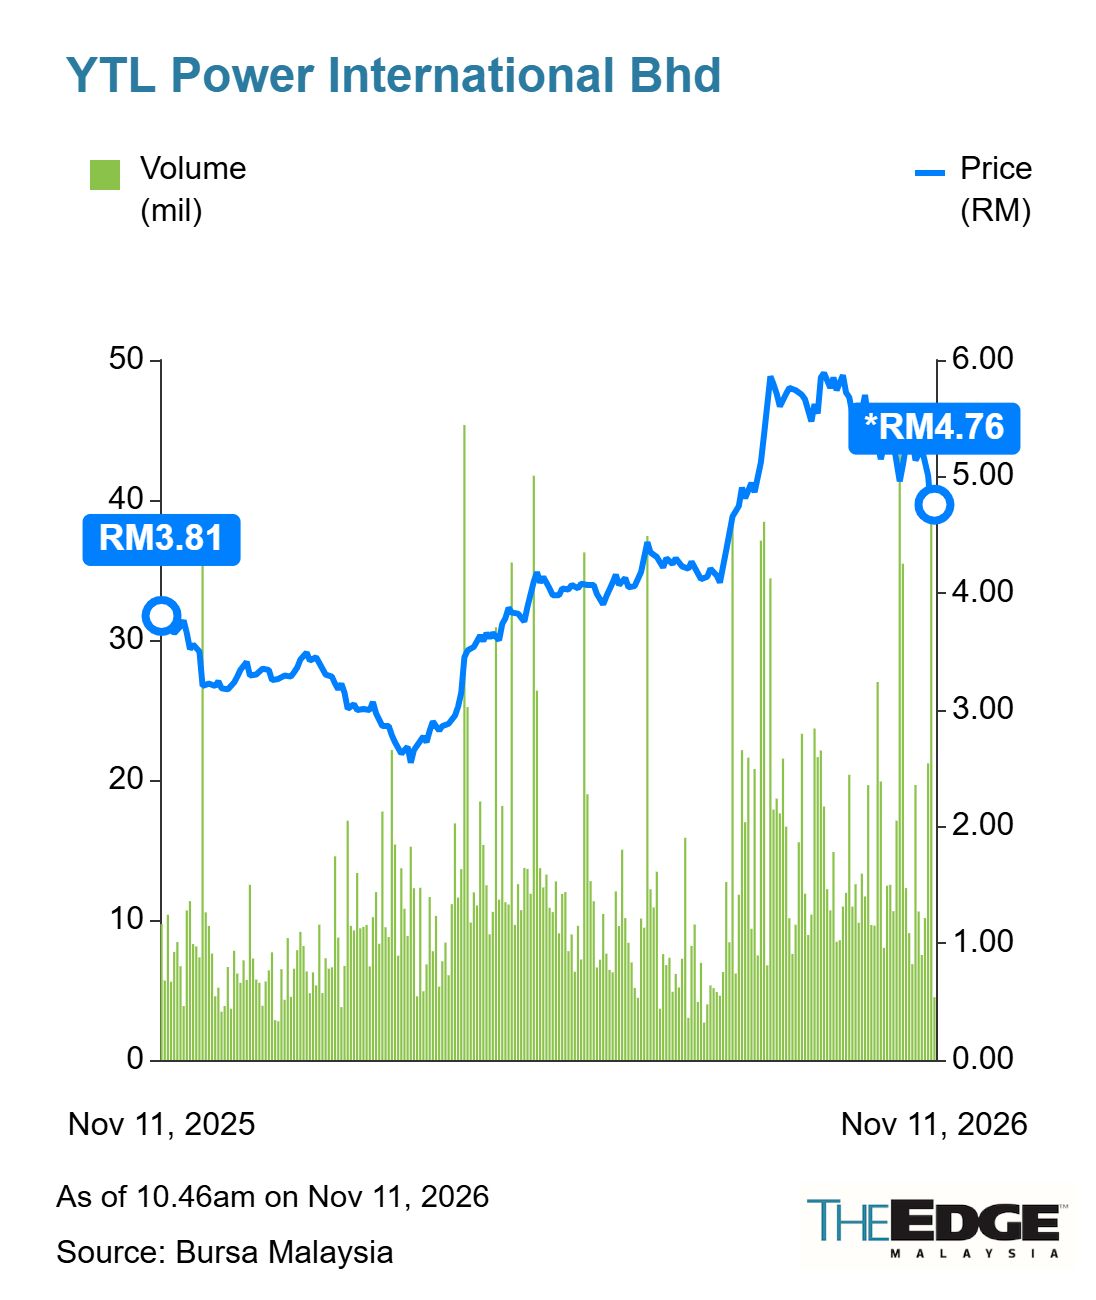
YTL Power shares fell 11% to close at RM4.69 on Tuesday amid renewed scrutiny of its data centre partner Nvidia over espionage allegations.
The counter has declined 21% since end-September, weighed down by broader global data centre concerns, heightened US regulatory uncertainty following the midterm elections and Indonesian gas curtailments affecting its Singapore-based power generation unit, PowerSeraya.
At the time of writing on Wednesday, the counter had gained six sen or 1.28% to RM4.75, with 1.92 million shares traded, giving the group a market capitalisation of RM41.74 billion.
CGS said the recent decline in data centre valuations has mainly affected neocloud and hybrid operators, whose enterprise value to earnings before interest, taxes, depreciation, and amortization multiples have fallen by about 37% since end-September 2026.
In comparison, listed colocation data centre operators have been more resilient, with the broader peer group declining by only 5%, while those outside Hong Kong and China have remained broadly unchanged.
This is relevant to YTL Power, as its data centre valuation is primarily supported by its colocation business, which has 298MW of existing contracted capacity, rather than the more volatile AI and neocloud segments, it said.
Earnings recovery and data centre expansion offer further upside
Meanwhile, CGS expects stronger Singapore spark spreads to contribute about RM35 million to YTL Power's quarterly earnings, largely offsetting the estimated RM38 million impact of Indonesian gas curtailments on PowerSeraya in the second quarter of the financial year ending June 30, 2027 (2QFY2027).
“We have updated our earnings model to reflect YTL Power’s recently released FY2026 annual report and other developments, as well as the recent improvement in Singapore spark spreads and higher PowerSeraya volume assumptions following the completion of maintenance shutdowns in 1H2026. This results in a 6.5% increase in our net profit forecast for FY2027F,” it said.
Beyond the near-term earnings recovery, CGS sees further growth potential from the progressive commissioning of secured data centre capacity, additional capacity wins and the deployment of YTL Power's reserved gas turbines to meet rising electricity demand in Malaysia and the wider region.
The research house also said tighter US regulatory scrutiny and power constraints could encourage some data centre workloads to shift to other markets.
"As highlighted in a report last week by our partner Raymond James, the evolving US policy environment is likely to place greater emphasis on power availability, project approvals and infrastructure readiness, rather than necessarily curtailing AI capex outright.
"This could support spillover demand for non-latency-sensitive workloads towards locations with ready land, infra and faster time-to-market — these dynamics play into YTL Power's strengths, in our view,” it added.