

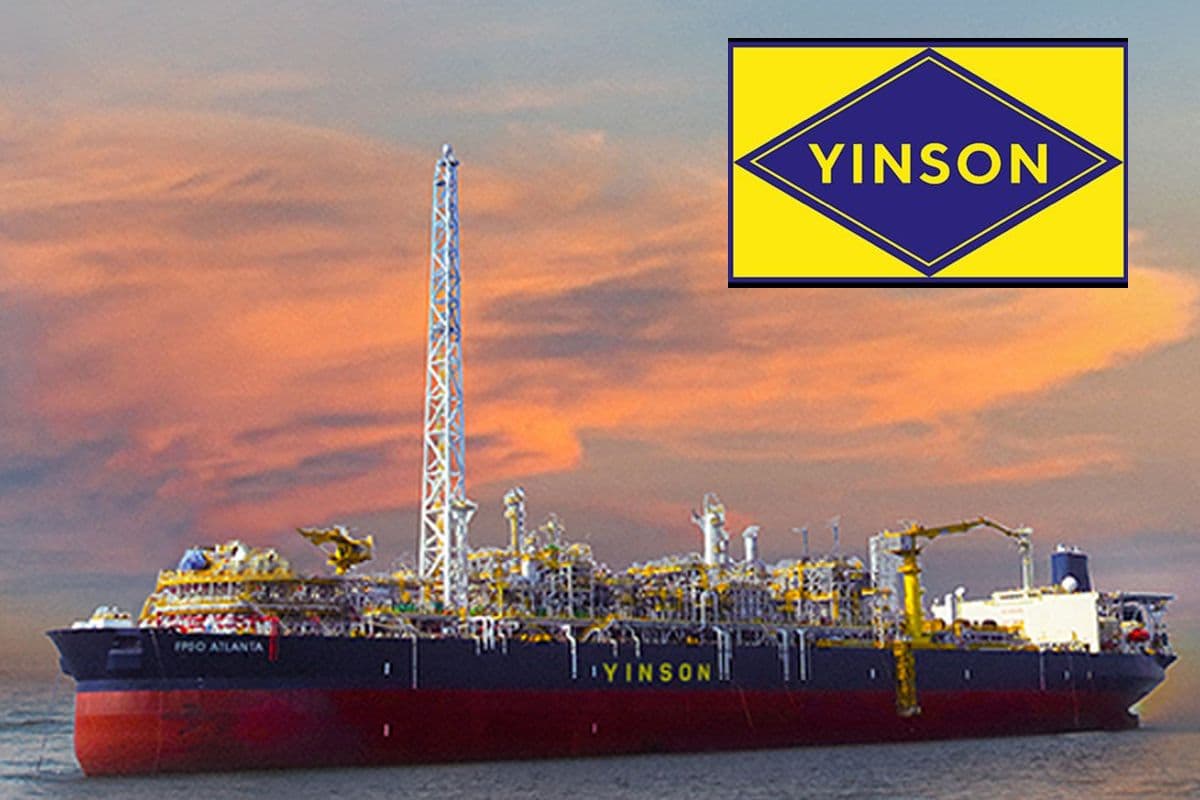
KUALA LUMPUR (Nov 10): The proposed RM2.50-a-share privatisation of Yinson Holdings Bhd (KL:YINSON) offers minority shareholders an exit opportunity above CIMB Securities’ valuation, as heavy gearing and costly financing could constrain growth and dilute returns from new projects, the research house said.
CIMB put Yinson’s net gearing at 2.3 times as at July 2026, excluding RM4 billion in redeemable convertible preference shares (RCPS) and RM1.9 billion in perpetual securities from its calculation.
It said the heavily geared balance sheet could constrain the group’s ability to pursue future growth opportunities.
“Reliance on costly financing instruments, such as RCPS, could also dilute the earnings upside attributable to ordinary shareholders from new projects,” CIMB Securities said in a note on Tuesday.
“Meanwhile, further delays in securing new contracts and deploying the RM4 billion in RCPS proceeds could prolong negative carry and weigh on earnings.”
The research house is of the view that new floating production, storage and offloading (FPSO) contracts could support future earnings for Yinson, although their contribution to cash flow would take time to materialise.
On its estimates, the offer values Yinson at 13.3 times earnings for the financial year ending January 2028, broadly in line with its five-year historical average of 13 times.
On Friday, MISC Bhd (KL:MISC), Yinson’s founding Lim family and the Employees Provident Fund (EPF) proposed to take Yinson private at RM2.50 a share. Buying the remaining 55.2% stake would cost RM4.03 billion, of which MISC would contribute RM3.03 billion.
Upon completion, MISC and Yinson Legacy Sdn Bhd would each hold about 41.5% of acquisition vehicle MY Offshore Holdings Sdn Bhd, while EPF would hold the remaining 17.1%. Yinson would become wholly owned by the vehicle and be delisted.
Completion is targeted for the second half of 2027, subject to shareholder, court and regulatory approvals. CIMB identified failure to secure the necessary approvals as the principal downside risk to its revised target price.
The consortium has asked Yinson’s board to decide by Dec 4 whether to recommend and put the scheme to shareholders.
For now, CIMB maintained its “hold” recommendation but raised its target price to RM2.50 (previously RM2.26) to match the cash offer.
The adjusted target directly matches the conditional cash offer of RM2.50, which commands a 10.6% premium over the research house's standalone valuation before the announcement.
“We view the offer as fair and reasonable, providing minority shareholders with an opportunity to realise value above our fair value for Yinson,” CIMB said, and advised shareholders to vote in favour of the scheme when it is tabled.
Most analysts tracking Yinson remain bullish, with five of the six assigning “buy” recommendations and CIMB maintaining the sole “hold” call, according to Bloomberg data. The consensus 12-month target price stood at RM2.88. Yinson shares slipped five sen or 2.11% as at 11.10am on Tuesday, valuing the group at RM7.11 billion.