

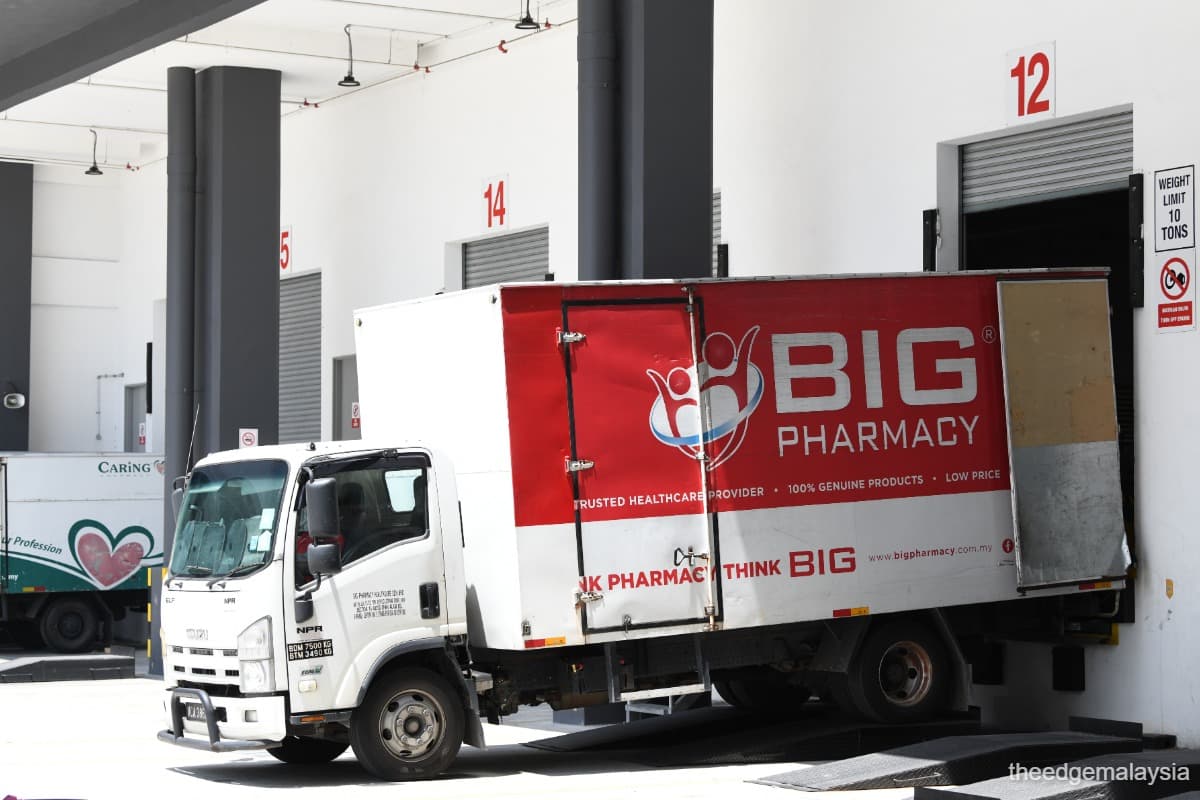
KUALA LUMPUR (Nov 5): MBSB Research has valued Main Market-bound Big Caring Group Bhd at RM1.20 a share, an 11.1% premium to its initial public offering (IPO) retail price of RM1.08, as it expects the pharmacy chain to deliver stronger earnings growth than its retail peers.
In a non-rated IPO note, the research house said Big Caring should trade at a higher valuation than other Malaysian consumer retailers, given its dominant position in the local pharmacy market and a business model that extends beyond running retail outlets.
Its fair value is based on 24 times the pharmacy chain operator's projected earnings for the financial year ending June 30, 2028 (FY2028), compared with the average of 21 times for Malaysian consumer retail stocks.
The valuation is still below that of convenience store chain 99 Speed Mart Retail Holdings Bhd (KL:99SMART), which trades at 29.5 times its forecast 2028 earnings, according to the research house.
“BCG (Big Caring) is the first listed way to own the shift of medicine and health spending into organised pharmacy chains, and it holds a quarter of that market. We think this scarcity supports a premium to general retail,” said MBSB Research.
It also sees Big Caring having an edge over conventional retailers, as prescription medicines are less exposed to competition from Chinese e-commerce platforms.
While Big Caring competes with health and beauty retailers such as Watsons and Guardian in supplements, over-the-counter healthcare products and beauty items, MBSB Research sees its prescription medicine business as a key advantage.
Unlike general healthcare and beauty products, scheduled medicines must be supplied through licensed pharmacies under Malaysian law, with a pharmacist dispensing or supervising their sale. This provides some protection against price competition from online marketplaces, including Chinese e-commerce platforms.
Pharmaceutical products accounted for 39% of Big Caring's retail revenue in FY2026, while its MyHA digital healthcare platform keeps repeat orders from customers requiring prescriptions.
The research house expects the group's earnings per share to grow about three times faster than those of its retail peers.
At its IPO retail price of RM1.08, Big Caring is valued at 21.6 times its projected FY2028 earnings, only slightly above the broader retail peer average despite its stronger growth prospects.
MBSB Research said Big Caring is Malaysia's largest pharmacy chain, with 668 outlets operating under brands including BIG, CARiNG, Georgetown, Ting, Wellings and iCare. Of these, 660 are licensed pharmacies, more than double the number operated by the nearest competitor. The group commanded 24.2% of Malaysia's retail pharmacy sales in 2025, according to the note.
MBSB Research expects Big Caring's core net profit to jump 37.3% to RM293.6 million in FY2027, from RM213.8 million in FY2026, before climbing further to RM368.7 million in FY2028 and RM433.9 million in FY2029.
Much of that growth is expected to come from opening more pharmacies and getting existing outlets to generate higher sales.
The group plans to add 40 to 50 outlets annually over the next three to five years, with room to expand particularly along the East Coast and in East Malaysia, where its presence remains relatively limited.
New stores have also been relatively quick to turn profitable, typically breaking even at the operating level within a year and recovering the initial investment within two to three years, said MBSB Research.
Big Caring is expected to have a market capitalisation of RM8 billion upon listing and is raising up to RM2.03 billion for its expansion plans. It will go live on Bursa Malaysia’s Main Market on Nov 19.