

This article first appeared in The Edge Malaysia Weekly on November 2, 2026 - November 8, 2026
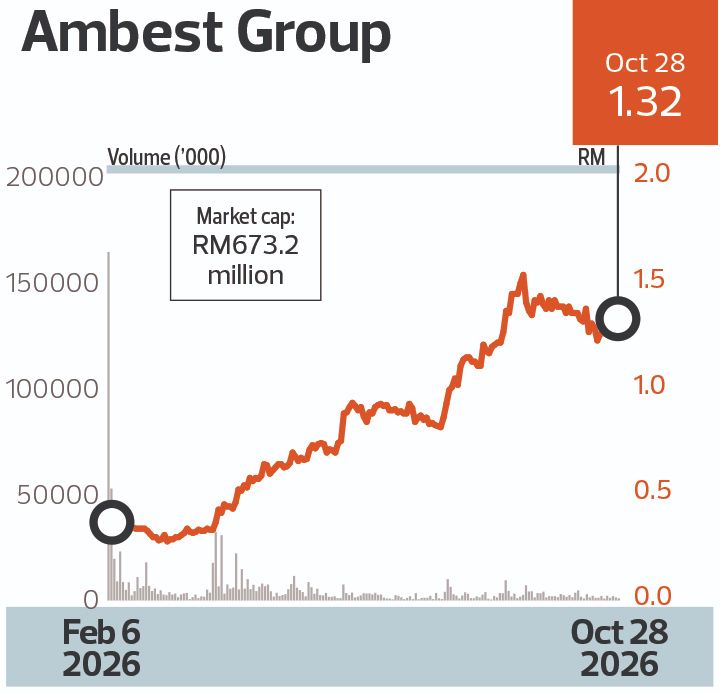
AMBEST Group Bhd’s (KL:AMBEST) share price has rallied more than fivefold since its February debut, making it one of the market’s top performers this year. Listed on the ACE Market at an initial public offering price of 25 sen, the stock reached RM1.32 last Wednesday.
What is driving investors’ enthusiasm for the semiconductor components maker? Ambest specialises in precision metal fabrication, using computer-controlled milling and turning to manufacture high-tech parts.
Managing director Tan Beng Beng tells The Edge in an interview that Ambest is directly involved in the front-end segment of the semiconductor supply chain, particularly through its work with a European-based global leader in high-precision vacuum transfer valves used in semiconductor manufacturing equipment.
“These transfer valves facilitate the movement of wafers between different sections of semiconductor manufacturing equipment and must meet stringent reliability requirements,” Tan says. “Such components offer a different proposition from conventional machined parts as customers must be confident that they can withstand repeated operating cycles without failure.”
Qualifying to supply these critical components can take years of rigorous testing. One key requirement is cycle testing, which can involve up to two million operating cycles to demonstrate that a component can withstand repeated use without compromising performance.
Tan recalls that one such qualification process took so long that there were times when the company felt as though it was simply going nowhere. That waiting period tested its resolve. After submitting products for evaluation, Ambest spent nearly four years stuck at the first-article testing stage before finally receiving approval. “It was quite a moment when the customer informed us that we had qualified,” he says.
The machining process demands precision down to the micron level — at fractions far thinner than a human hair. Given the stringent requirements, customers rarely switch suppliers once qualified, giving Ambest the opportunity to deepen its customer relationship and secure a more entrenched position in its supply chains.
To meet surging demand, Ambest has committed to investing in 24 new machines to support one of its customers. These include advanced five-axis machines from top-tier Japanese-German manufacturer DMG MORI, which will enable the group to produce more complex components and broaden its manufacturing capabilities. “We are looking at capital expenditure of RM30 million to RM40 million and the machines are already on the way,” Tan says.
Ambest has also signed a partnership letter with a key European customer, giving the group clearer visibility of future demand so it can align its machinery investments accordingly. While the non-binding agreement does not guarantee firm orders, it provides a framework for closer collaboration between the parties.
The group has also qualified to supply critical components directly to a wafer fabrication equipment (WFE) manufacturer, marking another step towards the front end of the semiconductor supply chain. Tan says the group is among the few Malaysian suppliers to have qualified for such work this year.
Orders extend into next year
Ambest’s order visibility already extends into next year as customers are placing orders earlier than usual. “Customers want to secure their inventory and are placing actual orders rather than giving rolling forecasts,” Tan says.
Traditionally, customers placed orders within a four-to-six-week window, in line with Ambest’s standard lead time, but they are now committing much further in advance to secure critical materials.
This demand surge has pushed Ambest’s initial 25,500 sq ft plant to 100% utilisation. In response, the group has commissioned a second 21,600 sq ft facility, alongside an additional mezzanine floor of about 12,000 sq ft to accommodate more production capacity.
However, with the incoming 24 machines set to fill this new space completely, management is already considering building a third plant to support further expansion.
During The Edge’s recent factory tour, the second plant was already taking shape, with some of the new five-axis machines undergoing trial runs.
“We are fortunate to have a good working relationship with DMG MORI and can get the machines earlier than others,” Tan says. The Japanese-German engineering group is often dubbed the “Rolls-Royce” of computer numerical control (CNC) machines for its precision and advanced technology.
Beyond high-precision machining, Ambest has invested in Class 10,000 and Class 100,000 cleanroom facilities to handle critical components that must meet stringent cleanliness requirements before being incorporated into semiconductor manufacturing equipment.
Tan describes the cleanrooms as a strategic advantage as not every precision machining supplier has the facilities to handle such components.
The combination of advanced machinery and cleanroom capabilities is expected to help Ambest secure higher-value orders, although production volumes for these specialised components are likely to remain relatively low for now.
The investments also support the group’s ambition to move beyond precision machining towards becoming a contract manufacturer, offering customers a broader range of integrated manufacturing services.
Should a third plant materialise, given that existing capacity is almost fully taken up, it would likely be from 2028 onwards and may require additional fundraising, though management has yet to finalise its plans.
For now, Tan says the priority is to fulfil existing orders while ensuring future investments remain aligned with customer demand. As at end-September, Ambest’s order book had increased to RM80 million, up from RM42 million in May.
Building resilience against a downturn
Despite the strong demand outlook, Tan remains mindful of the semiconductor industry’s notorious boom-and-bust cycles. A sudden slowdown can quickly translate into lower orders and leave expensive machinery underutilised while depreciation and other operating costs continue to bite.
“Most importantly, we need to manage our cash flow. We will continue to focus on generating sales because that is what sustains the business,” he says.
Ambest has maintained positive free cash flow despite substantial investments in new equipment, allowing it to fund expansion while building a cash buffer against a potential downturn.
As at end-June, Ambest held RM8.35 million in cash against total borrowings of RM22.43 million, translating to a net gearing ratio of 21.4%. The group also retains RM3.78 million from the proceeds of its IPO, which raised RM27.5 million.
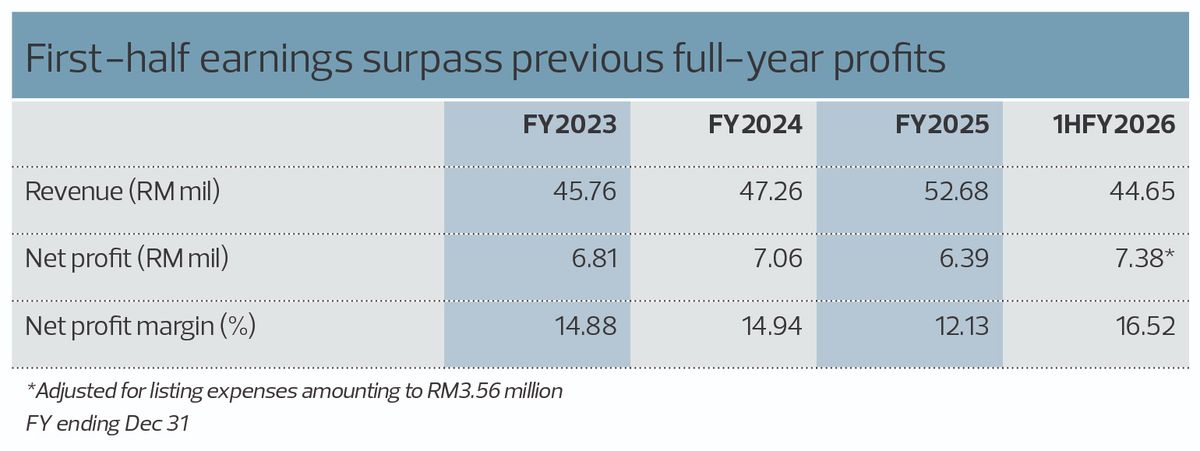
The group, which has a workforce of about 180, recorded revenue of RM52.68 million for the financial year ended Dec 31, 2025 (FY2025), up from RM47.26 million in FY2024 and RM45.76 million in FY2023. Revenue for the first half of FY2026 reached RM44.6 million.
Analysts expect revenue to scale rapidly as new capacity comes online. Tradeview Capital and Kenanga Research expect Ambest’s revenue to more than double to over RM100 million in FY2026, from RM52.7 million in FY2025. For FY2027, Tradeview forecasts revenue growth of about 70% to RM172 million while Kenanga projects a further increase of 80% to RM200 million.
In terms of profitability, Ambest recorded an adjusted net profit of RM7.38 million for the first half of FY2026, after excluding listing expenses. This already surpassed its full-year net profit for each of the preceding three financial years. Its first-half net profit margin expanded to 16.5%, from 12.1% to 14.9% over the previous three years.
For the full FY2026, Kenanga forecasts a net profit of RM12.6 million — nearly double FY2025’s RM6.4 million — before rising to RM36.7 million in FY2027. Tradeview, meanwhile, expects net profit of RM14.5 million for FY2026 and RM31.4 million for FY2027.
The forecasts hinge on Ambest’s ability to convert its order book into revenue, improve its product mix and utilise its new machinery efficiently. Execution risks remain, particularly given the capital commitments involved and the cyclical nature of semiconductor demand.
At its closing price of RM1.32 last Wednesday, Ambest had a market capitalisation of RM673.2 million. Based on the average of both earnings forecasts, the stock was trading at a consensus forward price-earnings ratio (PER) of 49.7 times FY2026 earnings and 19.8 times FY2027 earnings.
Both Tradeview and Kenanga have “buy” recommendations on the stock,with target prices of RM1.60 and RM1.80 respectively, implying potential upsides of about 21% and 36%.
Tan and executive director Lim Eng Guan each hold a 32.21% stake in the group, giving them a combined controlling shareholding of 64.42%.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.