

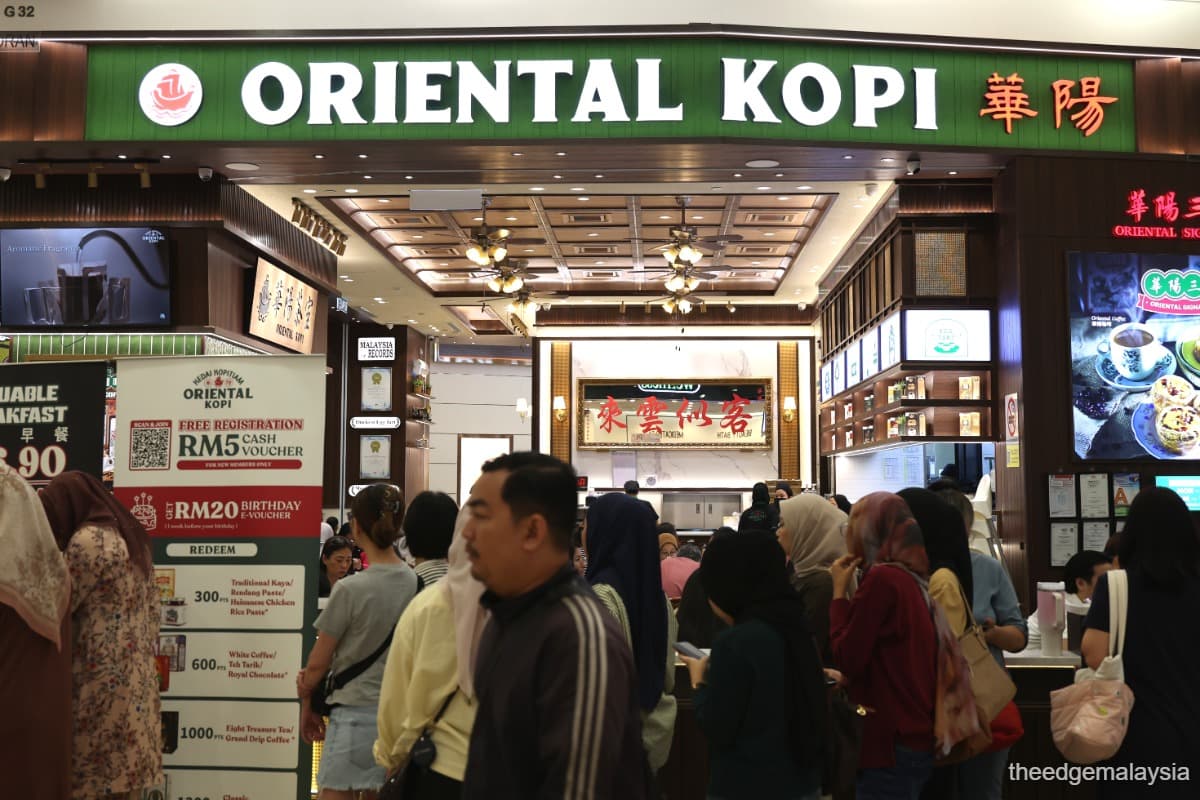
KUALA LUMPUR (Nov 4): Oriental Kopi Holdings Bhd (KL:KOPI) appears unscathed from a public uproar over its menu language, with little impact on revenue and minimal cost, said an analyst.
Trilingual menus were reprinted at a cost of about RM150,000 and will be rolled out to all outlets by the end of this month, CGS International said in a note following an investors briefing with the company. There was no material impact on footfall or the customer mix so far, the house noted.
“The three outlets opened in the past 10 days have drawn long queues,” CGS International wrote as it kept the stock on an ‘add’ call, equivalent to a ‘buy’ rating.
A social media backlash erupted against Oriental Kopi last month over its English- and Chinese-only menus. Datuk Calvin Chan, the restaurant chain’s founder and managing director, has since issued an apology and pledged to correct the matter by reprinting the menu to include Bahasa Malaysia.
Shares of Oriental Kopi, meanwhile, have lost nearly 8% of their value since the start of October, bringing the year-to-date decline to nearly 40% amid disappointing earnings with margins continuing to shrink due to an aggressive expansion.
However, six of eight research houses believe the worst is likely over, recommending investors to buy the stock. The remaining two are on ‘hold’. The average target price is RM1.21, according to Bloomberg, implying potential upside of 46% in the next 12 months from the last price of 83.5 sen.
For CGS International, the outlook for Oriental Kopi remains “constructive” with the company on track with its store expansion plan that would help eke out a net profit of RM67.4 million for the financial year ended Sept 30, 2026.
Oriental Kopi is eyeing up to 10 new outlets each year, and had 34 stores at the end of July. With presence in most high-footfall locations, the company is now moving into second-tier malls, which “should keep rental costs in check”, CGS International said.
Current valuations “do not fully reflect the value of its hybrid business model” that combines discretionary-driven café operations with a scalable fast-moving consumer goods platform, the house said.
At its target price of RM1.37, the stock would trade at about 22 times forward earnings, in between consumer staples and consumer discretionary sector target multiples, the house noted.