

Plantations
OVERWEIGHT
HONG LEONG INVESTMENT BANK (OCT 27): Seasonally stronger cropping trends and sustained downstream performance should drive q-o-q earnings improvement in the upcoming reporting season (commencing Nov 5, 2026). We expect earnings of the planters under our coverage to be largely in line with our projections, supported by broadly higher palm product prices and output.
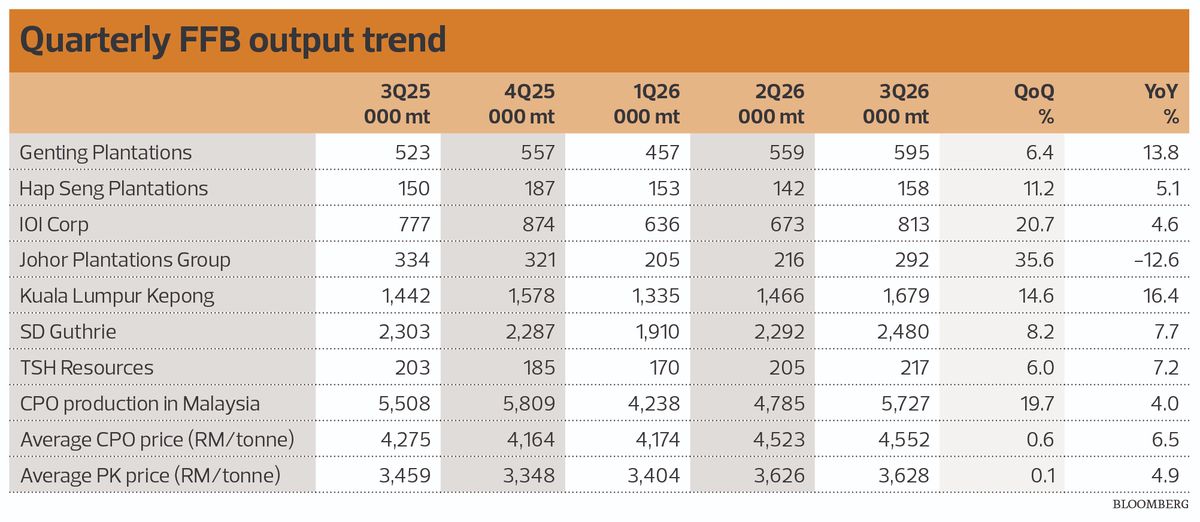
Planters under our coverage are expected to post improved q-o-q upstream performance in 3Q26, supported by a seasonal cropping up cycle and broadly stable palm product prices. During the quarter, fresh fruit bunch (FFB) production among these companies increased by 6% to 35.6% q-o-q.
Notably, Malaysia-focused planters, including Hap Seng Plantations Holdings Bhd (KL:HSPLANT), Johor Plantations Group Bhd (KL:JPG) and IOI Corp Bhd (KL:IOICORP), recorded stronger sequential volume growth than Indonesian peers.
For the downstream segment, several factors should provide near-term relief to profitability. These include a narrower crude palm oil (CPO) export tax differential compared to 2Q26, stable palm kernel prices, and proactive restocking activities amid geopolitical uncertainties and the impending implementation of the EU Deforestation Regulation (EUDR).
Broadly higher FFB output and palm product prices are expected to support upstream earnings growth in 3Q26, partly offset by higher fertiliser costs. JPG is the exception, as its FFB output was weighed down by an accelerated replanting programme.
In the downstream segment, refining profitability is expected to remain under pressure from a wider y-o-y CPO export tax differential and persistent industry overcapacity.
However, this may be partly mitigated by active restocking in the oleochemical segment, driven by geopolitical uncertainties and the impending implementation of the EUDR.
We maintain our 2026/27 average CPO price assumptions of RM4,450 and RM4,500 per tonne, supported by the anticipated tightening in the palm oil supply-demand balance as higher Indonesian biodiesel demand coincides with El Niño-related production losses.
We reiterate our “overweight” stance on the sector, underpinned by our expectation that elevated CPO prices will be sustained into 2027, supported by tightening supply conditions and resilient demand. We continue to favour planters with greater exposure to Malaysia. For exposure, our top picks are Hap Seng Plantations (“buy”; target price: RM2.81) and IOI Corp (“buy”; TP: RM5.16).
Maxis Bhd
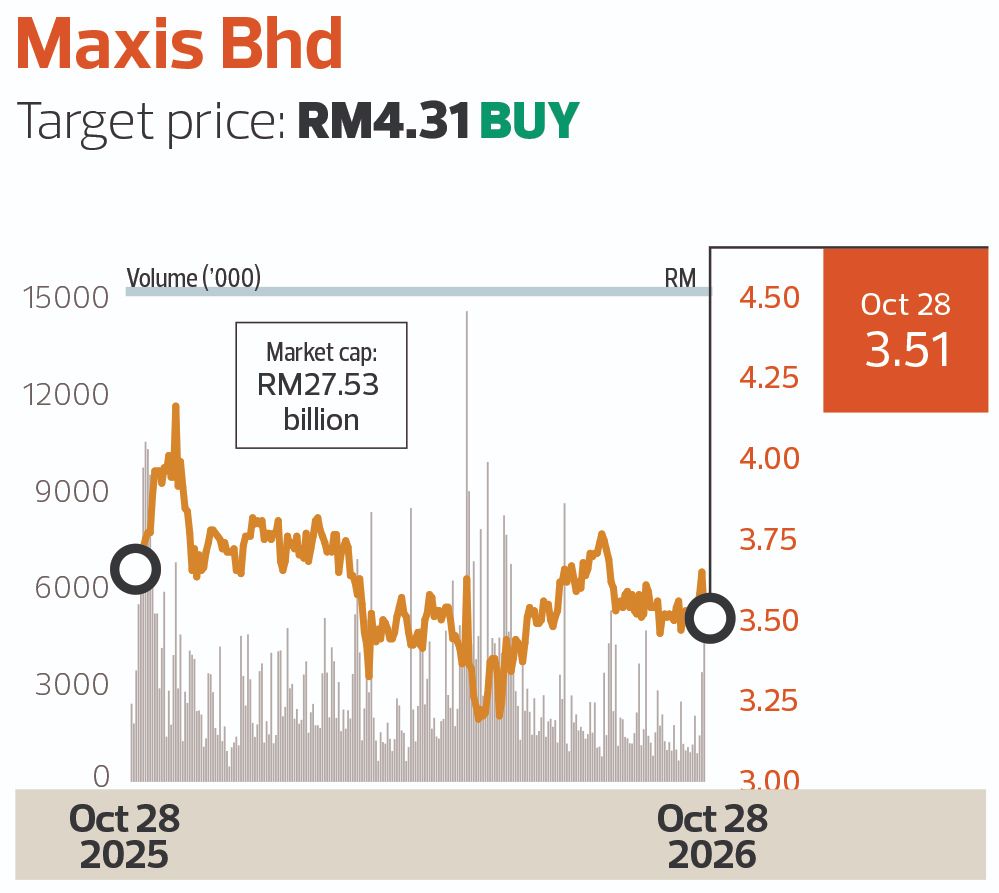
Target price: RM4.31 BUY
MBSB RESEARCH (OCT 26): We maintain our “buy” recommendation with an unchanged target price of RM4.31.
Maxis Bhd (KL:MAXIS) entered into a sale and purchase agreement with MEASAT Broadcast Network Systems Sdn Bhd (MBNS), wholly owned by Astro Malaysia Holdings Bhd (KL:ASTRO), to acquire MBNS’ broadband business assets for up to RM83 million in cash, for MBNS’ entire broadband subscriber base of 178,631 active subscribers as at end-February 2026, and associated contracts, software, equipment and inventories.
The acquisition will be funded through internally generated funds. Note that as at 2QFY26, the cash reserve stands at RM804 million.
Premised on the 178,600 subscribers, Maxis’ home connections could potentially increase by +22% to 991,600 subscribers. Moreover, we view that the average revenue per user could be similar to Maxis’ current home-blended ARPU of RM109.10 per month.
Based on Maxis’ average monthly consumer home revenue of RM84 million as at 2QFY26, we view that the inorganic growth would potentially grow the top line by slightly over 20%.
The main risk factors include delay or non-completion of the proposed transaction; subscriber retention and churn risks; and integration risks.
Coastal Contracts Bhd
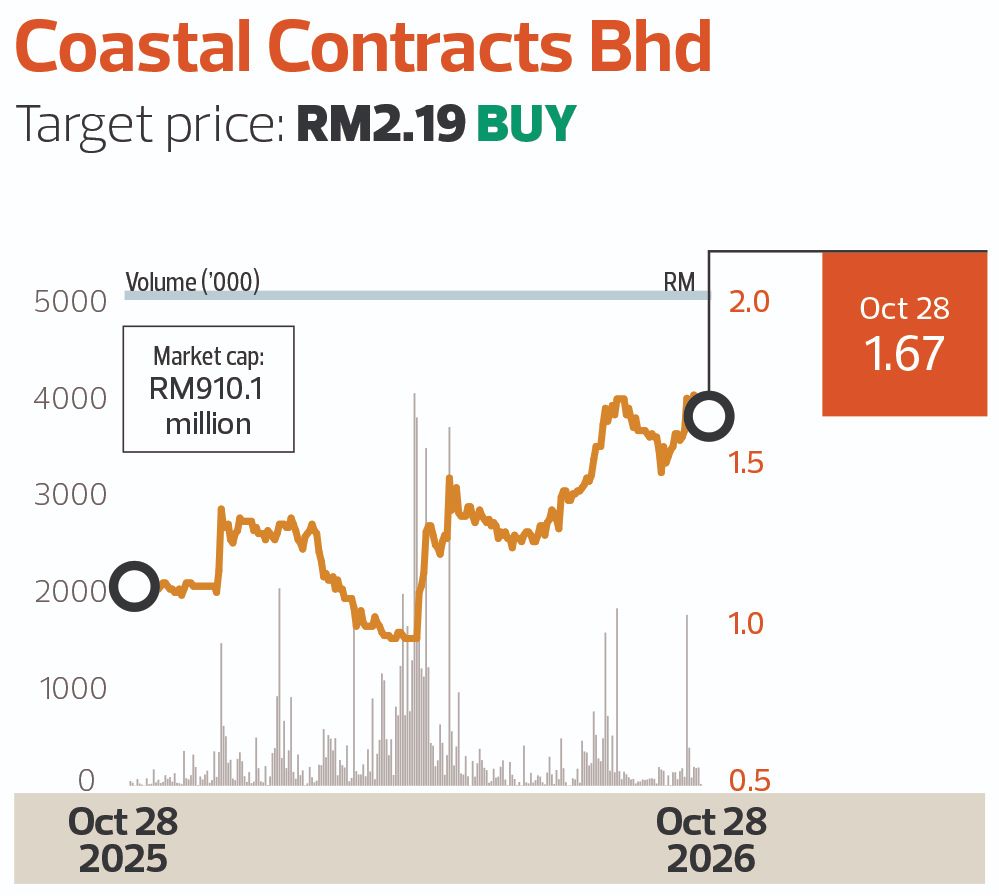
Target price: RM2.19 BUY
TA SECURITIES (OCT 26): Coastal Contracts Bhd’s (KL:COASTAL) plant commenced operations on May 20, 2026, and recorded an average processing volume of 181 million standard cu ft per day, or near-maximum capacity of 200mmscfd, during 2QFY26. The project generated US$250 million (RM1.01 billion) of engineering, procurement and construction (EPC) revenue, comprising US$157.5 million for the plant and US$92.5 million for permanent primary infrastructure (PI).
The EPC project achieved a net profit margin of above 30%, although management clarified that the earnings at this level are not sustainable.
Importantly, the second Perdiz plant should provide a recurring earnings stream through its three-year operations and maintenance contract until May 2029.
The second Papan plant remains on track, with overall construction progress reaching 40% as at 2QFY26, and commercial operations are targeted for 1QFY27 for the 150mmscfd facility.
Separately, the group’s US$170 million EPC contract for the second Papan PI works commenced in 2Q26 and is targeted for completion in 1QFY27.
At group level, Coastal’s vessel construction programme provides strong earnings visibility from 2H26 onwards, with at least three vessels scheduled for delivery in 3Q-4QFY26.
We maintain our target price of RM2.19 per share based on SOP valuation.
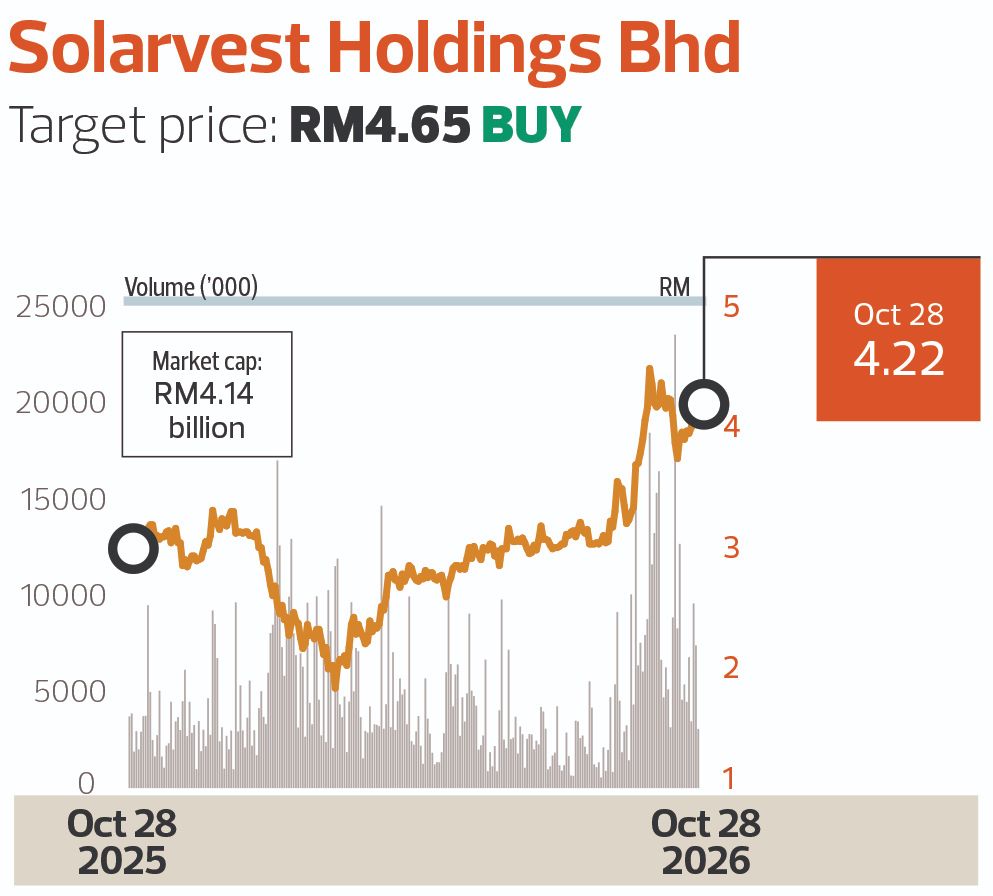
Solarvest Holdings Bhd
Target price: RM4.65 BUY
CIMB SECURITIES (OCT 25): We view Solarvest Holdings Bhd (KL:SLVEST) as a key beneficiary of Malaysia’s renewable energy push, backed by its proven solar photovoltaic (PV) engineering, procurement, construction and commissioning (EPCC) execution track record.
We forecast core net profit to grow at a three-year CAGR of 37.7% over FY26-FY29F, underpinned by its sizeable order book, potential new wins from the sixth phase of Malaysia’s Large Scale Solar programme (LSS6) and corporate renewable energy supply scheme (CRESS), and rising recurring income from solar generation.
Our SOP-based target price (TP) of RM4.65 comprises RM4.10 for its EPCC business, 30 sen for solar assets, and 25 sen for associates.
Solarvest’s sizeable RM2.4 billion unbilled order book provides strong earnings visibility through FY27-FY28F.
We see significant potential for further EPCC wins from LSS6, with tenders closing by end-CY26. Based on the 2.65GW of solar PV capacity on offer, we estimate RM10 billion worth of EPCC contracts are up for grabs. Assuming a 15% market share, we forecast Solarvest to secure RM1.8 billion in new contracts.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.