

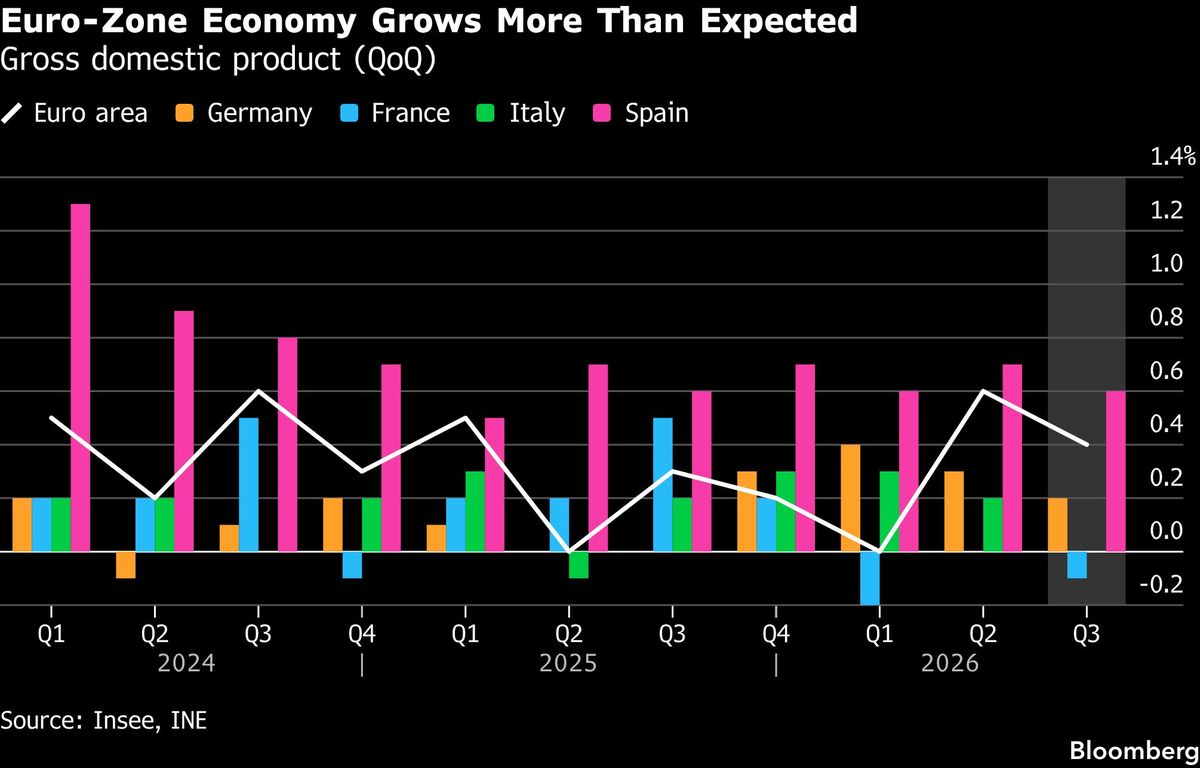
(Oct 30): The euro-area economy grew at twice the pace analysts predicted, despite an unexpected slump in France and headwinds including elevated inflation and the selloff in bond markets.
Gross domestic product across the 21-member currency bloc rose 0.4% in the third quarter (3Q), Eurostat said on Friday. Performances were mixed among its biggest members as Germany and Spain grew, Italy stagnated and France shrank by 0.1%.
The overall outcome highlights Europe’s broader sturdiness, not just to the Iran war’s inflationary impact but to the heat waves and droughts that marred much of the summer. Still, the European Central Bank (ECB) has flagged downside risks and could yet hike interest rates for a third time in December after standing pat this week.
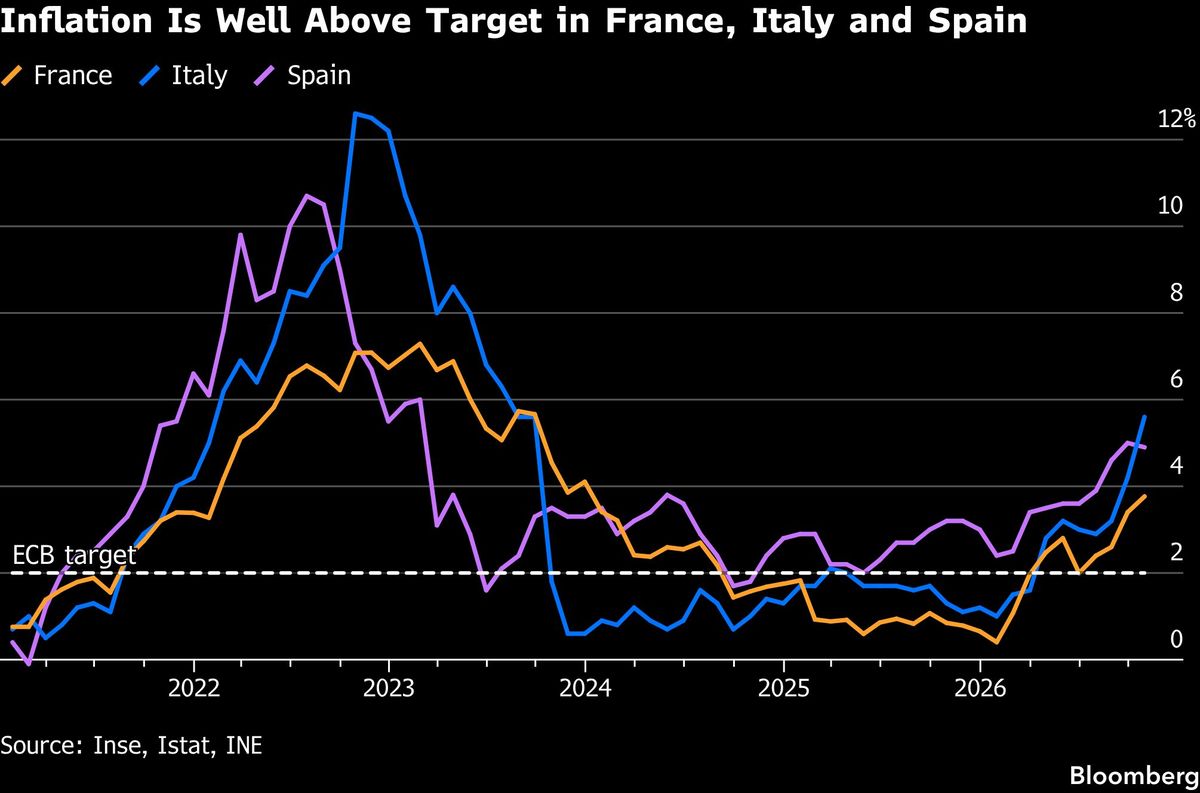
While inflation hasn’t spread beyond energy yet, officials in Frankfurt are wary. Separate data from Italy and France won’t reassure them, with prices jumping by 5.6% and 3.8% in October, the quickest since 2023 and ahead of expectations.
Inflation in Spain, despite easing a touch as anticipated, remained elevated at 4.9%.
The jump in global bond yields is another drag, with France’s shaky fiscal and political position making it the region’s focal point. Its economy was already the euro area’s major laggard, only narrowly avoiding a recession in the first half amid soft domestic demand, falling investment and as hot weather hurt agriculture.
The outlook is bleak. Prime Minister Sebastien Lecornu is in the midst of another parliamentary showdown over austerity, against a backdrop of social and political upheaval before presidential elections in 2027 where the far right leads polls.
“France’s economy is at a standstill due to a unprecedented convergence of external and domestic shocks,” Finance Minister Roland Lescure said on Friday. “It needs to pick up. We need to restore confidence and for that having a budget is essential as that is what will allow us to bring down interest rates.”
German GDP rose 0.2% despite factors including low water levels in the River Rhine. A public-spending spree on infrastructure and defense is generating optimism while carmakers may benefit from a European cap on Chinese hybrid-vehicle imports.
At the same time, Chancellor Friedrich Merz has made fresh efforts to perk up growth through social-welfare reforms and attempts to lure private capital.
“The headline overstates the strength of the economy. National data suggest Ireland accounted for about half of the increase, while the four largest economies grew by just 0.1% on average. With the conflict in Iran unresolved and energy prices still high, we think the bigger drag is yet to come. For now, though, the stronger GDP data reinforce our view that the ECB remains on track for another 25bp rate hike in December,” says Simona Delle Chiaie, chief euro-area economist at Bloomberg Economics.
Italy’s government forecasts GDP will increase 1% in 2026, helping finance some of the tax cuts Prime Minister Giorgia Meloni has promised before elections next year.
She’s also asked Brussels for extra leeway of about €28 billion (RM126.77 billion) for energy and defense outlays. Any slowdown in growth would complicate other fiscal commitments, including getting the budget deficit below 3% of output.
Spain, whose latest GDP reading was driven by domestic demand and trade, has shown significant resilience, with the central bank listing private consumption, job creation and population growth among drivers.
It sees growth of 2.6% in 2026 and 2.2% in 2027, comfortably above the euro area’s pace. It’s largely shaken off political instability including Prime Minister Pedro Sanchez inability to pass a budget.
Uploaded by Felyx Teoh