

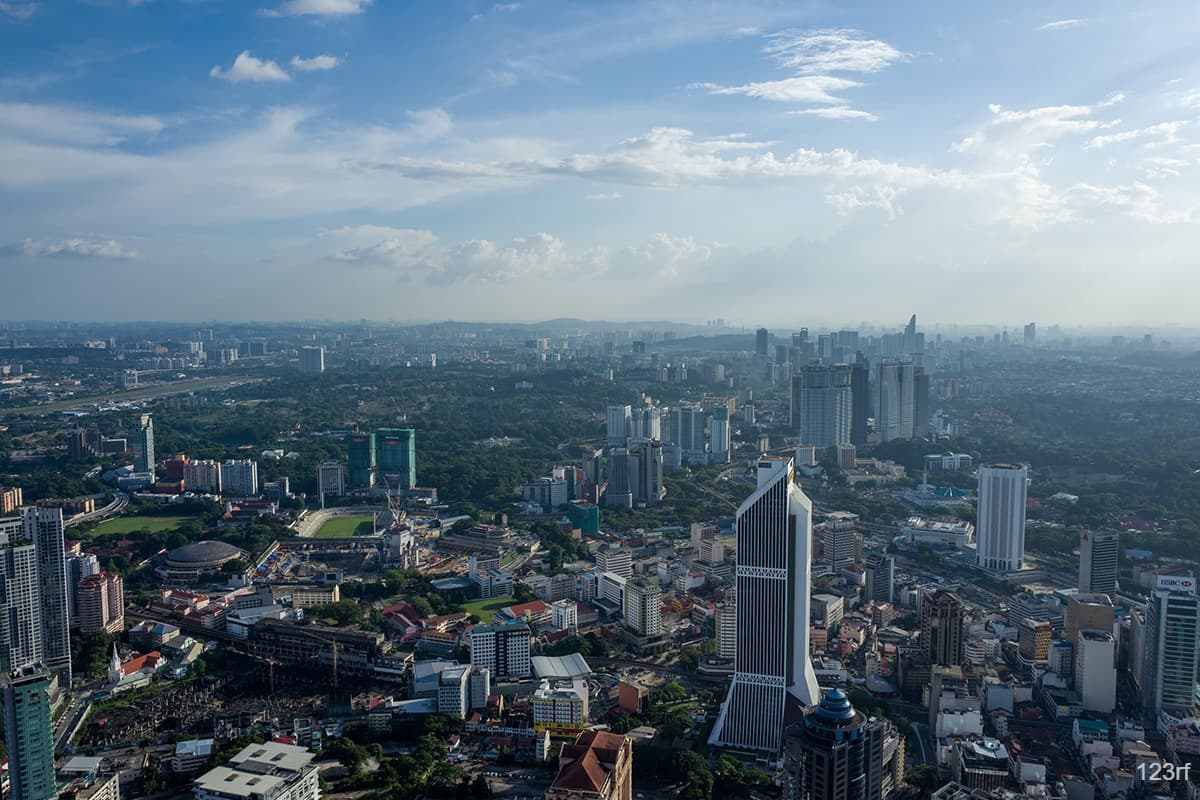
This article first appeared in City & Country, The Edge Malaysia Weekly on October 26, 2026 - November 1, 2026
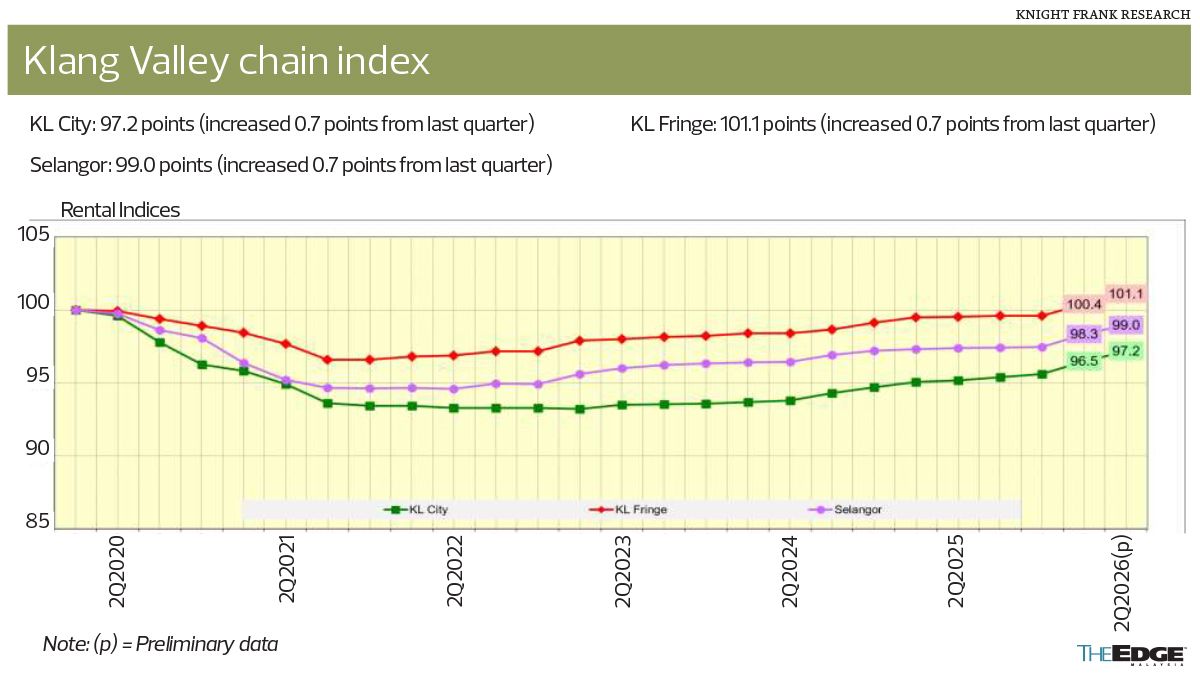
The Klang Valley office market saw leasing momentum continue to build in 2Q2026, supporting higher occupancy and rents across all key office localities, according to Knight Frank Malaysia executive director of research and consultancy Amy Wong in presenting The Edge Malaysia | Knight Frank Kuala Lumpur and Selangor Office Monitor 2Q2026.
“With 1H2026 net absorption already exceeding half of 2025’s full-year total, market conditions are showing a more sustained improvement in comparison to previous quarters,” she says.
Knight Frank Malaysia’s data shows that the net absorption in the Kuala Lumpur office market recorded a notable increase to slightly over one million sq ft in 2Q2026, supported by major corporate relocations and continued take-up in newer Grade A office developments, particularly in the new central business district (CBD).
Wong says Malayan Banking Bhd’s (KL:MAYBANK) relocation of its headquarters to Menara Merdeka Maybank was a key contributor to the uplift in tracked occupied space during the quarter.
The Selangor office market recorded stronger net absorption of about 240,000 sq ft, supported by continued leasing activity at the recently completed Sunway Square Corporate Towers.
The total estimated office supply across KL City, KL Fringe and Selangor currently stands at 120.62 million sq ft, comprising 60.63 million sq ft in KL City, 32.18 million sq ft in KL Fringe and 27.81 million sq ft in Selangor.
“The absence of new completions kept office stock unchanged at 120.62 million sq ft, providing additional time for existing vacancies to be absorbed,” says Wong.
Meanwhile, some 3.17 million sq ft of office space is under construction and expected to be completed between the second half of 2026 and 2027. Of this, KL City accounts for 390,000 sq ft, with 120,000 sq ft expected to be completed in 2026 and 270,000 sq ft in 2027.
KL Fringe accounts for 1.58 million sq ft, comprising 1.37 million sq ft expected to be completed in 2026 and 210,000 sq ft in 2027. In Selangor, 1.2 million sq ft of office space is under construction, with completion expected in 2026.
“About 3.17 million sq ft of new office space is scheduled until 2027, representing a manageable 2.6% of existing stock,” she adds.
Occupancy improvement in some localities
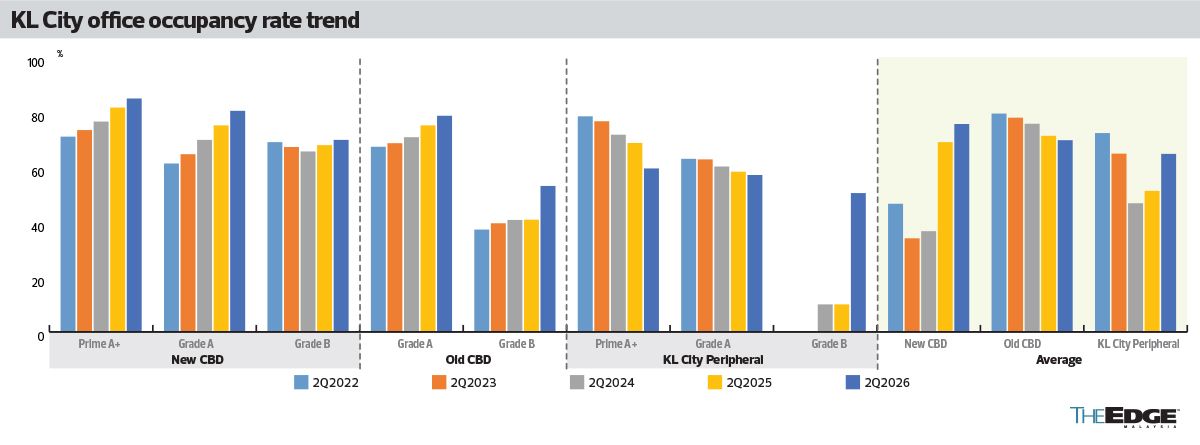
Knight Frank Malaysia senior executive director of office strategy and solutions Teh Young Khean says market fundamentals strengthened in 2Q2026 compared with 1Q2026. In terms of average occupancy rates in KL City, it increased in 2Q2026 from 1Q2026 across all localities.
Kuala Lumpur’s new CBD recorded an increase to 78.8%, from 78.2%, while the old CBD’s average occupancy rate improved to 57.2% from 54.1%. The KL city centre peripheral recorded the most significant improvement, rising to 64.9% from 51.2%. Overall, the average occupancy rate for KL City increased to 73.9% in 2Q2026 from 71% in 1Q2026.
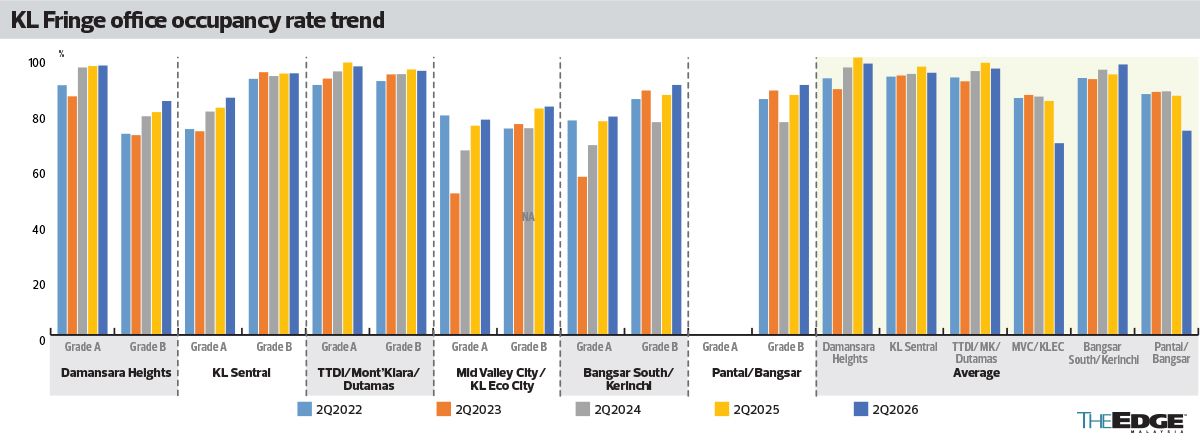
The average occupancy rate in KL Fringe showed mixed movements across localities in 2Q2026 from 1Q2026. Damansara Heights recorded an increase to 85.5% from 85%. In contrast, KL Sentral’s occupancy rate declined to 95.2% from 95.6%, while Taman Tun Dr Ismail/Mont’Kiara/Dutamas recorded a slight decline to 78.7% from 78.8%.
Mid Valley City/KL Eco City experienced an improvement to 90.1%, from 88.7%, whereas Bangsar South/Kerinchi saw its occupancy rate decrease to 96% from 97.3%. Pantai/Bangsar recorded an increase to 73.6% from 73.3%. Overall, the average occupancy rate in KL Fringe edged up to 88.7% in 2Q2026 from 88.6% in 1Q2026.
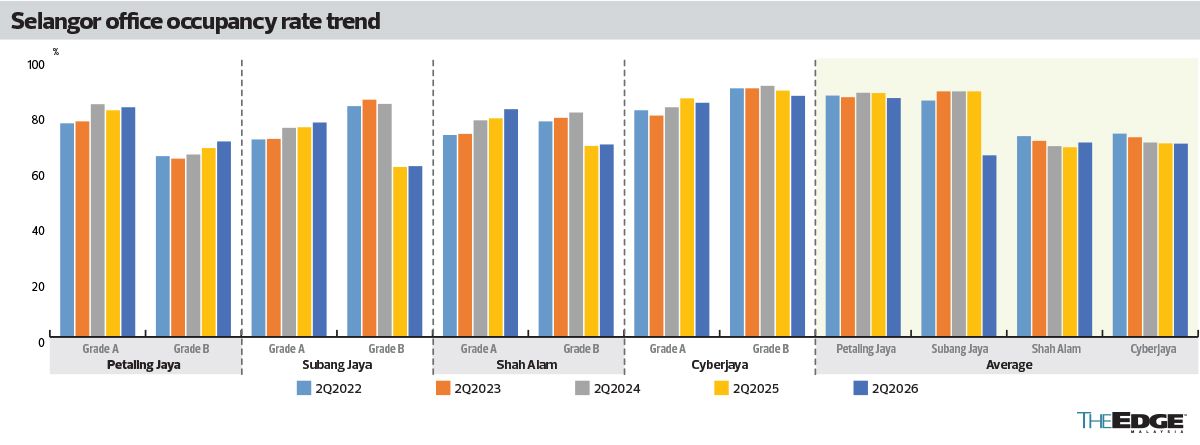
In Selangor, the average occupancy rate saw an overall improvement in 2Q2026 from 1Q2026, with most localities recording increases. Petaling Jaya’s occupancy rate rose to 77.1% from 76.6%. Subang Jaya recorded a notable improvement to 69.2%, from 63.9%. In contrast, Shah Alam’s occupancy rate declined to 85.9% from 86.6%. Cyberjaya recorded a slight increase to 69.5%, from 69.1%. Overall, Selangor’s average occupancy rate increased to 74.5% in 2Q2026 from 73.2% in 1Q2026.
“The improvement is expected to extend modestly into the second half, although occupiers are likely to remain measured in their space decisions amid an increasingly complex business operating environment with active enquiries still observed in the market,” says Teh.
He adds that occupiers such as financial institutions, technology firms and business services are expected to actively take up space. “Continued expansion by flexible workspace operators should also broaden occupier choice, particularly for businesses managing variable headcount, project-based requirements or shorter-term growth.”
Uptick in rental performance
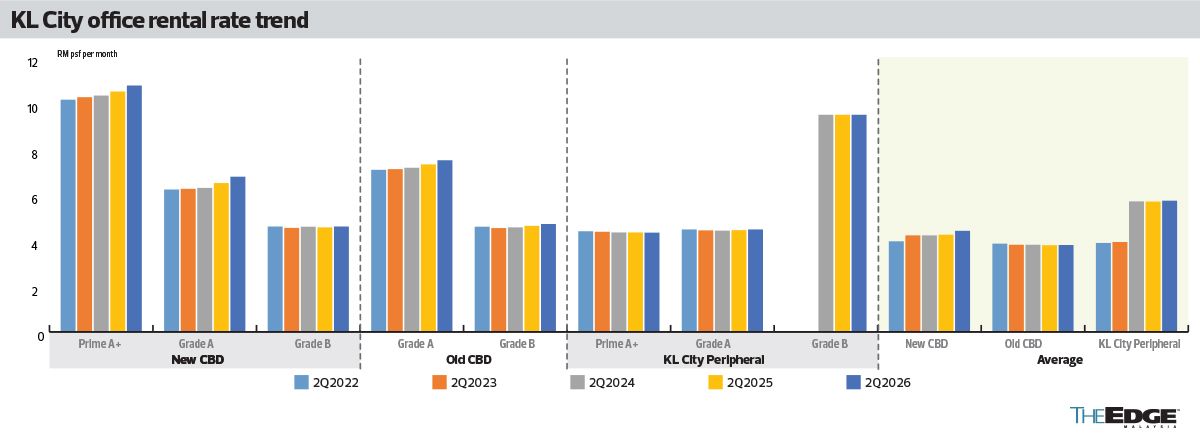
According to Wong, the increase in net absorption in 2Q2026 has contributed to higher rental rates across most localities.
Rental rates in KL City recorded an overall increase in 2Q2026 from 1Q2026, as the new CBD saw rental rates rise to RM7.51 psf per month, from RM7.45. Similarly, the old CBD recorded a slight increase to RM4.48 psf per month, from RM4.47. The KL city centre peripheral also experienced an increase in rental rates, to RM5.74 psf per month from RM5.72. Overall, the average rental rate in KL City increased to RM6.85 psf month, from RM6.80.
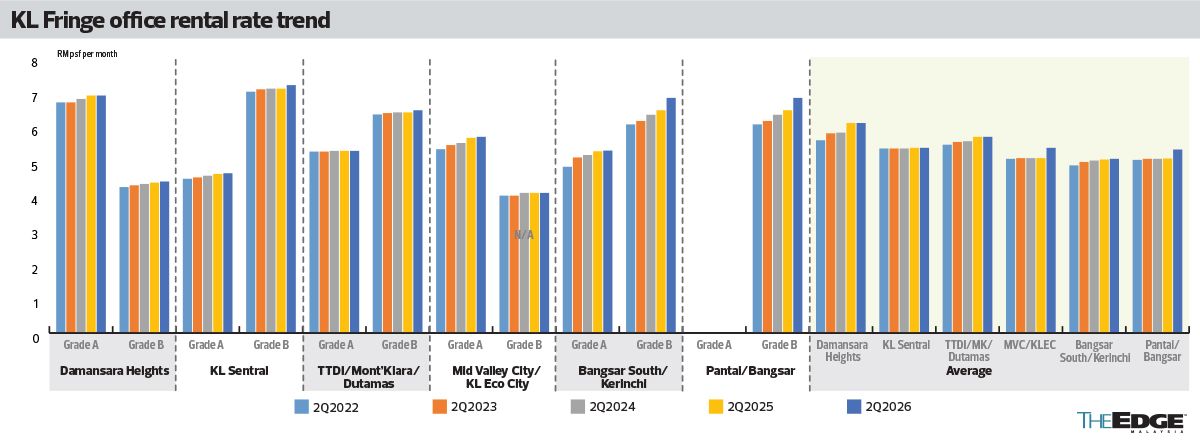
In KL Fringe, rental rates generally remained stable in 2Q2026 compared with 1Q2026, with slight increases recorded in selected localities.
Damansara Heights saw the rental rate remain at RM4.64 psf per month, while KL Sentral recorded a slight increase to RM6.47 psf per month, from RM6.46. Taman Tun Dr Ismail/Mont’Kiara/Dutamas was unchanged at RM5.30 psf per month, while Mid Valley City/KL Eco City recorded the most notable increase, to RM6.83 psf per month from RM6.64.
Bangsar South/Kerinchi and Pantai/Bangsar saw rental rates maintained at RM5.70 and RM5.33 psf respectively. Overall, the average rental rate in KL Fringe increased to RM5.92 psf per month in 2Q2026 from RM5.88 psf in 1Q2026.
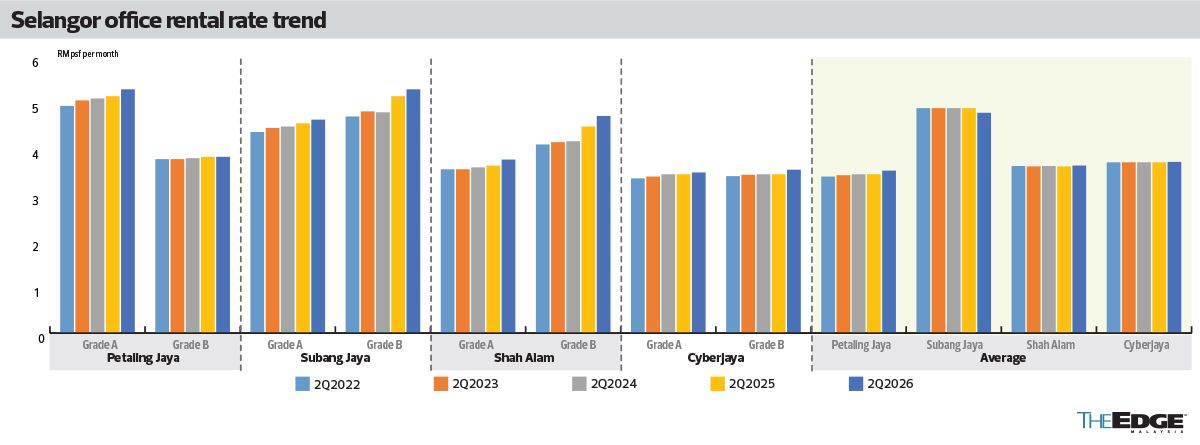
Rental rates in Selangor recorded a modest overall increase in 2Q2026 compared with 1Q2026.
Petaling Jaya saw rental rates rise to RM4.65 psf per month from RM4.61. Similarly, Subang Jaya recorded an increase to RM4.73 psf per month, from RM4.69. Shah Alam and Cyberjaya saw stable rental rates of RM3.54 and RM3.73 psf per month respectively. Overall, the average rental rate in Selangor increased to RM4.36 psf per month in 2Q2026 from RM4.33 psf in 1Q2026.
On his outlook, Teh says although manageable in scale, the timing and concentration of the pipeline for new office stock will influence absorption and competitive conditions across individual buildings and submarkets.
“Developments offering strong connectivity, efficient floor plates, quality amenities and future expansion capacity are likely to be better placed to capture demand. Capital deployment is expected to remain selective, with activity shaped by owner-occupier requirements, income visibility and capital recycling. Recent transactions point to continued interest in assets offering stable cash flow, sound location fundamentals and repositioning potential,” he adds.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.