

This article first appeared in Capital, The Edge Malaysia Weekly on October 26, 2026 - November 1, 2026
Malaysian REITs
OVERWEIGHT
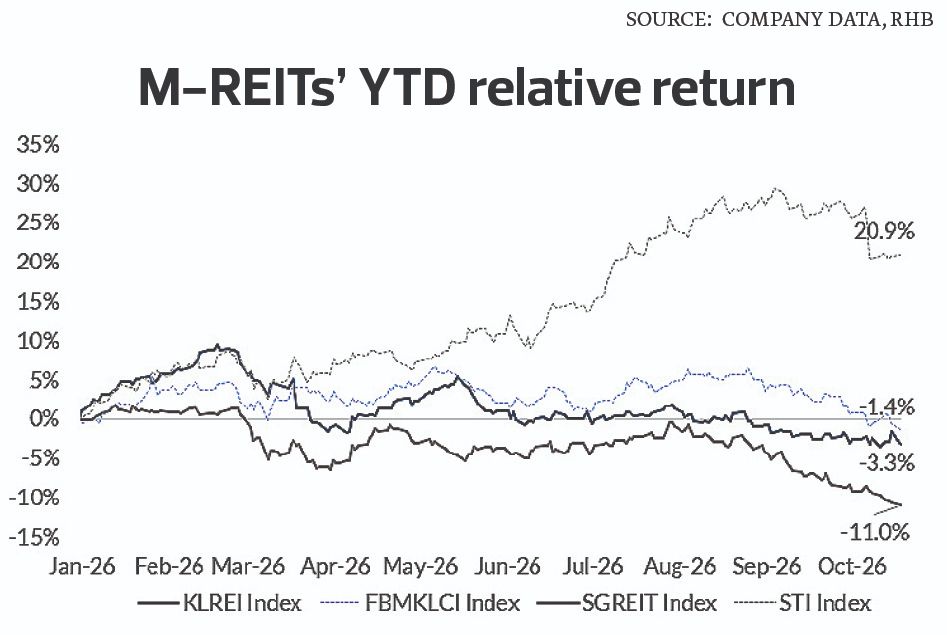
RHB INVESTMENT BANK (OCT 20): We continue to like the M-REITs sector for its defensive qualities, with underlying fundamentals still healthy despite macroeconomic headwinds and the recent rise in Malaysian Government Securities 10-year (MGS10) yields. We believe the sector de-rating has been largely valuation-driven, while occupancy rates, reversions and earnings visibility remain intact. Top picks are Axis REIT (KL:AXREIT) and Pavilion REIT (KL:PAVREIT).
The Bursa Malaysia REIT Index (KLREI)-MGS10 yield spread is currently around 230bps, close to +1SD from the long-term mean. Despite the higher risk-free rate, funding cost pressure remains manageable, with the overnight policy rate (OPR) maintained and the recent rise in longer-tenure Kuala Lumpur Interbank Offered Rate (Klibor) having a limited impact on floating-rate borrowing costs so far.
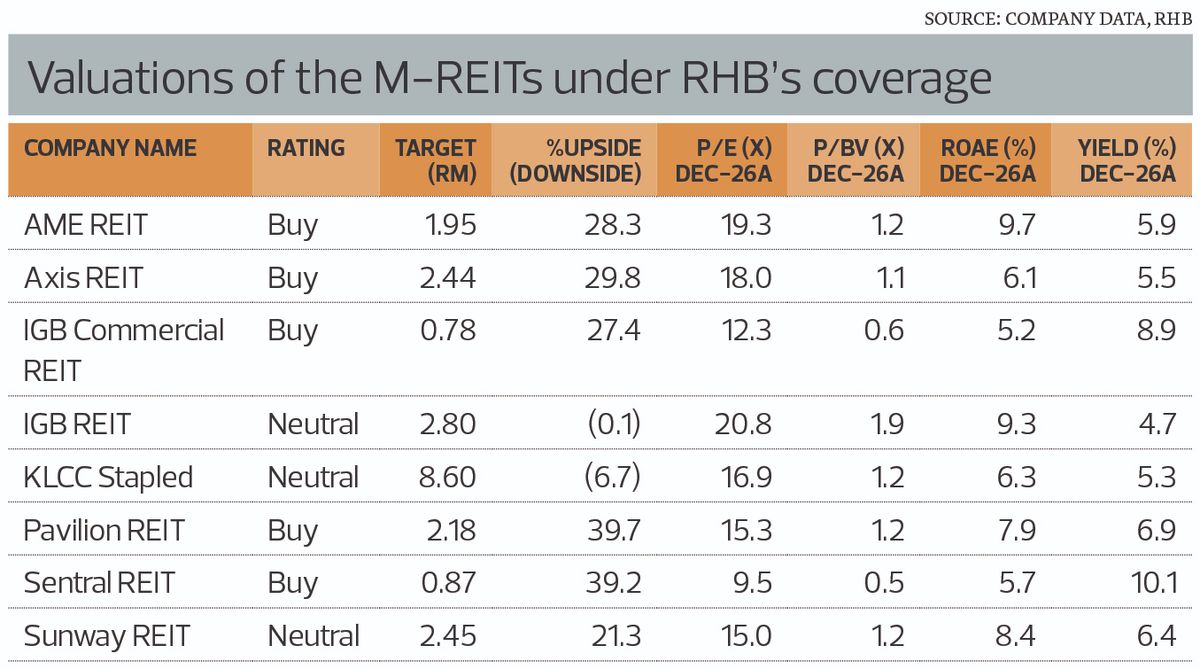
For the M-REITs that we cover, 1H26 revenue and earnings grew c.15% and c.17% y-o-y, although a meaningful part of the uplift came from IGB REIT (KL:IGBREIT) following the Mid Valley Southkey acquisition. We expect a similar pattern in 3Q26, with retail REITs likely to see a better q-o-q performance following the seasonally softer 2Q. This should be partly offset by higher utility costs following the automatic fuel adjustment (AFA) shift, which we believe could compress net property income margins by about 50-100bps for retail and office-heavy REITs.
As the Mid Valley Southkey uplift and other recent acquisitions move into the base, growth should depend more on rental productivity, asset enhancement initiatives, lease-ups and the next external growth pipeline. This should increase dispersion across the sector where prime retail increasingly relies on rental productivity and tenant optimisation, office recovery remains asset specific, while industrial offers more avenues through acquisitions. We see Axis REIT standing out on this front, supported by a visible acquisition/development pipeline with at least around RM250 million of additional opportunities under consideration.
Budget 2027 should provide incremental demand support through higher household assistance, tourism measures and investment incentives, while enhanced Global Services Hub incentives from January 2027 should support demand for higher-quality office space.
On the rate front, RHB Economics expects a 25bps OPR hike in 1H27. Assuming a full-year 25bps increase in borrowing costs, our sensitivity analysis indicates that sector FY27F earnings would decline by up to 2% — which we believe should be manageable.
Key risks include yield spread compression, higher-than-expected inflation, and macroeconomic shocks from persistently high energy prices. While RHB Economics expects a 25bps OPR hike in 1H27, we expect near-term funding cost pressure to remain manageable.
CIMB Group Holdings Bhd
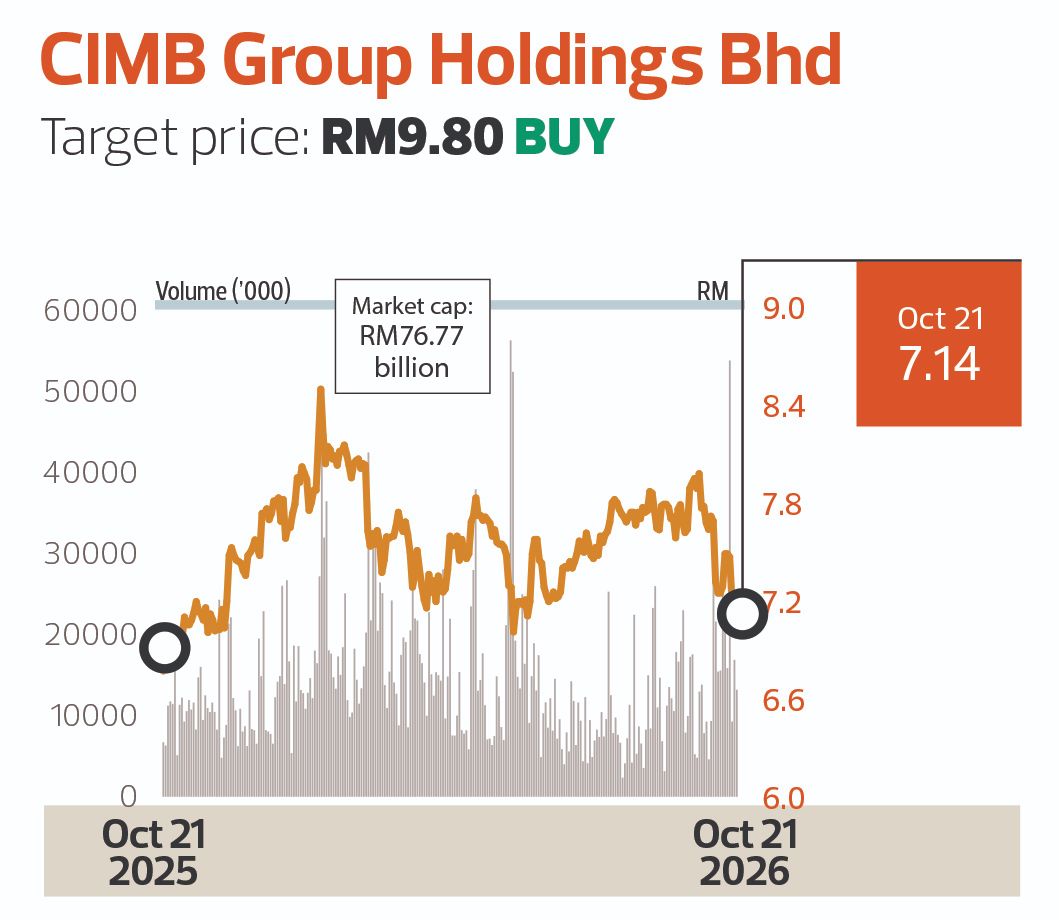
Target price: RM9.80 BUY
AMINVESTMENT BANK (OCT 21): The market has been too quick to turn bearish on CIMB Group Holdings Bhd (KL:CIMB) amid concerns over Indonesia and the recent spike in bond yields. Yet, management has retained its 11%-11.5% ROE guidance. More tellingly, CIMB bought back RM446 million worth of shares at an average of RM7.60 per share between Sept 21 and Oct 16 (about 6% above current levels). This speaks volumes to management’s confidence in the stock’s underlying value. Its attractive 6%-7% dividend yield is another reason to stay positive on CIMB.
With PT Bank CIMB Niaga Tbk’s valuation beaten down, CIMB is taking a closer look at privatisation. We see merit in such a move; at just RM600 million to RM700 million to buy the balance 7.5% stake, the potential move is well within CIMB’s means, especially with some RM850 million in excess capital from its Thai auto loan disposal (previously RM1.3 billion).
Despite market jitters over rising bond yields, CIMB indicated that 3Q26 trading income has remained resilient sequentially, as the bank was able to capitalise on heightened volatility and wider spreads. Faced with higher funding costs, CIMB is responding on several fronts by shifting towards cheaper retail deposits (from wholesale) in Malaysia, stepping up loan repricing and deposit mix optimisation in Indonesia ahead of further rate hikes, along with tapping liquidity from Singapore and Hong Kong to fund Malaysian operations at a 20-30bps cost advantage.
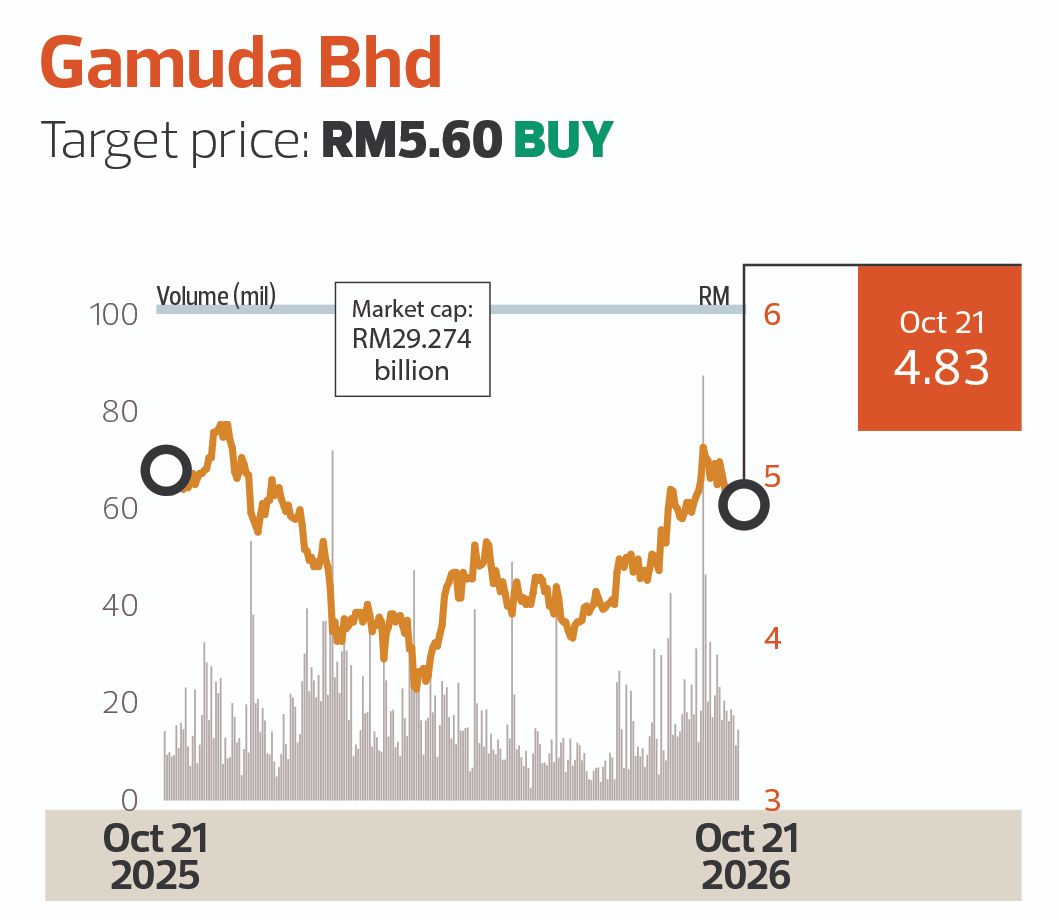
Gamuda Bhd
Target price: RM5.60 BUY
MBSB RESEARCH (OCT 21): Gamuda Bhd (KL:GAMUDA) remains our top construction pick, backed by its record pro forma RM63.9 billion order book and improving earnings visibility. Management expects construction revenue and PBT to grow by around 60% y-o-y in FY27, with 90% of revenue already covered by existing contracts. Meanwhile, property sales are targeted to more than double to RM7.0 billion in FY27, underpinned by a RM9.4 billion launch pipeline across Vietnam, Singapore and Malaysia over FY27-FY28.
Gamuda, through its 50:50 joint venture with Perbadanan Kemajuan Negeri Perak (PKNPk), Khazanah Air Perak (KAP), signed an agreement with the Perak government to implement the Northern Perak Water Supply Scheme (NPWSS). Under the agreement, KAP will undertake the raw water infrastructure works, while its wholly-owned subsidiary, Prasarana Air dan Irigasi Perak (PAIPP), will develop and operate the water treatment plants. This follows the 40-year bulk water supply agreement signed with Penang in July 2026.
Penang has committed to a minimum of 300 million litres per day offtake over 40 years, with supply targeted to commence on March 31, 2032. Based on the RM210 million annual capacity charge and RM1.70/m3 supply tariff, we estimate annual project revenue of around RM396 million, or RM198 million attributable to Gamuda through its 50% stake. Assuming a 15%-20% PAT margin, this could translate into RM30 million to RM40 million in annual attributable earnings once operations stabilise.
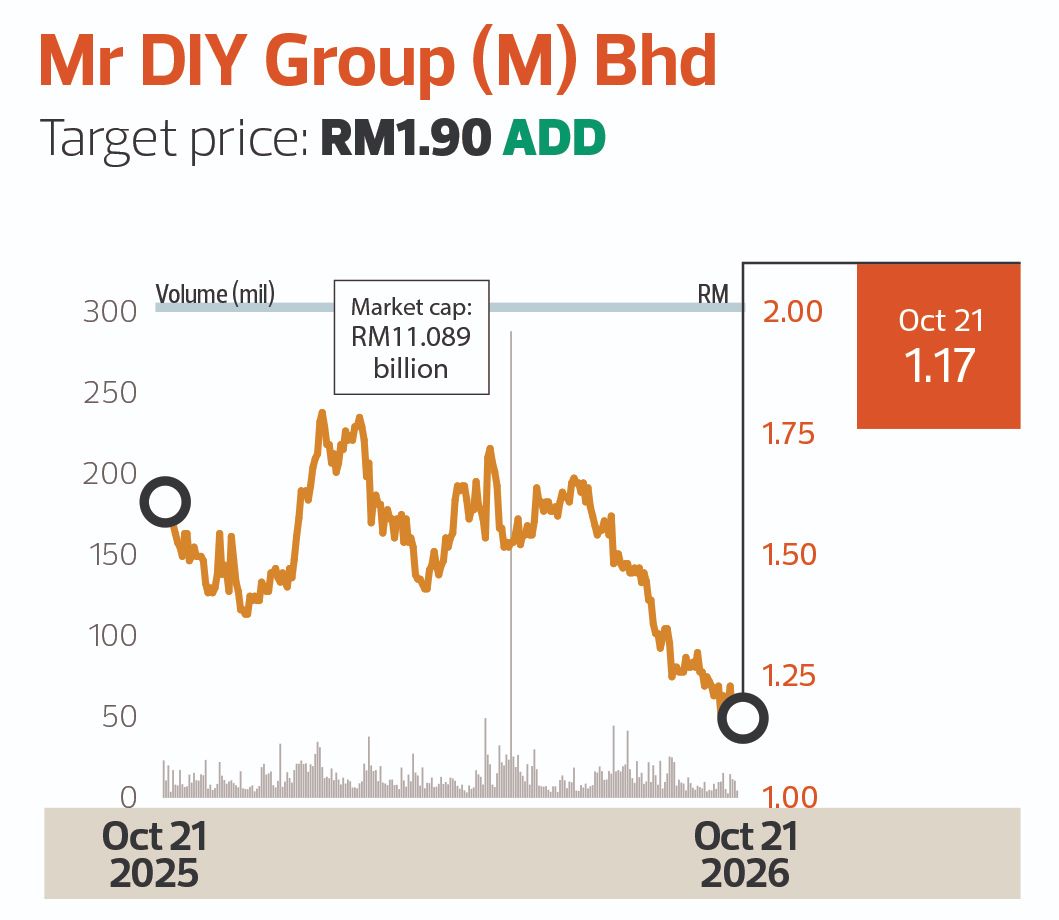
Mr DIY Group (M) Bhd
Target price: RM1.90 ADD
CGS INTERNATIONAL (OCT 21): Mr D.I.Y. Group (M) Bhd’s (KL:MRDIY) share price is down 27.3% over the past 12 months and 20.0% YTD (compared with the FBM KLCI down 1.1% over the past 12 months and 4.2% YTD). This is due to lower foreign shareholding following its reclassification to the MSCI Malaysia Small Cap Index in May 2026 and concerns over Chinese e-commerce platform Pinduoduo’s (PDD) free shipping campaign for single item purchases. We believe PDD’s appeal is largely confined to price-sensitive purchases where immediate product availability is less important.
We think PDD’s free shipping is a short-term marketing subsidy funded by PDD Holdings, similar to its strategy in the US and Europe. We estimate PDD’s Malaysia e-commerce market share at RM1 billion-RM3 billion per annum or 1.4%-3.4%, less than 0.4% of Malaysia’s total retail sales. We view PDD as a temporary headwind and do not expect free single item shipping to persist following the implementation of the E-Commerce Bill, based on the precedent in Thailand.
Mr DIY initially targeted 155 new store openings annually. However, with only 62 net new stores in 1H26, the pace of expansion has slowed, making the full-year target a challenge to achieve. We view this positively as management can focus on enhancing existing stores and improving same-store sales growth given that negative SSSG has been a key investor concern.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.