

KUALA LUMPUR (Oct 27): Seasonal recovery of crude palm oil (CPO) production is expected to drive earnings growth of the plantation sector for the third quarter of the year (3Q2026), said HongLeong Investment Bank (HLIB) Research.
“Seasonally stronger cropping trends and sustained downstream performance should drive quarter-over-quarter (q-o-q) earnings improvement in the upcoming reporting season starting Nov 5,” said the research house in a note on Tuesday.
The house expects earnings from its seven coverage companies to be largely in line with its past projections.
The upstream fresh fruit bunch (FFB) output grew between 6%-35.6% q-o-q among HLIB’s coverage companies due.
Out of seven, three planters showed stronger sequential volume growth than their Indonesian competitors, namely Hap Seng Plantations Holdings (KL:HSPLANT), Johor Plantations Group Bhd (KL:JPG) and IOI Corporation Bhd (KL:IOICORP).
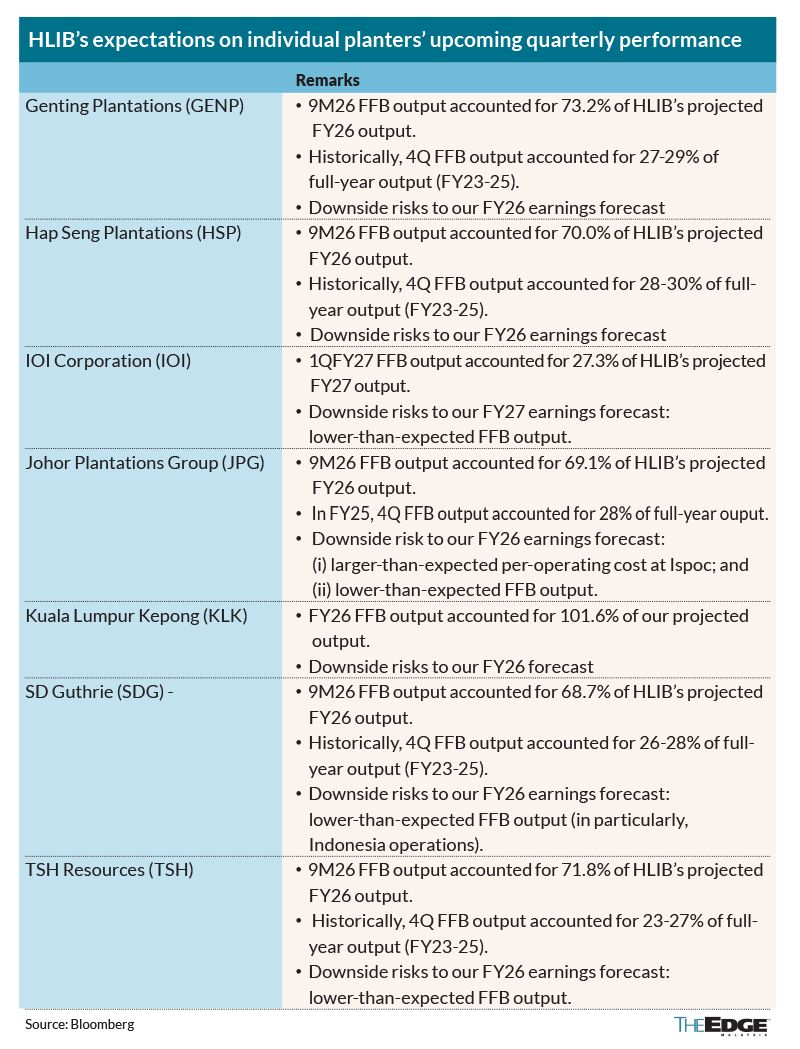
These companies are also expected to support upstream earnings growth in 3Q2026, with the exception of Johor Plantations Group, due to its FFB output being weighed down by an accelerated replanting programme which has reduced its available harvesting area.
The downstream segment, meanwhile, is expected to remain under pressure from tax differential and sector overcapacity.
But this can be reduced through active restocking in the oleochemical segment amid geopolitical uncertainties and the impending implementation of the European Union Deforestation Regulation.
HLIB maintained its 'overweight' call on the sector, with top picks being Hap Seng ('buy', target price RM2.81) and IOI Corporation ('buy', RM5.16), with a preference for planters with higher Malaysian exposure.
The research house maintained its 2027 CPO price assumption of RM4,500 per metric ton.