

This article first appeared in Capital, The Edge Malaysia Weekly on October 19, 2026 - October 25, 2026
Banks
NOMURA RESEARCH (OCT 13): We are turning increasingly bullish on Malaysian banks as the recent bond yield spike-driven derating appears overdone, in our view. Our positive stance is based on three key reasons: 1) we think concerns about bond-yield-driven earnings, capital and dividend risks may be not as severe; 2) sector valuations have reset and many stocks are trading at attractive levels with healthy yield support; and 3) incremental tailwinds from Budget 2027 via minimum wage hike, deposit formalisation, loan demand and asset quality.
We upgrade Public Bank Bhd (KL:PBBANK) and RHB Bank Bhd (KL:RHBBANK) to “buy”, reiterate “buy” for CIMB Group Holdings Bhd (KL:CIMB), AMMB Holdings Bhd (KL:AMBANK) and Malayan Banking Bhd (KL:MAYBANK), while keeping Alliance Bank Malaysia Bhd (KL:ABMB), Hong Leong Bank Bhd (KL:HLBANK) and Affin Bank Bhd (KL:AFFIN) at “neutral”. This is the order of our preference: CIMB, AMMB, Maybank, Public Bank and RHB Bank.
While we cut FY26F earnings across the stocks under our coverage to reflect weaker bond trading income, we leave FY27F earnings broadly unchanged. We see our bullish thesis playing out through a rotation back into banks on stabilising/declining bond yields, alongside year-end repositioning to capture the net interest margin upside from our 25 basis point (bps) policy rate hike forecast in the coming months.
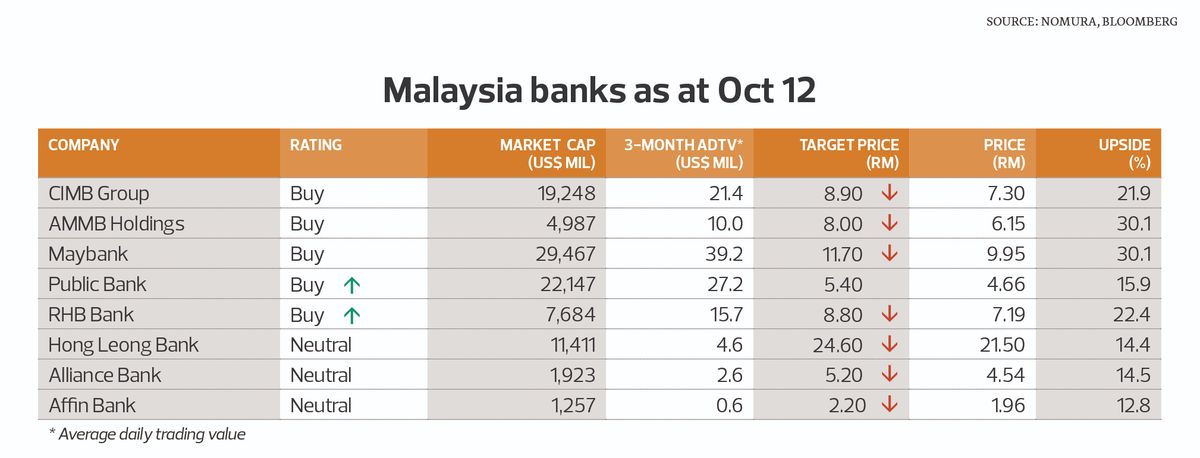
We believe market concerns about the impact of rising bond yields on banks’ earnings, capital and dividends are likely overstated. Our illustrative sensitivity analysis across the eight banks under our coverage, applying a hypothetical 50bps yield shock, suggests a manageable pro forma earnings impact of 0% to -6% (before any hedging or treasury offsets), and a Common Equity Tier 1 (CET-1) impact of just -6bps to -37bps, leaving pro forma CET-1 ratios comfortably at 12.4% to 14.8%. This should pose limited risk to dividend payout capacity. Moreover, mark-to-market losses are not necessarily permanent. Should yields stabilise or decline, bond valuations may improve, while banks could benefit from reinvestment at higher rates, supporting net interest income going into FY27F.
We think valuations have turned attractive again, with dividend yields providing added support. Following a ~15% correction in the KL Financial Index from its mid-February peak, driven by mixed capital management outcomes, geopolitical and macro concerns, domestic political uncertainty and FBM KLCI expansion fears, the sector now trades at a forward P/B of 1.01 times and a forward PER of 9.6 times, both below 5- and 10-year averages, against still resilient return on equity of ~10.1%. The dividend yield spread over 10-year Malaysian Government Securities has widened to ~264bps from ~150bps at the February peak, even as MGS yields eased from their September peak. We also view fears of forced selling from the FBM KLCI’s expansion to 50 constituents as overdone, given limited passive tracking and phased implementation in 2026/27.
MN Holdings Bhd
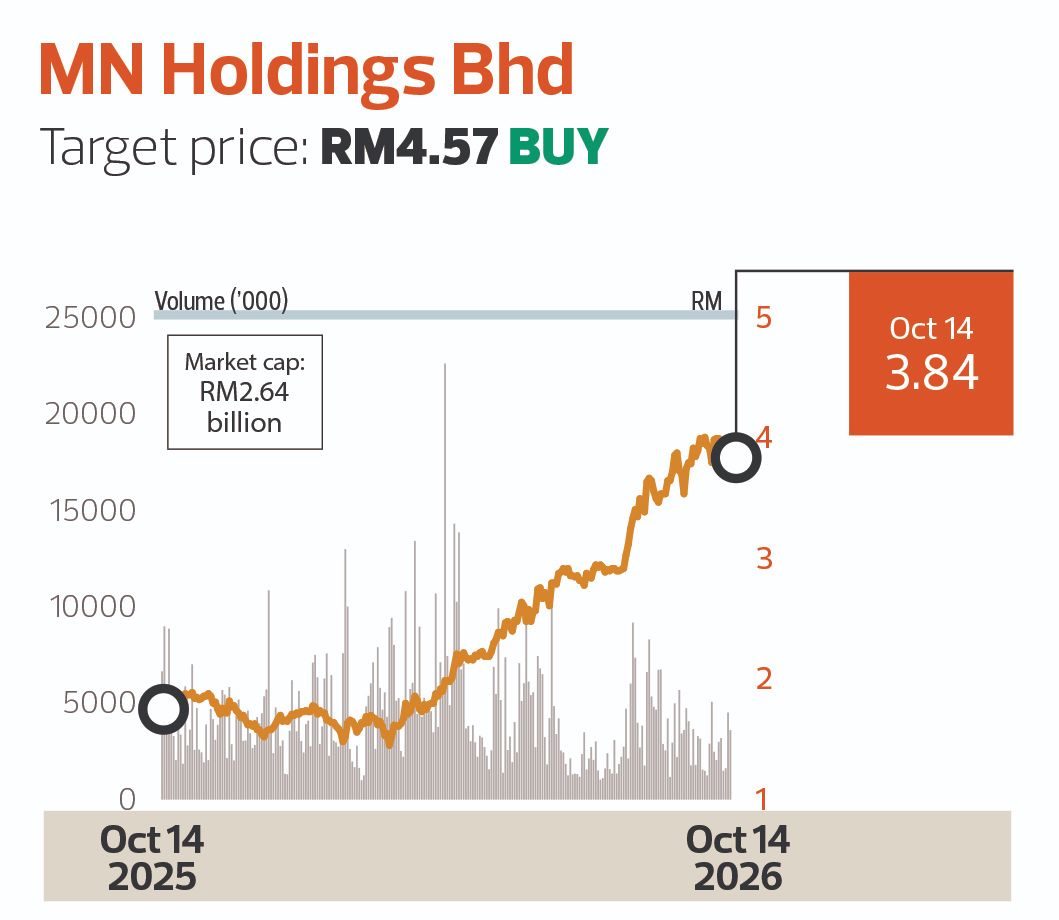
Target price: RM4.57 BUY
PHILLIP CAPITAL (OCT 13): MN Holdings Bhd’s (KL:MNHLDG) wholly-owned subsidiary, MN Power Transmission Sdn Bhd, has secured a letter of award from Company A valued at RM294 million. The contract covers the construction, supply, installation, testing and commissioning of two 275kV consumer landing stations (CLS) for a data centre (DC) in the central region of Peninsular Malaysia.
The award represents MN’s largest single contract win to date, surpassing the previous record of RM276 million for a 275kV CLS project in the central region. The contract win brings YTD wins to about RM600 million, equivalent to 46% of our RM1.3 billion replenishment assumption, and lifts the outstanding order book to about RM2 billion (equivalent to 2.2 times FY26 revenue cover). Assuming a net margin of 8%, we estimate the contract to contribute PAT of RM24 million over the contract period. The group’s tender book stands at about RM4.7 billion.
We reiterate our “buy” and 12-month target price, based on unchanged PER of 24 times on fully diluted CY27f EPS. We continue to view MN as a proxy for Malaysia’s expanding power infrastructure with strategic exposure in the rapidly growing DC and solar sectors.
IJM Corp Bhd
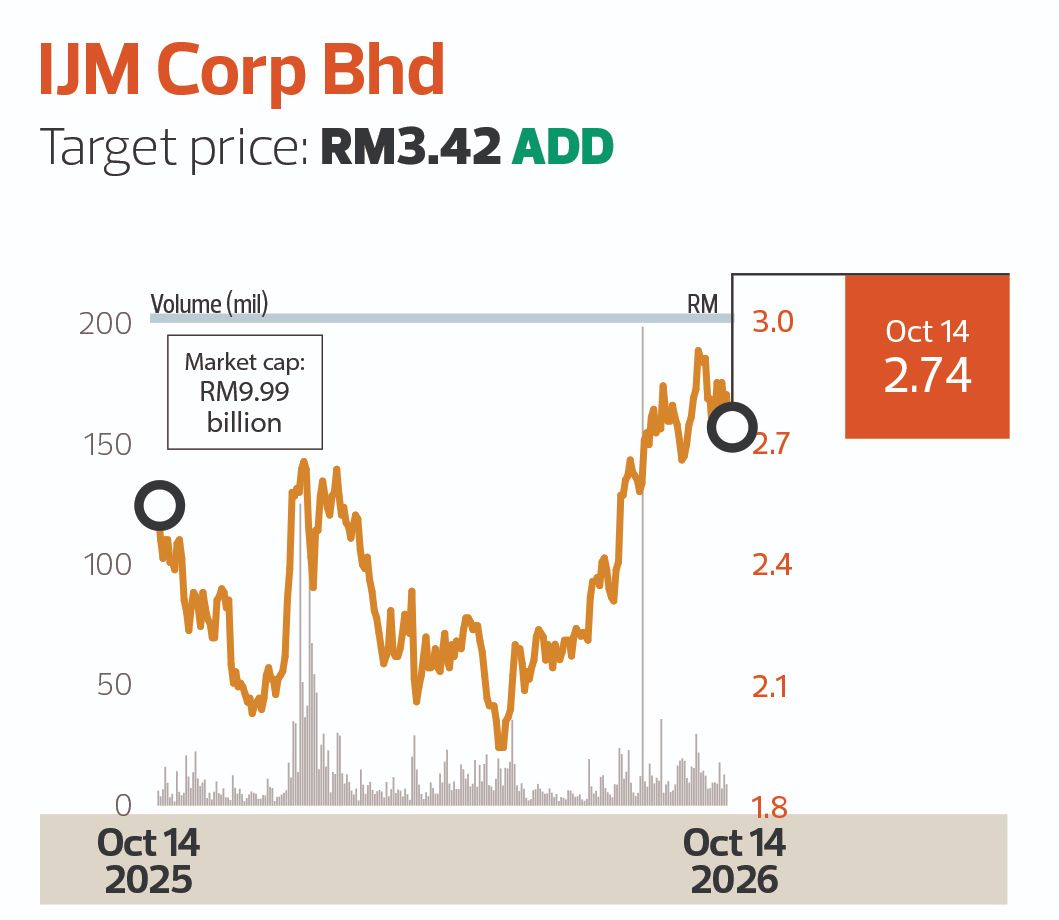
Target price: RM3.42 ADD
CGS INTERNATIONAL (OCT 12): IJM Corp Bhd (KL:IJM) won a RM1.23 billion contract from AT&S Austria Technologie & Systemtechnik (Malaysia) Sdn Bhd. This win brings IJM’s FY27 (ending March 31, 2027) YTD wins to about RM3 billion and its Malaysia and Singapore construction order book to RM10.6 billion.
Given that this is a design-and-build contract, we expect pretax margins to be at the higher end of the 6% to 9% range it usually guides for. We believe IJM’s semiconductor/medical space exposure will be the key differentiating factor between IJM and its closest competitors in the lead-up to its potential construction initial public offering (IPO). We expect IJM to be more aggressive in replenishing its order book over the next nine to 12 months, with the potential listing of its construction business, which the company expects in 3QCY27F. It is targeting RM4.5 billion to RM5 billion in construction business revenue for FY27F, above our RM4.1 billion forecast.
IJM said it is committed to distributing RM1.2 billion in dividends to its existing shareholders from this IPO. We believe this payout will be in cash and represent a 12% yield at its current price. We reiterate our “add” and target price, which values construction at an FY27F PER of 18 times, or RM3.1 billion.
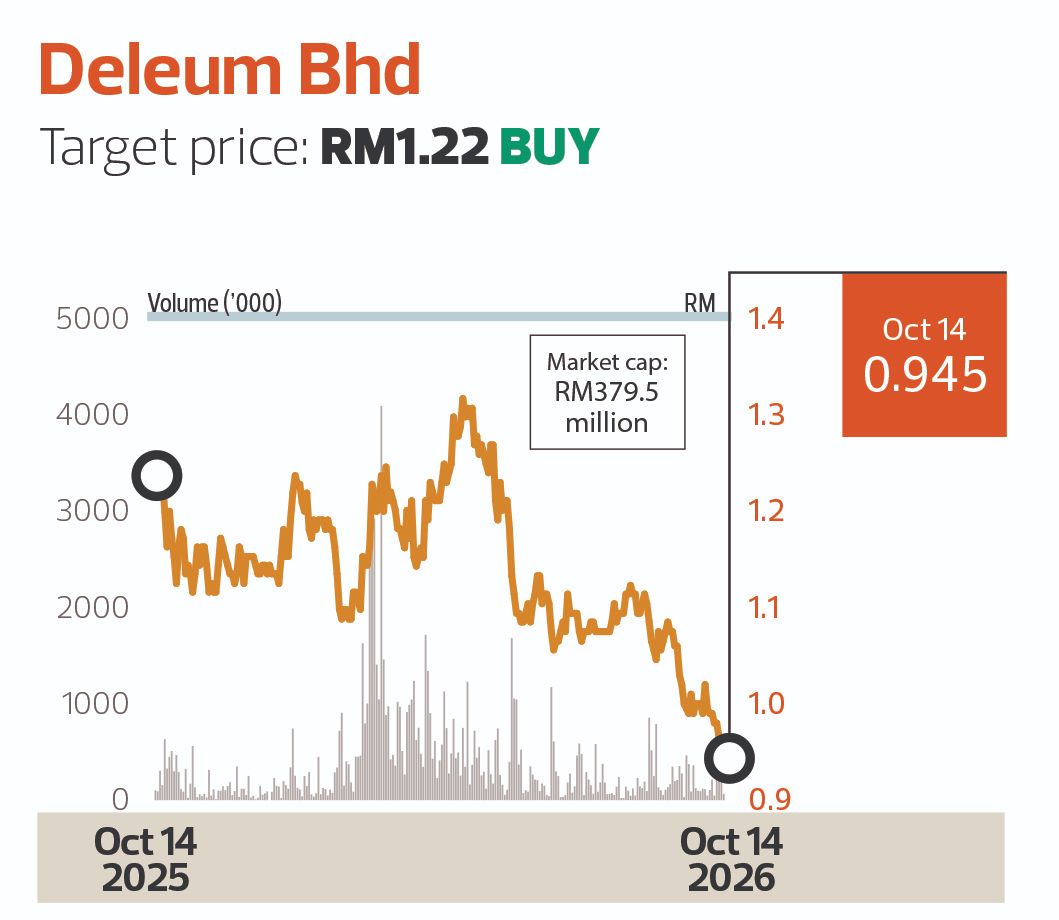
Deleum Bhd
Target price: RM1.22 BUY
MBSB RESEARCH (OCT 13): Deleum Bhd’s (KL:DELEUM) subsidiaries — Deleum Services Sdn Bhd and Delcom Holdings Sdn Bhd — have entered into a heads of agreement to dispose of a collective 86.67% stake in Deleum Technology Solutions Sdn Bhd to Ocean Vantage Holdings Bhd. The disposal aligns with Deleum’s strategic direction to optimise its asset portfolio and develop the value of its investments.
We opine that the RM13 million in cash proceeds will be utilised for capital reallocation, which will subsequently improve Deleum’s liquidity and overall financial standing. The funds will provide the group with the financial flexibility to redeploy capital towards businesses and opportunities with stronger earnings visibility and growth potential. We note that the deal remains subject to the successful negotiation and execution of a definitive share sale agreement (SSA) within the 90-day deadline, as well as obtaining necessary financier or third-party approvals. If negotiations stall or approvals fail, the deal could fall through.
As the two parties have until January 2027 to negotiate and execute a definitive SSA, unless mutually extended, we make no change to our earnings estimates for Deleum at this juncture. We maintain our “buy” and target price.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.