

This article first appeared in Capital, The Edge Malaysia Weekly on October 19, 2026 - October 25, 2026
THIS week will see two more companies debut on Bursa Malaysia’s ACE Market — health food and personal care products supplier NWE Resources Group Bhd on Wednesday, and railway technology and enterprise ICT (information and communications technology) solutions provider RedPlanet Bhd (KL:RPLANET) on Thursday.
NWE Resources is raising RM28.6 million through its initial public offering (IPO), while RedPlanet is raising RM13.3 million through a public issue as it transfers from the LEAP Market.
The public portions of the two offerings have drawn markedly different levels of demand, with NWE Resources’ oversubscribed by 2.8 times and RedPlanet’s by 85.8 times. While NWE Resources plans to accelerate growth through product development and in-house manufacturing, RedPlanet is looking to capitalise on demand for geospatial technologies and railway safety systems.
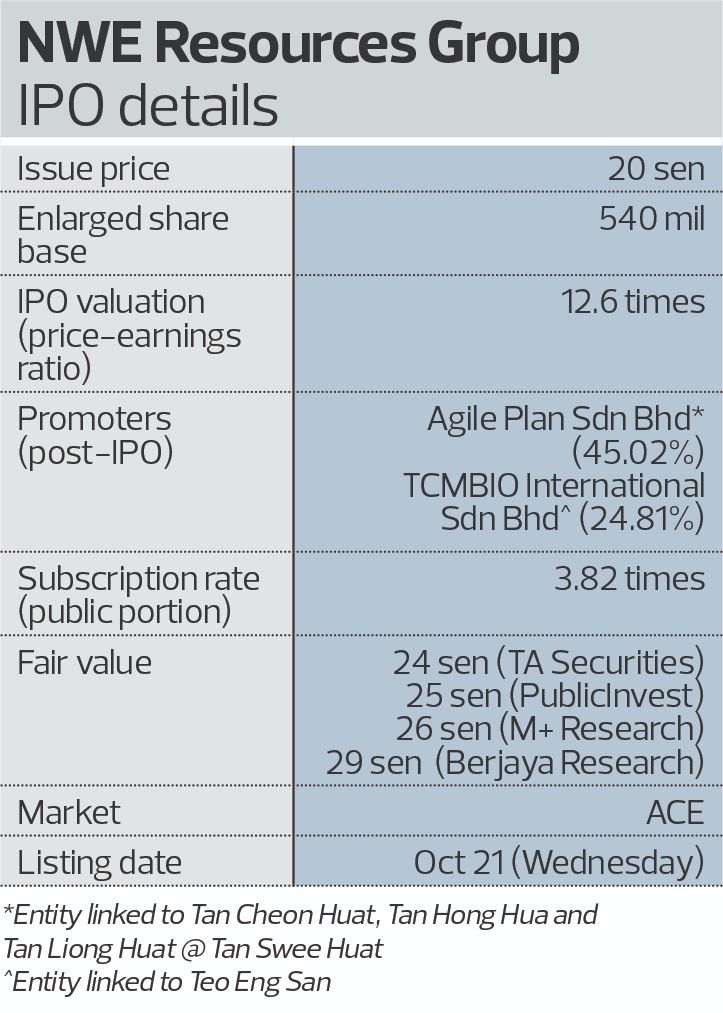
NWE Resources is issuing 143.1 million new shares at 20 sen apiece, representing 26.5% of its enlarged share capital of 540 million shares. The IPO, which has no offer for sale, values the group at RM108 million.
Of the RM28.6 million in gross proceeds, RM9.1 million, or 32%, is earmarked for product development. Another RM1.2 million will go towards expanding its research and development (R&D) capabilities, while RM4.6 million has been allocated for marketing and promotional activities. The remaining proceeds will fund working capital, equipment, transportation fleets, a new sales office and listing expenses.
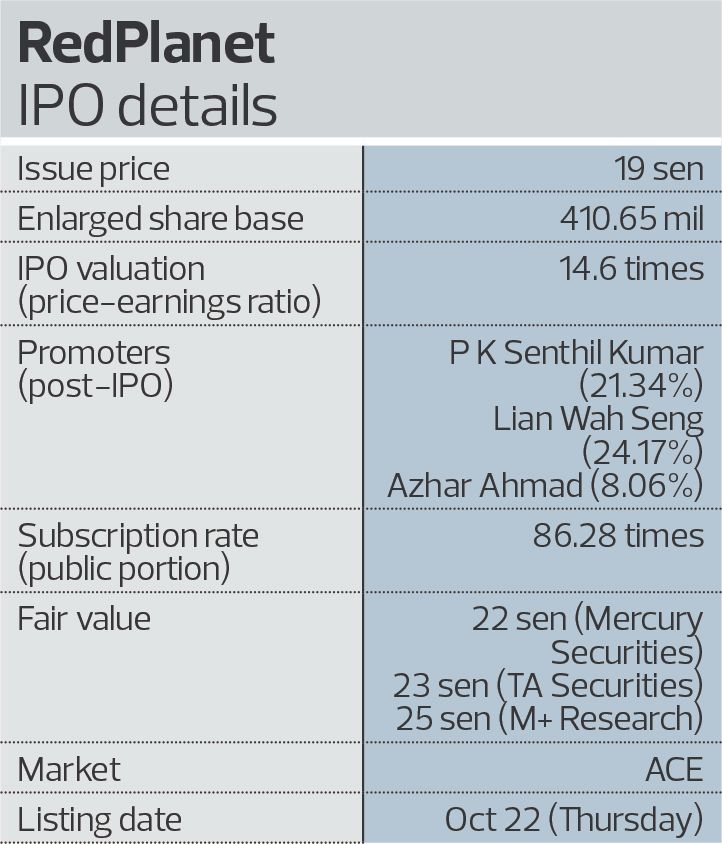
RedPlanet’s IPO comprises 70 million new shares and an offer for sale of 10 million existing shares, priced at 19 sen apiece. Based on its enlarged share capital of 410.7 million shares, the group will have a market capitalisation of RM78 million upon listing.
Of the RM13.3 million in gross proceeds from the new shares, RM8.1 million, or 61.1%, will be used for business expansion. Another RM2.4 million is earmarked for working capital, with the remaining RM2.8 million allocated for listing expenses.
NWE Resources
With a business dating back to 1979, NWE Resources supplies health foods and personal care products to consumers through its M-Plan multi-level marketing (MLM) network. It also supplies hospitality amenities and repackaged food and beverage products to hotels and resorts, while developing health food formulations for brand owners.
The group has operated its hospitality supply business for 39 years, while its M-Plan direct-selling business has been around for about three decades. As at Aug 28, it had 7,309 active M-Plan distributors selling 21 stock-keeping units of health foods, personal care and related products.
The two core businesses — health food and personal care products — account for more than 90% of revenue. Malaysia contributes more than 90% of revenue. Its other markets include Singapore, Indonesia, Brunei, Hong Kong, the Maldives and South Korea.
NWE Resources is looking to build on its established market presence by expanding its product portfolio and strengthening its R&D capabilities.
In an Oct 9 report, PublicInvest Research highlights the group’s in-house R&D capabilities as a key growth driver. As at Aug 28, NWE Resources had developed 20 health food formulations and has plans to broaden its offerings to capture demand for health and personal care products.
The product development programme will cover six new health food formulations and five skincare formulations. The group currently outsources the manufacturing of its health food products to contract manufacturers or obtains them in ready-to-sell form from third-party brand owners.
It plans to establish in-house manufacturing capabilities at its Glenmarie facility in Shah Alam for liquid, semi-liquid and powdered health food products. The move is intended to give it greater control over production, inventory costs and quality, while shortening lead times. It also plans to bring the manufacturing of selected existing products in-house and repackage Miki Prune Extract at its own facility.
In skincare, the group intends to develop five formulations — sunscreen with moisturiser, overnight face masks, face mists, skin protection products and moisturising lip care. These will add to its Essando brand, launched in October 2025 with five products manufactured by a contract manufacturer.
To support the expansion, NWE Resources plans to enlarge its Glenmarie laboratory and increase its R&D team from five to 11 employees within 24 months of listing. The additional hires will include two nutritionists, two chemists and two laboratory assistants.
Beyond product development, the group plans to establish an M-Plan sales office in Johor within 24 months of listing to strengthen its presence in southern Peninsular Malaysia. It will also participate in nine exhibitions over three years in Malaysia, China and the Middle East, while expanding its e-commerce and digital marketing activities.
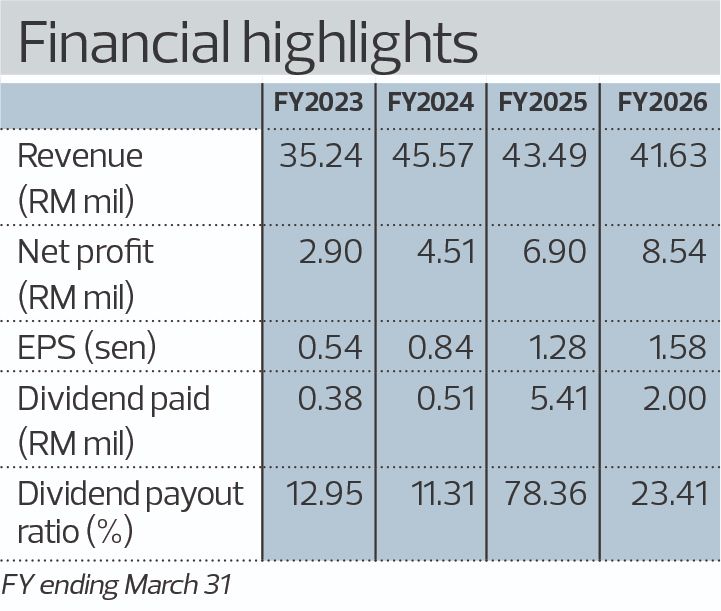
The expansion comes as NWE Resources seeks to reverse two consecutive years of declining revenue. Revenue fell from RM45.6 million in the financial year ended March 31, 2024 (FY2024), to RM43.5 million in FY2025 and RM41.6 million in FY2026.
The decline reflected weaker sales of hospitality amenities, following the completion of major high-volume contracts, as well as changes in the group’s sales mix. However, a shift towards higher-yield customers and better-margin products has helped improve profitability despite lower revenue.
Gross profit rose from RM13.7 million in FY2023 to RM21.8 million in FY2026, while gross profit margin expanded to 52.4% from 39%. In personal care and related products, the gross profit margin increased to 44.8%, from 24.7%, over the same period, supported by higher-yield customers, better-margin own-brand products, higher average selling prices and favourable supplier pricing. Net profit consequently increased from RM2.9 million in FY2023 to RM8.5 million in FY2026.
TA Securities forecasts net profit to rise to RM9.9 million in FY2027 and RM11.4 million in FY2028, with revenue projected at RM43.5 million and RM46.4 million respectively. Its forecasts assume growth in hospitality product sales, a 1% annual increase in active MLM members and annual sales growth of 3% to 5% per member. Gross profit margins are expected to remain above 50% in both years.
PublicInvest Research is more bullish on the group’s growth prospects, projecting revenue of RM47.9 million in FY2027, RM55.1 million in FY2028 and RM63.3 million in FY2029. Net profit is forecast to increase to RM9.7 million in FY2027 and RM12.7 million in FY2029, implying a three-year compound annual growth rate (CAGR) of 14.1% from FY2026.
NWE Resources remains exposed, however, to customer and supplier concentration risks, as well as fluctuations in tourism activity.
“Customer A” — whose identity is not disclosed — contributed between 13.5% and 14.3% of revenue from FY2024 to FY2026, according to PublicInvest Research. It notes that although NWE Resources owns the formulations supplied to this customer and has contractual protections over their disclosure, the loss of the customer could still affect the group’s financial performance.
Miki Corporation, La Bottega Group and “Supplier A” collectively accounted for 34.9% to 41.5% of the group’s purchases between FY2023 and FY2026. Miki-branded health food products alone contributed between 27.1% and 30.5% of revenue over the period, highlighting the importance of these supplier relationships to the group’s business.
Its hospitality supply business also leaves it vulnerable to weaker hotel occupancy and reduced tourism spending, which could weigh on demand for personal care products and hospitality amenities.
TA Securities values the group at 24 sen a share, based on a forward price-earnings ratio (PER) of 13 times its forecast calendar year 2027 earnings. PublicInvest Research has a fair value of 25 sen, based on a PER of 12.5 times forecast CY2027 earnings.
KAF Investment Bank Bhd is the principal adviser, sponsor, underwriter and placement agent for the IPO.
RedPlanet
RedPlanet is looking to capitalise on demand for digital infrastructure and railway safety systems as it transfers its listing to the ACE Market.
Established in 2016, the group provides enterprise ICT solutions through three segments: geospatial solutions, intelligent rail solutions and ICT trading. Its geospatial business helps infrastructure operators digitalise and manage physical assets, while its rail business focuses on railway safety and communication systems. The ICT trading segment supplies related hardware, software and components.
RedPlanet’s revenue reached RM40.7 million in the financial year ended June 30, 2026 (FY2026), with geospatial solutions contributing 45.1%, intelligent rail solutions 28.4% and ICT trading 26.5%. Malaysia accounted for 87% of revenue, with the remainder generated from overseas markets.
Its customers include government agencies, utilities, rail operators, infrastructure companies and multinational corporations. One of its key relationships is with a major Malaysian electricity utility, which has engaged the group since 2016 to provide geospatial solutions for managing its power infrastructure.
RedPlanet intends to use its listing proceeds to strengthen its capabilities and pursue larger infrastructure-related projects, particularly in geospatial and intelligent rail solutions.
As at Aug 29, the group had a secured order book of RM51.74 million, comprising RM18.17 million from geospatial solutions and RM33.58 million from intelligent rail solutions. Of this, RM32.47 million is expected to be recognised in FY2027, equivalent to about 79.7% of FY2026 revenue, providing near-term revenue visibility.
It also had 11 submitted tenders worth RM132.05 million, more than 2½ times its existing order book. However, the tenders remain subject to contract awards.
RedPlanet is expanding its rail business beyond its proprietary Platform Intrusion Emergency Stop (PIES) system into Central Transmission System (CTS) solutions, which provide communication links between railway control centres and critical rail subsystems.
The PIES system detects intrusions onto railway tracks and signals the train system to prevent trains from entering affected stations. Protected by registered patents in six countries, it has been deployed at more than 88 railway stations in Malaysia.
RedPlanet has secured two CTS projects worth roughly RM32.47 million, providing a growth avenue beyond its established railway safety technology. It is also looking to tender for upcoming infrastructure projects, including the Penang Mutiara Line light rail transit (LRT) and Johor’s automated rapid transit system (RTS).
The group is also developing artificial intelligence (AI) applications to enhance its existing offerings.
In geospatial solutions, it is developing an AI Asset Detection Tool to automate the identification and digitalisation of physical assets from mapping data. The tool remains at the prototype stage, with commercialisation targeted by end-2026, subject to successful testing.
For its rail business, RedPlanet is developing a drone-based Automated Open Track AI Detection and Early Warning System to identify potential obstacles on railway tracks and alert operators in real time. The system is undergoing internal testing, with feedback obtained from two Malaysian rail operators.
The expansion is underpinned by a growing market for geospatial technologies. According to an industry report cited by TA Securities, Malaysia’s geospatial solutions market grew from RM6.7 billion in 2021 to RM11.3 billion in 2025, representing a CAGR of 14%. It is projected to reach RM15.1 billion by 2028, implying a CAGR of 10.1% from 2025.
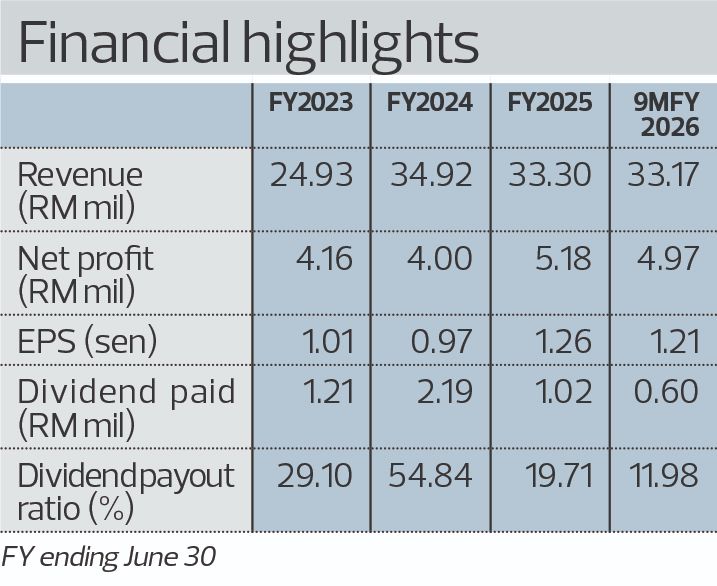
RedPlanet’s revenue grew from RM24.9 million in FY2023 to RM40.7 million in FY2026, representing a three-year CAGR of about 17.8%.
In FY2024, revenue rose 40.1% to RM34.9 million, supported by contributions from intelligent rail projects, following the consolidation of its rail technology subsidiary. It subsequently declined 4.6% to RM33.3 million in FY2025, owing mainly to lower ICT trading revenue, before rebounding 22.3% in FY2026 as ICT hardware and software sales recovered.
Net profit increased from RM5.2 million in FY2025 to RM6.3 million in FY2026.
Looking ahead, TA Securities expects core profit to ease to RM6.2 million in FY2027 as the effective tax rate normalises, following the utilisation of previously unrecognised tax losses in FY2026. Earnings are forecast to recover to RM6.7 million in FY2028 and RM7.3 million in FY2029, supported by progressive recognition of its order book, contributions from CTS projects and potential new contract wins.
Mercury Securities projects a stronger recovery, forecasting core net profit of RM7.1 million in FY2028 and RM8 million in FY2029, after an estimated RM4.3 million in FY2027. It expects revenue to increase to RM55 million in FY2027, RM57.9 million in FY2028 and RM63 million in FY2029.
Profitability will depend partly on RedPlanet’s ability to maintain a higher contribution from its core businesses. In FY2026, geospatial solutions recorded a gross profit margin of 42.1%, while intelligent rail solutions achieved 62%, compared with just 7.2% for ICT trading.
A sustained shift towards geospatial and intelligent rail solutions could therefore support overall margins, although the project-based nature of the business means revenue and earnings may fluctuate depending on the timing of contract awards and execution.
Customer concentration remains another risk. RedPlanet’s relationship with the major Malaysian electricity utility has generated 239 contracts and purchase orders worth a cumulative RM138.98 million since 2016. While this demonstrates customer stickiness and specialised industry expertise, dependence on large customers exposes the group to changes in their project awards and spending decisions.
Its revenue visibility also depends on replenishing its order book, as submitted tenders do not guarantee future contracts. Project execution schedules, milestone billings and customer collections can further affect working capital and cash flow.
Operating cash flow has fluctuated in recent years, turning negative at RM1.56 million in FY2024 before recovering to RM4.69 million in FY2025 and RM9.56 million in FY2026. The fluctuations largely reflected changes in receivables and contract assets associated with major rail projects.
The ability to undertake larger projects will also depend on working capital, as performance bonds typically require 5% to 10% of a contract’s value. The IPO proceeds allocated for working capital should provide additional liquidity, but sustained expansion will require effective cash-flow management.
TA Securities has a target price of 23 sen, implying potential upside of 21.1%, based on a forward PER of 14 times its forecast CY2027 core earnings. Mercury Securities has a fair value of 22 sen, representing potential upside of 15.8%, and recommends subscribing to the IPO.
RedPlanet’s net gearing stood at 0.22 times in FY2026. Following the listing and utilisation of proceeds, its net cash position is expected to increase to RM33.9 million from RM22.4 million, according to TA Securities. The group does not have a formal dividend policy.
UOB Kay Hian (M) Sdn Bhd is the principal adviser, sponsor, underwriter and placement agent for RedPlanet’s IPO and transfer of listing to the ACE Market.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.