

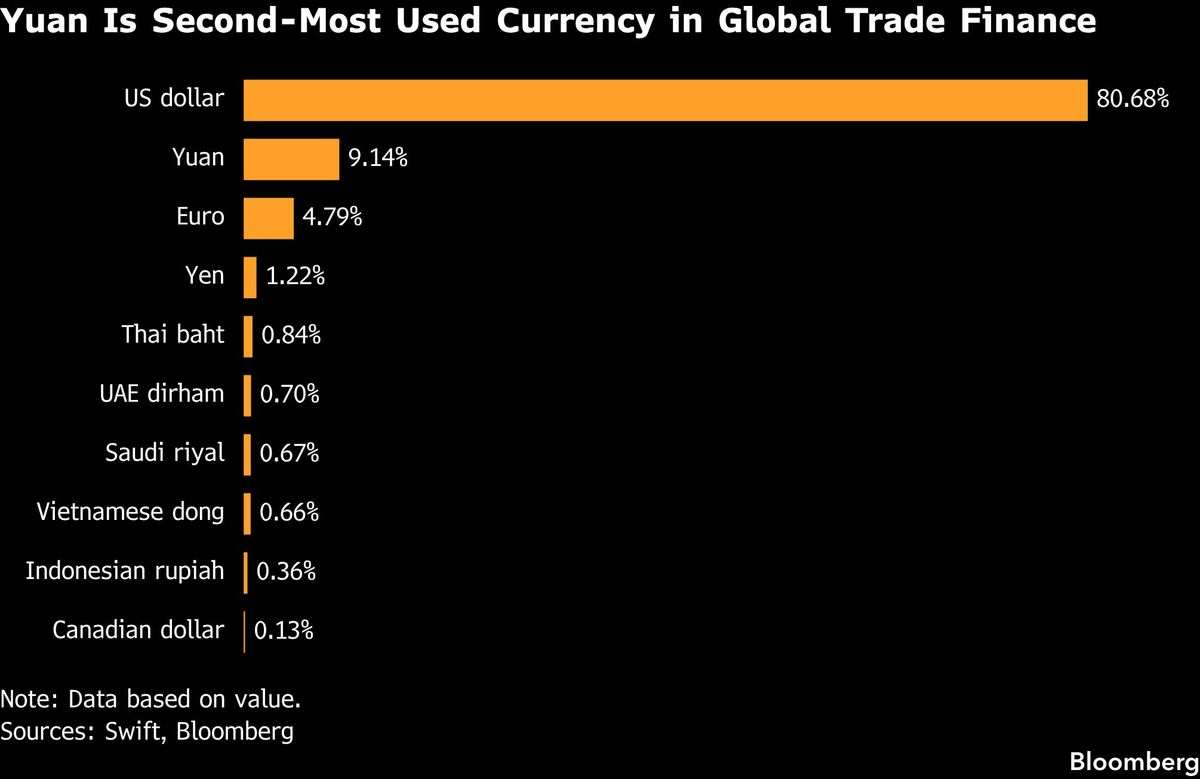
(Oct 16): China’s campaign to promote the global use of the yuan appears to be accelerating as the authorities seek to build a more comprehensive financial ecosystem for the currency beyond just trade settlement.
Beijing is focused on developing the infrastructure needed to expand the yuan’s use in global financing and investment, and to strengthen its role as a reserve currency. This includes broadening the range of available investment products and financial instruments, such as derivatives and hedging tools, while making it easier for borrowers to issue so-called dim sum and panda bonds.
China’s challenge is no longer simply to persuade its trading partners to settle transactions in yuan. It must also ensure that the currency has sufficient liquidity, financing channels, investment products, and reserve assets to play a larger role in global portfolios and capital flows.
Here are four areas where Beijing is making progress towards the yuan’s internationalisation:
1. Creating more offshore-yuan investment products
Measures to broaden offshore yuan-denominated investment products include plans to increase the scale and frequency of government bond issuance in Hong Kong, where policymakers are seeking to develop a yield curve for the currency.
Hong Kong authorities are also studying the introduction of short-term yuan debt instruments and plan to launch a redesigned yuan-denominated gold futures contract.
“The next policy focus will likely be on speeding up the development of renminbi asset markets,” said Tommy Wu, a senior economist for Greater China and North Asia at Standard Chartered plc in Hong Kong. “One of the key challenges is how to capitalise on global investors’ increasing needs for diversification and attract them to increase their investment in renminbi assets.”
2. Adding yuan derivatives and hedging tools
Many overseas investors will be reluctant to increase their yuan holdings unless they have ways to manage volatility, interest-rate and currency risks.
China’s authorities are seeking to address these concerns in several ways, including by expanding a major derivatives trading link with Hong Kong to give foreign investors access to more onshore interest-rate products. In August, they also introduced a new set of government bond futures in Hong Kong, giving global investors another hedging tool.
“Institutions will not hold substantial renminbi balances without instruments offering suitable duration, liquidity and risk management,” said Tommy Xie, the head of Asia macro research at Oversea-Chinese Banking Corp (OCBC) in Singapore. “The missing piece is therefore not just ‘more renminbi assets’ but a full asset-liability and hedging chain.”
3. Deepening yuan’s role in financing
Mainland China and Hong Kong are both seeking to make the currency a more widely used financing vehicle by expanding onshore and offshore funding channels. China plans to make panda bond issuance and trading more accessible to overseas borrowers. Panda bonds are yuan-denominated debt issued in mainland China by foreign entities.
Hong Kong is seeking to encourage further issuance of yuan-denominated debt in the city and aims to develop an “enhanced tenor structure” for dim sum bond issuance. Dim sum bonds are securities denominated in yuan and issued outside mainland China. The city is also seeking to increase yuan liquidity, making it easier for governments and companies to raise funds in the currency.
4. Expanding cross-border yuan clearing and settlement
China’s cross-border yuan payment and settlement system is gaining traction. The annual transaction value in 2025 had almost quadrupled in 10 years to 180.2 trillion yuan (US$26.9 trillion or RM101.0 trillion), based on data compiled by Bloomberg.
The expanding Cross-Border Interbank Payment System (CIPS) allows companies and financial institutions to transact more easily in yuan outside China, Standard Chartered’s Wu said.
“We could see efforts to further expand the CIPS’ usage for cross-border clearing and settlement, as well as the promotion of cross-border QR code payments, especially with Asean countries,” he said.
Uploaded by Tham Yek Lee