

This article first appeared in Capital, The Edge Malaysia Weekly on October 12, 2026 - October 18, 2026
Negeri Sembilan
RHB RESEARCH (Oct 7): Negeri Sembilan is emerging as Malaysia’s next industrial growth frontier, supported by its proximity to Greater Kuala Lumpur, competitive industrial land prices, improving infrastructure and expanding semiconductor ecosystem. As the state accelerates efforts to attract high-value manufacturing and technology investments, we believe its growing investment pipeline could drive stronger economic activity, infrastructure development and private-sector opportunities.
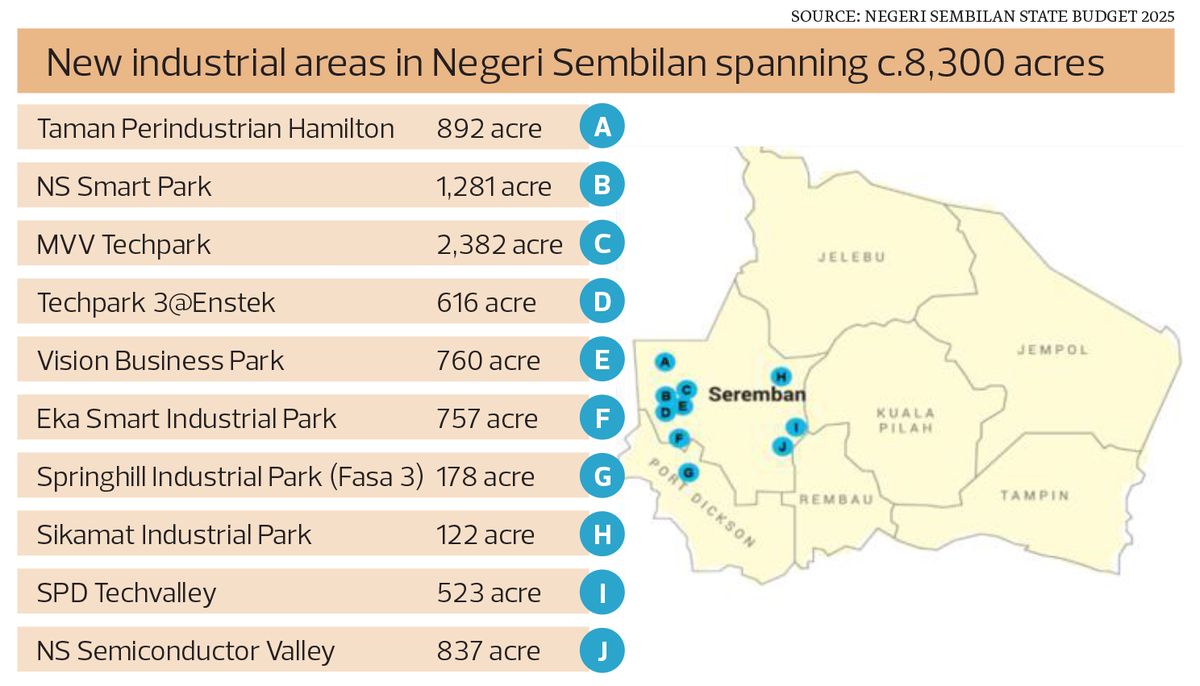
Manufacturing accounted for 37.4% of Negeri Sembilan’s GDP in 2025, second only to services at 53.3%. The state attracted RM3.4 billion of approved foreign investments in 1H2026, following RM4.4 billion in FY2025. Industrial expansion is supported by parks such as SPD Tech Valley and Negeri Sembilan Semiconductor Valley, within the Malaysia Vision Valley (MVV) 2.0 corridor spanning about 379,000 acres across Seremban and Port Dickson.
Property developers are also expanding their presence. Eco World Development Group Bhd (KL:ECOWLD) acquired 1,195 acres in Port Dickson in September 2025 for Eco Business Park 7 (EBP7), jointly developed with SD Guthrie Bhd (KL:SDG) and NS Corp. Matrix Concepts Holdings Bhd (KL:MATRIX) is developing the 2,382-acre MVV City with the state government, with an estimated GDV of RM15 billion, while IJM Land, the property arm of IJM Corp Bhd (KL:IJM), has 831 acres worth RM 7.7 billion.
The industrial and data centre influx is also creating spillover opportunities for builders. Gamuda Bhd (KL:GAMUDA) has secured about RM8 billion of contracts from hyperscale data centre developments, while Kerjaya Prospek Group Bhd (KL:KERJAYA) is benefiting from IJM Land’s IKON Residences. Inta Bina Group Bhd (KL:INTA) is constructing cluster factories at EBP7. Upcoming Bandar Enstek Hospital and Sunway Medical Centre Seremban Sentral could provide further opportunities for contractors with healthcare expertise.
We also flag Seremban Sentral, a RM2 billion transit-oriented development next to Seremban railway station, which is being developed by Sunway with Railway Assets Corporation. Sunway Construction Group Bhd (KL:SUNCON) could potentially secure construction works across its phases, particularly the medical centre and residential components, given its track record on Sunway-linked projects.
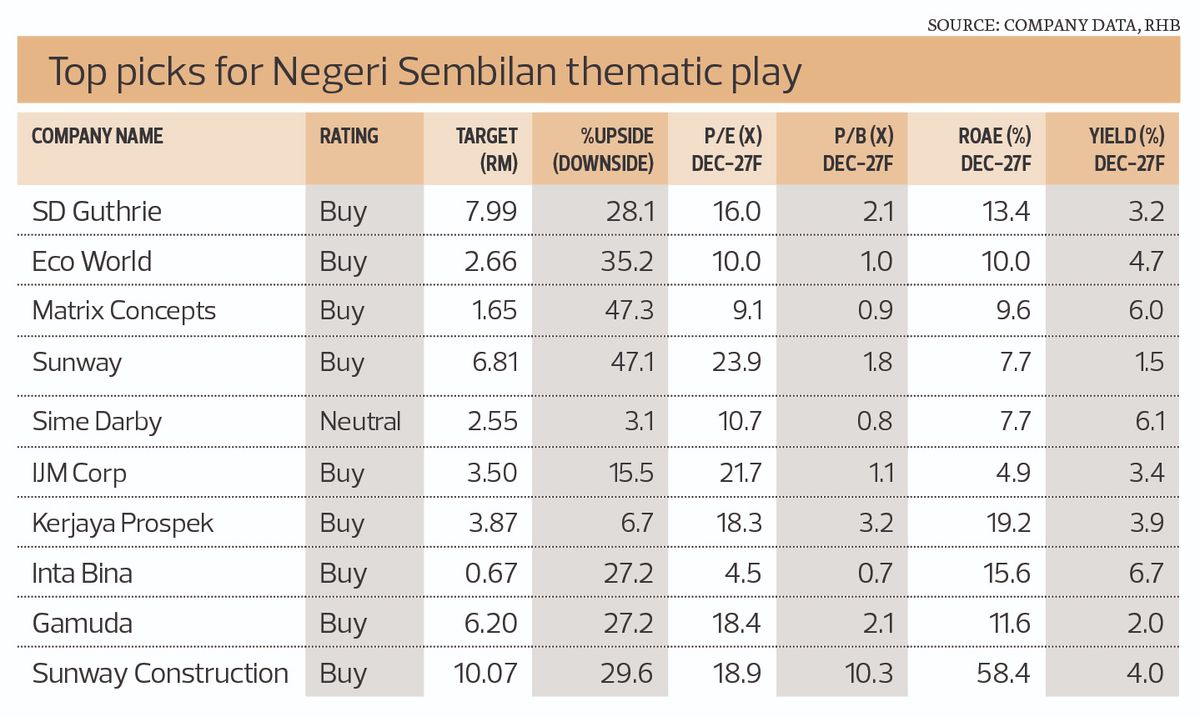
Our preferred Negeri Sembilan thematic plays are Eco World, IJM, Sunway, Matrix Concepts, Gamuda, Kerjaya Prospek, Inta Bina, Sime Darby, SD Guthrie and Sunway Construction.
Top Glove Corp Bhd
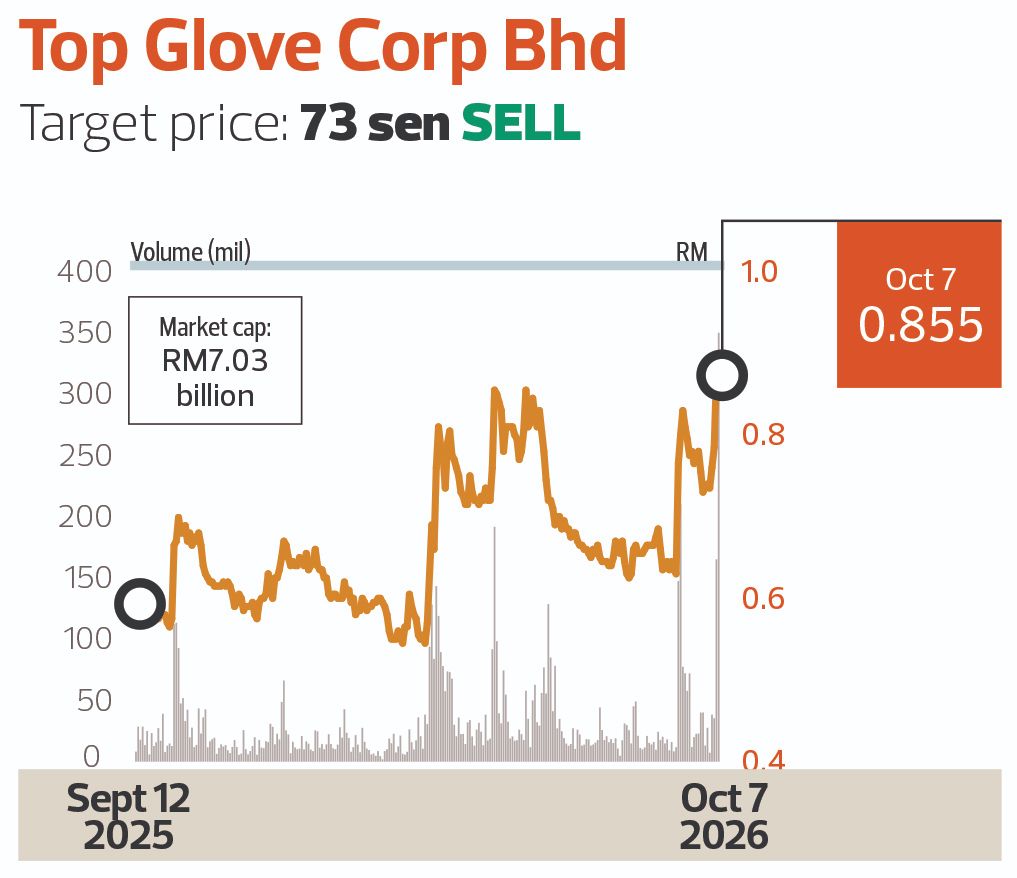
Target price: 73 sen SELL
Hong Leong Investment Bank (Oct 7): Top Glove reported FY26 core Patmi of RM419.9 million, up 11.8 times year on year (y-o-y) and above both our and consensus forecasts, driven by stronger-than-expected revenue and margins, alongside a RM39.5 million deferred tax credit. However, we expect earnings to weaken sequentially, as pricing power for further margin expansion fades, natural gas costs rise and deferred tax credits provide less support in 1QFY27.
We believe the brief period of elevated oil prices is insufficient to trigger a prolonged nitrile butadiene rubber (NBR) shortage, which we estimate would require at least six months to force weaker small- and mid-sized players out of the market and accelerate a supply-demand rebalancing. Hence, structural oversupply remains a concern.
We downgrade Top Glove from a “hold”, despite raising our target price (TP) from 68 sen. We recommend selling into strength following the strong results, which benefited from a temporary average selling price uplift amid NBR shortages in March-May 2026. Our TP is based on an unchanged 22 times PER, in line with its three-year pre-Covid mean, applied to rolled-forward CY27 EPS of 3.6 sen.
Mi Technovation Bhd
Target price: RM7.67 OUTPERFORM
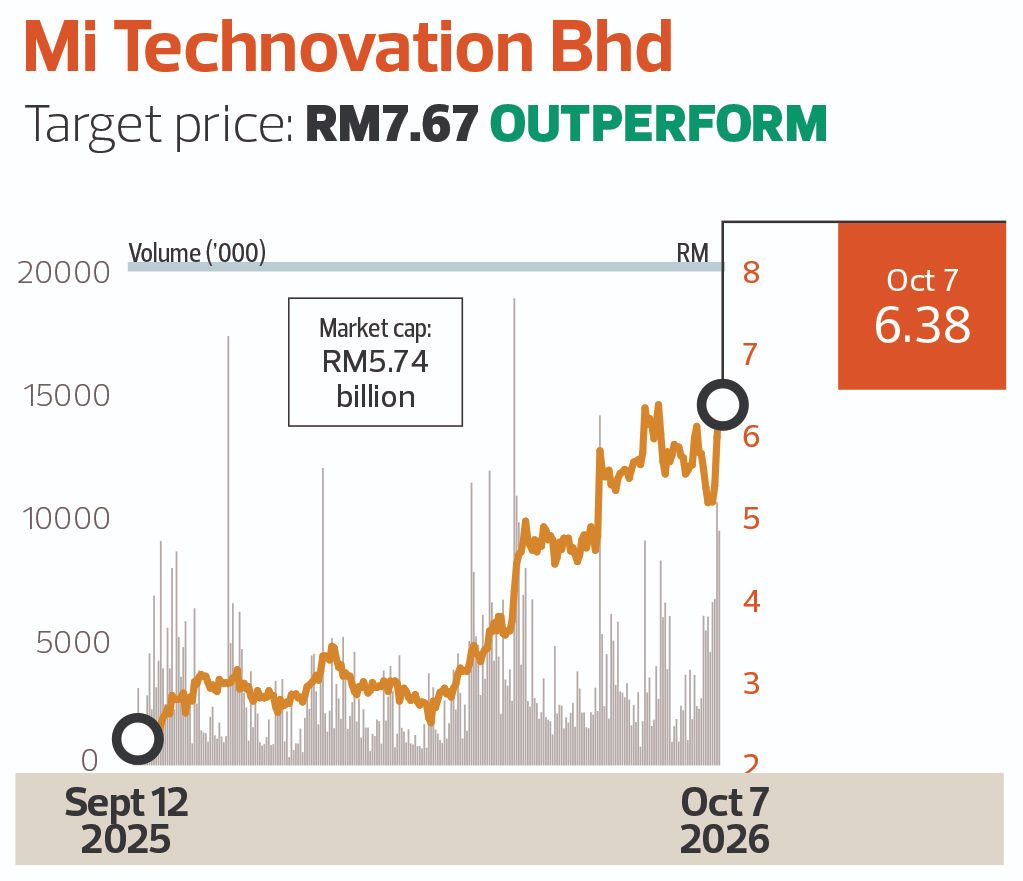
Public Investment Bank (Oct 6): Mi Technovation’s subsidiary, Mi Material Holding Ltd, released its preliminary prospectus on Oct 5, alongside robust 3QFY26 sales guidance. Based on the indicative IPO price of S$1.80/share, Mi Material would command a market cap of S$891 million (RM2.8 billion), above our earlier RM1.8 billion-RM2.2 billion estimate. This implies FY26-FY27F PER multiples of 17 to 21 times based on our earnings projections.
The IPO aims to raise S$168.2 million through offering up to 77.5 million shares, comprising 51.5 million new shares and 26 million vendor shares. Proceeds will fund expansion of solder ball production lines from 19 currently to 33 by 2029, lifting installed annual capacity from 6.6 billion-8.9 billion units to 11.3 billion-15.2 billion units. Mi Technovation’s retained 73.7% stake would be worth an implied S$657 million upon listing, scheduled for Oct 28.
We maintain our “outperform” call, with a lower TP of RM7.67 following the share dividend distribution, which increased the share base to 898 million from 885 million. Our TP is based on 35 times FY27F EPS.
Empire Premium Food Bhd
Target price: RM1.36 BUY
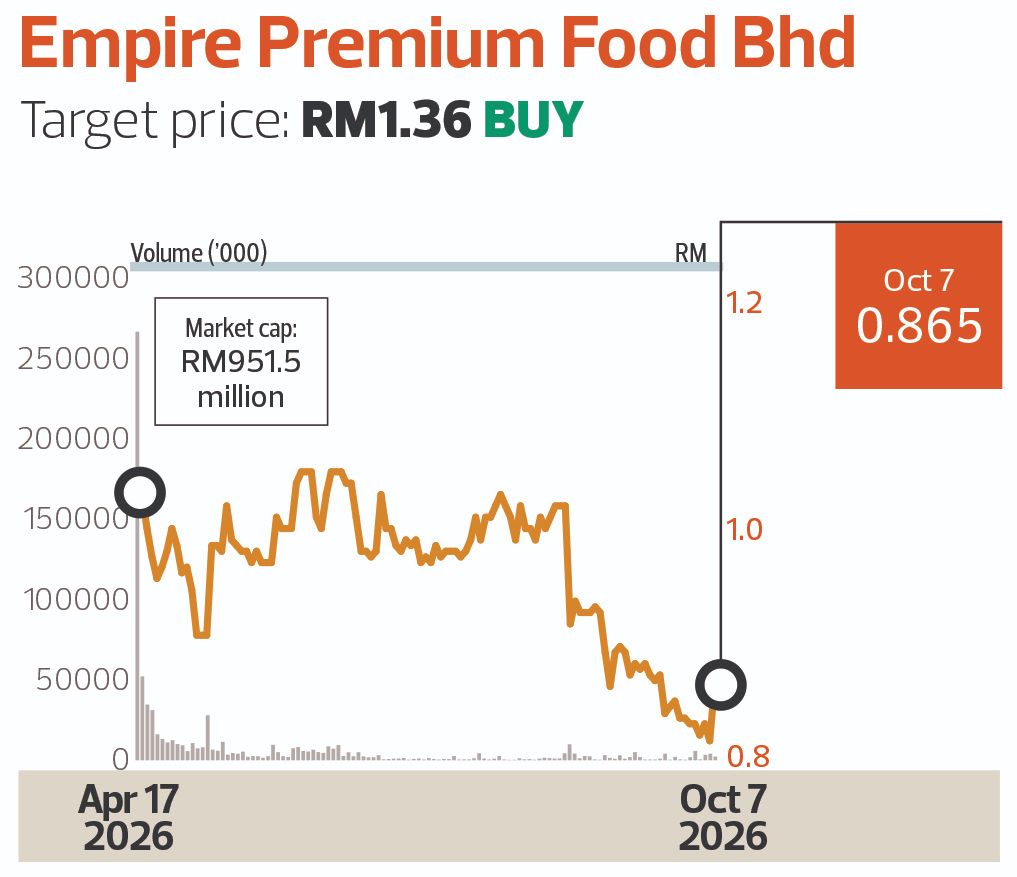
CIMB Securities (Oct 6): Empire Premium Food (Empire Sushi) continues to see healthy sales momentum in 2QFY27, supported by new stores and product launches. We expect same-store sales growth to remain positive, while higher operating leverage and a more profitable product mix should support margins despite cost pressures. Seasonal products typically carry higher margins, while its fast moving consumer goods products are also gaining traction. Empire Sushi targets 18 new stores annually in FY27-FY29, slightly below our forecast of 20. We see ample expansion runway across malls, airports and train stations, as well as significant geographic whitespace in east Malaysia, with just six stores in Sarawak and one in Sabah, versus 155 nationwide.
Budget 2027 could further support consumer spending through targeted assistance and cost-of-living measures. A potential minimum wage hike from RM1,700 per month may exert modest margin pressure, although the impact should be limited as most of its circa 1,500 employees already earn above RM2,000.
We maintain our “buy” call and FY26-FY28F EPS forecasts, with TP unchanged at RM1.36, based on 23 times CY27F PER. At 83 sen, the stock trades at 14.1 times CY27F PER, which we view as undemanding against its 23.9% FY24-FY29F core EPS CAGR.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.