

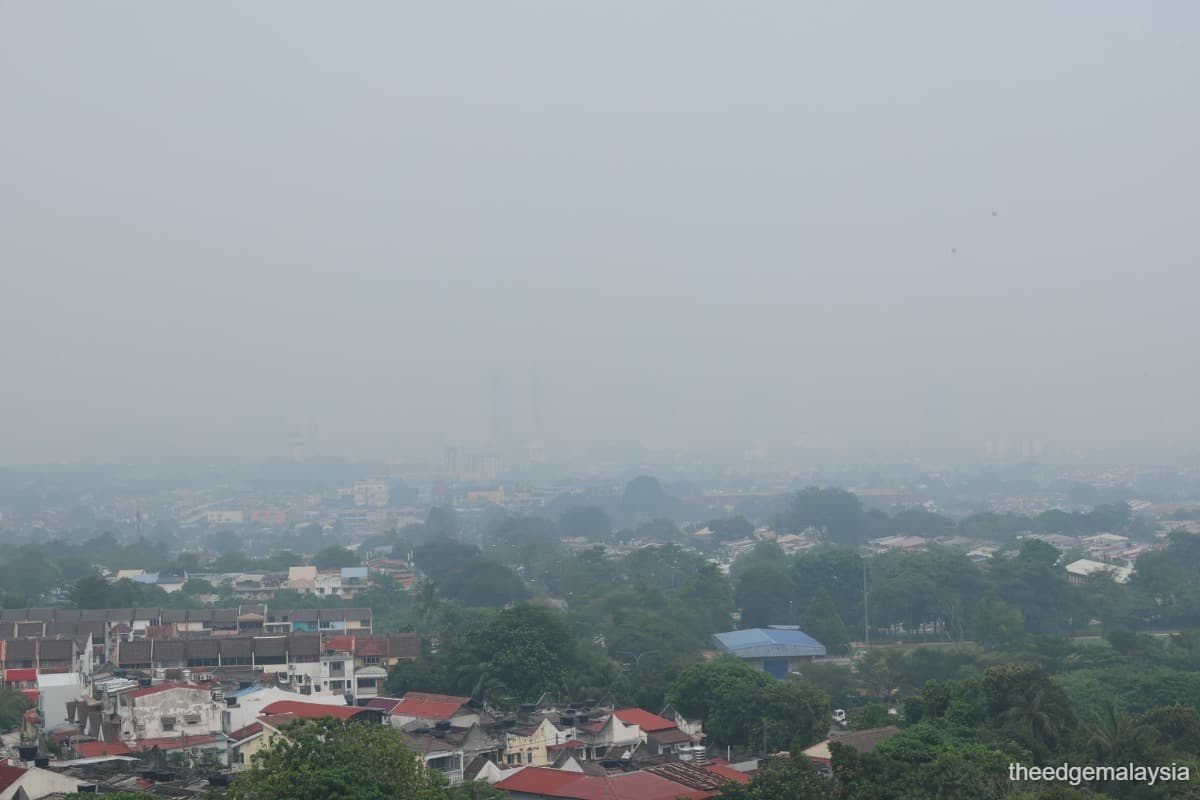
KUALA LUMPUR (Oct 13): Malaysian insurers, grappling with backlash from surging premiums, may be facing margin squeeze with prolonged transboundary haze, an analyst warned.
More people seeking treatment for haze-related respiratory illnesses could push medical claims higher, coming at a time when insurers are already dealing with pricier medicine and medical equipment from logistics-related disruption, MBSB Research flagged in a sector report.
However, the rising cost of living makes it harder to pass the additional expense to policyholders who may drop out of coverage, risking the ire of regulators, the research house said.
The pressure comes as haze originating from severe forest and peatland fires in Indonesia continues to blanket the skies over several Malaysian cities. At 10am on Tuesday, Johor Bahru, Kuching and Kuala Lumpur all reported unhealthy air quality readings.
Bank Negara Malaysia, which regulates the insurance sector, has already moved to limit the increases on medical insurance premiums to 10% amid public outrage and the cap is set to expire next year.
While insurers could then raise premiums more sharply to recover their costs, any steep hike could prompt customers to cancel their policies and invite further regulatory intervention, particularly as households continue to struggle with rising living costs, MBSB Research said.
Insurers may therefore have to settle for smaller premium increases and accept thinner profit margins, the research house said.
Insurance policies with recurring medical premiums face a greater risk of regulatory intervention while employer-provided medical coverage is less exposed because its pricing can be negotiated annually, the house noted.
Among the insurers under its coverage, MBSB Research identified Allianz Malaysia Bhd (KL:ALLIANZ) as the most vulnerable, given its greater reliance on medical insurance products with recurring premiums.
Syarikat Takaful Malaysia Keluarga Bhd (KL:TAKAFUL), meanwhile, is expected to be less affected as its family takaful business focuses more on products linked to financing while much of its medical coverage comes from employee benefits.
The house cut its earnings forecast for both and reduced its target price for Allianz by RM4.04 to RM22.73 and Takaful Malaysia by RM1.07 to RM3.44.
Still, the ongoing haze does not cloud the sector’s attractive valuations, dividend payouts and near-term growth prospects, MBSB Research said in maintaining a ‘buy’ call on both stocks. "Expect high top-line values but more moderate bottom-line growth," the house added.