

This article first appeared in The Edge Malaysia Weekly on October 12, 2026 - October 18, 2026
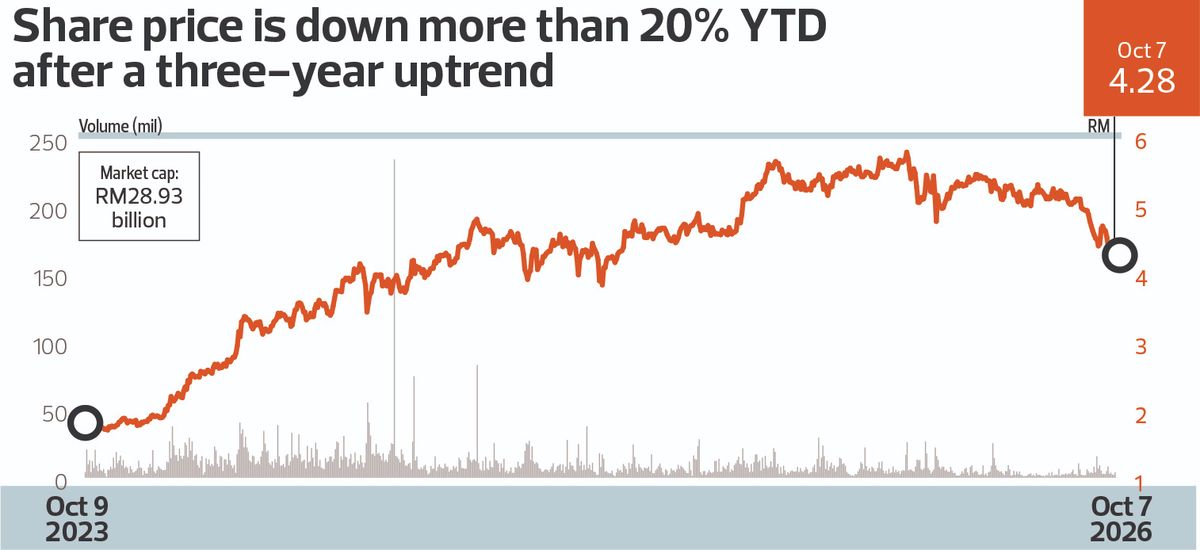
SINCE the beginning of the year, Sunway Bhd (KL:SUNWAY) shares have declined more than 20%. From a record high of RM5.98 in February this year, the stock has fallen by almost 30%, coming on the heels of Sunway’s failed bid earlier this year to take over rival IJM Corp Bhd (KL:IJM) for RM3.15 billion, a deal that valued IJM at RM11 billion.
In March, Sunway’s healthcare arm, Sunway Healthcare Holdings Bhd (KL:SUNMED), made a strong debut on the local bourse, touching a high of RM2.46 against its listing price of RM1.45 a share. The private hospital operator became a component stock of the FBM KLCI upon listing.
Meanwhile, Sunway Construction Group Bhd (KL:SUNCON) has continued its upward trajectory this year, gaining 35% year to date (YTD), although the stock remains 10.6% below its record high of RM8.40 recorded two months ago.
Much of the enthusiasm surrounding Sunway shares over the past three years was driven by the group’s high exposure to the construction of data centres (DCs), which now accounts for more than half of SunCon’s order book, as well as the listing of its healthcare arm.
Analysts and fund managers say the broader outlook for Sunway has not materially changed, although the group is now waiting for fresh catalysts to drive the next leg of its share price rerating.
Tradeview Capital Sdn Bhd CEO Ng Zhu Hann says it is crucial for Sunway to demonstrate successful execution of its major acquisitions, such as the purchase of MCL Land in Singapore. Improved earnings from these initiatives could support future valuation growth.
Last year, Sunway paid S$738.7 million (RM2.4 billion) to buy MCL Land from Hongkong Land Holdings, marking the conglomerate’s largest deal ever. MCL Land and its subsidiaries undertake development projects in Singapore and boast a portfolio of income-generating and development assets in Malaysia.
RHB Research property analyst Loong Kok Wen attributes Sunway’s share price weakness to pressure on the property sector amid the Middle East conflict and local political uncertainty ahead of the general election. “Not just Sunway, but other property stocks are also underperforming. Market attention has also shifted toward technology, solar, DC and MEP (mechanical, electrical and plumbing) value-chain companies.”
Although property demand has softened, Loong says property developers continue to be supported by ongoing sales and unbilled sales.
She says Sunway will continue to be supported by SunCon’s massive DC jobs and the expansion of SunMed. However, she stresses that following the SunMed listing, the group needs to demonstrate further robust initiatives to drive growth.
“After the failed takeover of IJM, I think Sunway should look at a big asset or landbank acquisitions. It has grown so big, so it needs to do something major to continue to support its valuation,” says Loong, who has the highest target price of RM6.81 for Sunway.
Meanwhile, a fund manager who declined to be named says the cooling sentiment and profit-taking in Sunway are understandable after the stock’s strong uptrend since 2023, which was fuelled by strong DC jobs and the healthcare listing exercise.
Having said that, he notes that Sunway remains favourably viewed over the long term because of its diversified exposure, with the healthcare business seen as a “stabiliser” due to its defensive nature.
He points out that Sunway has about RM8 billion to RM9 billion of unbilled property sales, against its estimated gross development value (GDV) that is about 10 times higher.
As at end-December 2025, the group had a remaining landbank of 2,375 acres with a GDV of nearly RM75 billion.
In the first half ended June 30, 2026 (1HFY2026), Sunway recorded new sales of RM2.32 billion, or about 55% of its full-year sales target of RM4.2 billion.
For SunCon, it had secured almost RM7 billion in new orders, already exceeding its initial full-year target of RM6 billion. Management has raised its FY2026 replenishment target from RM7 billion to RM9 billion on robust DC demand.
The outstanding order book stood at RM10.5 billion as at end-June, with a RM14.2 billion tender book. Notably, SunCon, which has zero gearing, is trading at a decent trailing 12-month dividend yield of 8.6%.
Diversified structure offers defensive nature
Generally, diversified conglomerates often trade at a discount compared with “pure-play” companies that focus on just a single business or sector. Investors may choose SunCon or SunMed directly for more focused exposure, although Sunway offers group-level diversification and relative stability.
However, Ng says the conglomerate discount is not viewed as the main issue because Sunway has already pursued value-unlocking exercises, including the SunMed spin-off.
He notes that Sunway’s diversified structure does offer more defensiveness over the long term.
“I always believe that while a diversified conglomerate may have a holding discount, they are more defensive in the long run. For Sunway, I think we can give it a little bit more time for the share price to stabilise first. Under the current situation and macroeconomic environment, there is no need to rush into buying the stock at this juncture,” he opines.
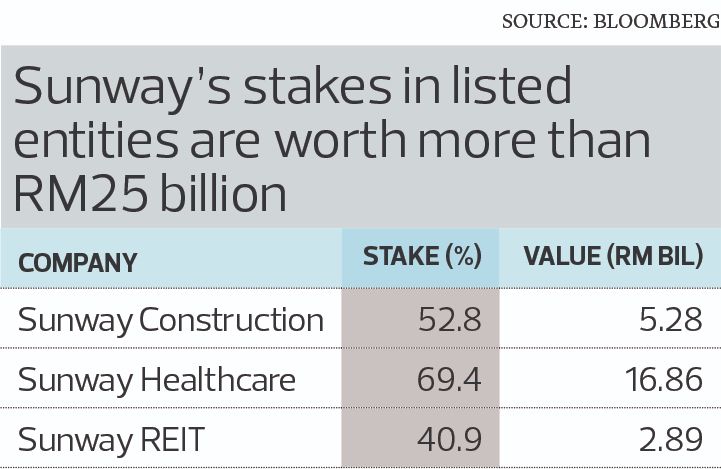
Sunway’s stakes in listed entities, namely SunCon, SunMed and Sunway Real Estate Investment Trust (KL:SUNREIT), are already valued at about RM25.03 billion, compared with the group’s current market capitalisation of about RM28.93 billion, based on last Wednesday’s closing price of RM4.28.
Sunway’s core property development is valued at about RM13 billion, according to TA Securities. In other words, the total value of Sunway could be worth close to RM40 billion, or about RM5.92 per share, if other business segments were included.
That valuation is higher than the target prices by most analysts. The consensus target price for the stock is RM5.70 – based on seven “buy” calls and another seven “hold” recommendations, implying an upside potential of 33.2%.
Sunway also has interests in the building materials, quarrying, and trading and manufacturing businesses.
In FY2025, construction was the largest contributor to the group’s profit before tax at 29%, while property investment and property development accounted for 22% and 21%, respectively. The balance of 28% came from healthcare, building materials, quarrying, trading and manufacturing, and others.
In an Aug 28 note, TA Securities expects Sunway’s 2HFY2026 earnings to improve, underpinned by firmer contribution from investment properties and continued earnings ramp-up by SunMed.
“SunMed remains a key growth driver, supported by higher patient volume, international patient census and continued ramp-up of Sunway Medical Centre Damansara and Sunway Medical Centre Ipoh.”
The fund manager says the group’s gearing will be closely monitored following its aggressive expansion, which could pressure capital requirements and leverage, despite gearing being lower than the previous year.
Sunway’s net gearing stands at about 0.3 times compared with 0.48 times as at end-December 2025. As at end-June 2026, its borrowings totalled RM16.41 billion against RM8.64 billion in cash and bank balances, giving it a net debt position of RM7.77 billion.
At the same time, the fund manager notes that it remains to be seen if the DC demand and construction activity will continue to be exceptionally strong.
Hong Leong Investment Bank Research is of the view that Sunway remains a “compelling proxy” to domestic growth, which is entering a new phase driven by rising foreign direct investments and structural reforms, given the group’s footprint expansion across key sectors.
Net profit for 1HFY2026 came in at a whopping RM9.73 billion from RM463.51 million a year earlier, mainly due to a RM9.1 billion one-off gain arising from the remeasurement of Sunway’s investment in SunMed to fair value, following the healthcare group’s listing and its reclassification as a subsidiary.
The consensus net adjusted earnings forecast for Sunway is expected to normalise to RM1.25 billion for FY2026, before expanding to RM1.39 billion for FY2027, according to Bloomberg data. In FY2025, the group posted a net profit of RM1.3 billion compared with RM1.15 billion in FY2024.
The Employee Provident Fund’s stake in Sunway has increased to 11.9% compared with 11.66% three months ago. Founder and chairman Tan Sri Jeffrey Cheah holds 60.31% of Sunway via Sungei Way Corp Sdn Bhd, Jef-San Enterprise Sdn Bhd and Active Equity Sdn Bhd.
Other shareholders of Sunway include UBS AG (4.37%), Public Mutual Bhd (2.74%) and Vanguard Group Inc (2.17%).
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.