

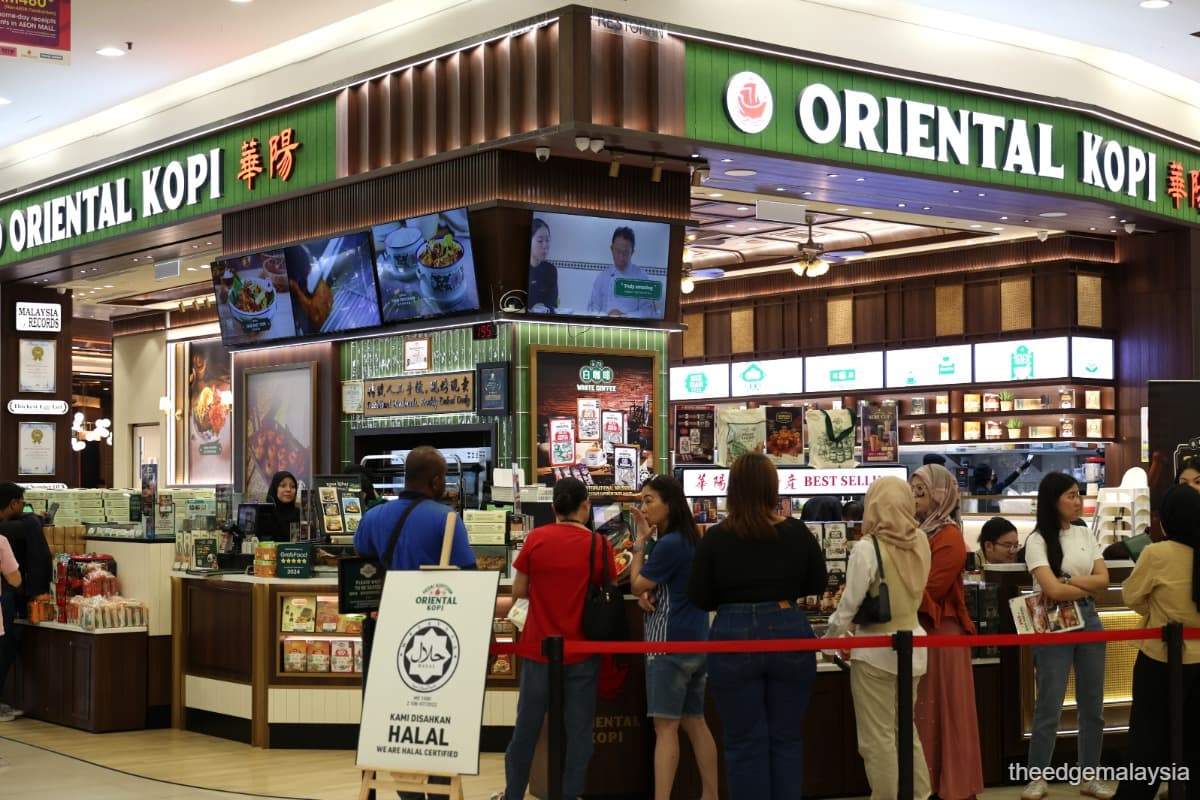
KUALA LUMPUR (Oct 9): Oriental Kopi Holdings Bhd (KL:KOPI) could see its share price rise by more than 50%, according to CGS International Securities (CGSI), which expects the cafe operator's expansion and growing packaged food business to drive stronger earnings over the next few years.
The research house initiated coverage on Oriental Kopi with an "add" call and a target price of RM1.37, implying a potential upside of 53.5% from its reference share price of 89 sen as at Oct 7.
CGSI believes the stock's current valuation does not fully reflect its growth prospects, particularly as the group expands its café network, benefits from higher tourist spending and improves profitability through a planned central kitchen.
"We view Kopi's business model favourably, given its halal-certified modern 'kopitiam' format, strong and growing brand presence, and integrated FMCG business," CGSI said in a note on Thursday.
The research house noted that Oriental Kopi was trading at about 14 times its projected earnings for the financial year ending September 2028 (FY2028), well below its historical average of 30.8 times.
CGSI expects the group's revenue to grow by an average of 31.1% annually between FY2025 and FY2028, supported by 23 additional outlets, higher sales at existing cafes and expansion of its packaged food business.
Core net profit is projected to grow at an average annual rate of 27.8% over the same period, reaching RM126.9 million in FY2028 from RM64.2 million in FY2025.
Oriental Kopi operated 31 cafes in Malaysia and three joint-venture outlets in Singapore as at July 2026, with expansion plans targeting high-traffic locations including Genting Highlands and Merdeka 118.
CGSI also expects the group to benefit from Malaysia's tourism recovery, noting that international visitors typically spend about twice as much as local customers, who spend an average of RM30 to RM35 per visit.
Beyond its cafes, the research house sees the group's fast-moving consumer goods (FMCG) business, which includes packaged coffee, tea, pastries and instant noodles, as another source of growth.
Revenue from this segment is expected to increase to RM64 million by FY2028 from RM29 million in FY2025.
The packaged food business also offers higher profit margins of between 40% and 50%, compared with about 20% to 24% for cafe operations, potentially improving the group's overall profitability as sales increase.
Meanwhile, CGSI expects Oriental Kopi's planned central kitchen, targeted to begin operations by end-2027 or early FY2028, to improve efficiency by reducing manpower requirements and allowing outlets to serve more customers.
The facility could lift the group's gross profit margin by about two percentage points to 24% in FY2028, it said.
However, CGSI acknowledged that higher raw material costs, labour expenses and weaker sales growth at existing outlets had weighed on profitability in FY2026.
It expects margins to recover as new outlets mature, input costs stabilise and pre-opening expenses ease.
"Faster-than-expected outlet expansion, stronger SSSG, and higher tourism-driven demand are key potential re-rating catalysts," the research house said.
Key downside risks include intense competition in the food and beverage industry, labour shortages, rising operating costs and potential food safety incidents.
CGSI's RM1.37 target price is the highest among eight analysts tracked by Bloomberg, whose average 12-month target price stands at RM1.21.
Of the eight analysts, five have “buy”-equivalent recommendations and three have “hold” calls, with none recommending a sell.