

KUALA LUMPUR (Oct 7): Glove stocks were among Wednesday's most actively traded counters, led by Top Glove Corp Bhd (KL:TOPGLOV), though analysts cautioned the world's largest glove maker's strong finish to its financial year ended Aug 31, 2026 (FY2026) may not signal a sustained recovery.
Analysts cited persistent oversupply, rising natural gas tariffs, and potential wage hikes as reasons for their pessimism, noting these factors continue to cloud glove maker's outlook.
Top Glove rose as much as seven sen at 92 sen on Wednesday early trade from its opening price of 88 sen, after reporting a strong 4QFY2026 results the day prior.
At the time of writing, Top Glove was the most active stock on early trade on Bursa Malaysia, with more than 162.52 million shares changing hands.
Supermax Corp Bhd (KL:SUPERMX) rose as much as five sen to 51 sen, with about 52 million shares done.
However, Kossan Rubber Industries Bhd (KL:KOSSAN) rose to a high of RM1.30 before retracing its gains to RM1.22, down three sen or 2.4%, with just over 12 million shares changing hands.
Top Glove's earnings likely topped out
While 4QFY2026 Top Glove's core net profit leaped sharply on higher average selling prices (ASPs) and sales volumes, both PublicInvest Research and CIMB Securities maintained their bearish ratings on the stock, citing ongoing structural challenges and compressed long-term return visibility.
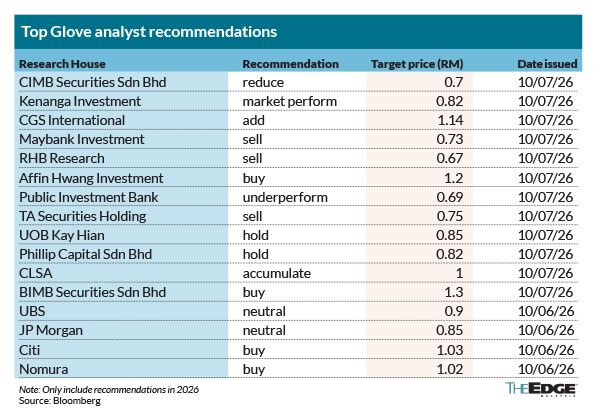
PublicInvest Research retained its "underperform" recommendation with a revised target price (TP) of 69 sen from 59 sen, while CIMB Securities maintained its "reduce" call with a TP of 70 sen, an increase from 63 sen.
According to Bloomberg data, market sentiment on Top Glove is mixed, with 16 research houses covering the stock. Of these, four recommended a "buy" call, three issued a "sell", two advised "hold", two rated it as "neutral", and one each recommended "add", "accumulate", "market perform", "underperform", and "reduce".
Top Glove ended FY2026 on a robust note as 4QFY2026 net profit surged to RM157.6 million. Revenue for the quarter rose 39.7% year-on-year to RM1.25 billion, supported by higher sales volumes and stronger blended ASPs. The top-line expansion was aided by cost pass-through measures implemented since late April to offset rising raw material costs.
For the full year, net profit reached RM307.96 million, beating market expectations.
Sequentially, sales volume slipped 7.0% quarter-on-quarter in 4QFY2026 due to softer demand for latex gloves, with powdered and powder-free glove volumes contracting 18.7% and 7.0%, respectively. Order volumes from Middle Eastern markets also dropped 42% y-o-y due to ongoing geopolitical tensions.
"As ASPs have already normalised from the June 2026 peaks of US$27 to US$29 per 1,000 pieces, we believe earnings have likely topped out and will gradually trend down towards normalised levels over the coming quarters," CIMB Securities noted.
The research house added that near-term pricing could stay temporarily elevated following Top Glove's US$2 to US$2.50 per 1,000 pieces blended ASP hike in September 2026, but long-term upside remains capped by global oversupply, with industry capacity exceeding 500 billion pieces against an estimated demand of 400 billion pieces.
"Over the longer term, industry prospects remain clouded by persistent oversupply with global capacity exceeding 500 billion pieces against the estimated demand of approximately 400 billion pieces for 2026-2027F, and intense competition from Chinese manufacturers," CIMB Securities added.
Margins are also set to come under pressure from cost headwinds. A 30% to 39% increase in natural gas tariffs effective October 2026 is projected to raise costs per carton by 2% to 3%. Furthermore, a potential minimum wage hike to RM1,900 per month could further add 1% to production costs.
"Should the minimum wage be raised by 12% to RM1,900/month in 2027 from the current RM1,700/month, we estimate a potential 11%/4% impact on our FY2027/FY2028F earnings estimates, respectively," CIMB Securities cautioned.
That said, stronger cash flow generation enabled Top Glove to turn around its balance sheet to a net cash position of RM141 million at the end of FY2026, reversing a net debt position of RM267 million a year prior, noted PublicInvest.
The house raised its FY27F/FY28 earnings forecasts by 78.6%/64.6% and introduced FY29 estimates, incorporating higher ASP assumptions alongside anticipated energy and labour cost increases.
Its raised TP of 69 sen is based on a price to book multiple of 1.1 times applied to adjusted 2027 book value per share.
"The higher multiple recognises the earnings recovery and stronger balance sheet. However, further rerating requires evidence that improved utilisation and pricing can sustain higher returns beyond the current oversupply conditions," PublicInvest Research said.