

This article first appeared in Capital, The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Technology
NEUTRAL
MBSB INVESTMENT BANK (SEPT 29): The global semiconductor sales for the month of July grew by 135.1% year on year (y-o-y) and 6.4% month on month (m-o-m) to US$146.8 billion. This represents 17 months of sequential growth, indicating that the 2026 sales projection of US$11 billion could be surpassed.
Demand continues to be underpinned by AI infrastructure and data centre (DC) buildouts.
According to International Data Corp, 2QCY26 global smartphone shipments declined by 6.7% y-o-y to 277.5 million units. Chinese brands such as Xiaomi, OPPO and Vivo posted declines in sales. On the flip side, Samsung and Apple managed to increase shipments by 8.1% y-o-y and 14.9% y-o-y respectively.
Apple’s 2QCY26 performance was supported by the iPhone 17 and stable pricing. The launch of iPhone 18 and Duo could help support Apple’s position. Based on newswires, demand for iPhone Duo has been encouraging, though this could be partially tempered by the price tag and constrained supply.
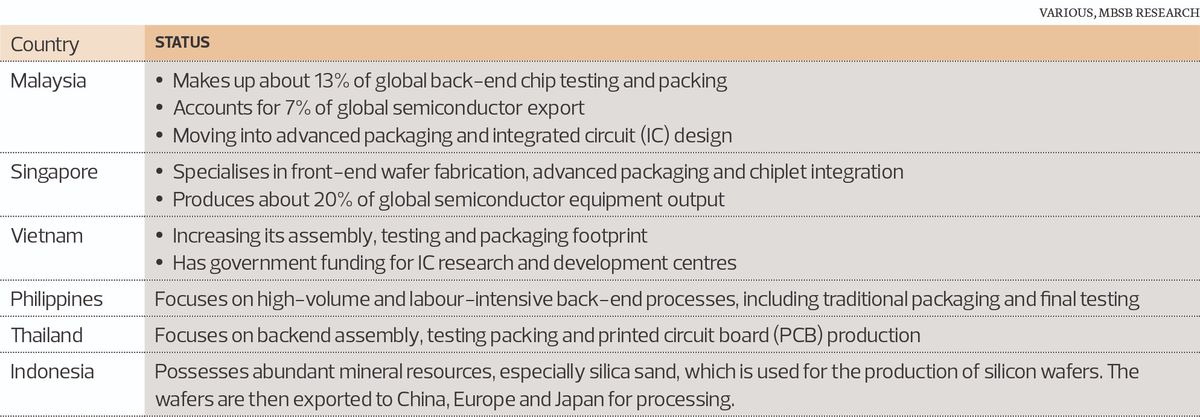
Given the explosive growth in the AI and data centre sphere, there is a severe structural talent shortage. For Malaysia, the issue is further compounded by the government’s plan to move up from back-end assembly and testing into integrated circuit design, advanced packaging and innovation-led manufacturing.
According to newswires, the local industry needs around 50,000 engineers to meet current demand while there are only 5,000 engineering graduates annually. However, the National Semiconductor Strategy targets to train 60,000 engineers by 2030. Nonetheless, we understand that talent shortage has currently limited the potential earnings upside.
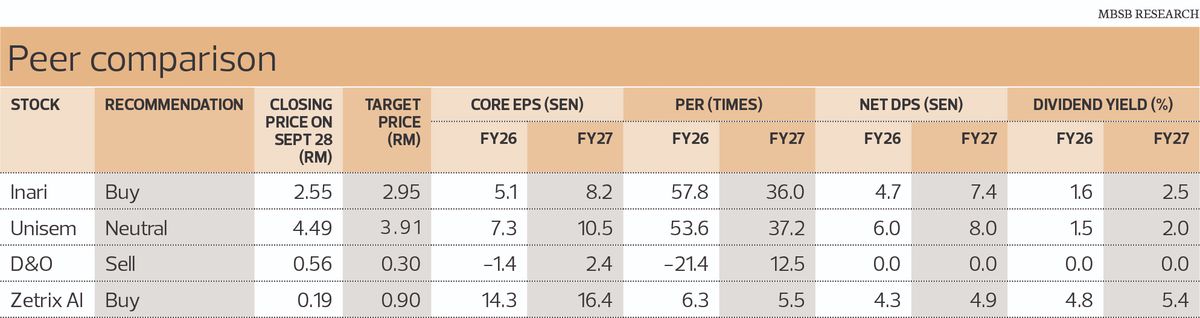
On a year-to-date basis, share price performances of local outsourced semiconductor assembly and test companies have increased by between 41% and 53%. Note that among our coverage, only D&O Green Technologies Bhd’s (KL:D&O) share price has contracted by 28% YTD, given the challenging outlook. Premised on this, we gather that the current PER valuations of between 35 times and 42 times have surpassed the five-year mean. This indicates that the market has largely priced in the potential rebound in earnings.
Future earnings growth could potentially be capped by the shortage of talent. Should there be any let-up in 2HCY26 earnings growth, we view that there could be some pullback in share price performances. Inari Amertron Bhd (KL:INARI) remains as our top pick for the sector.
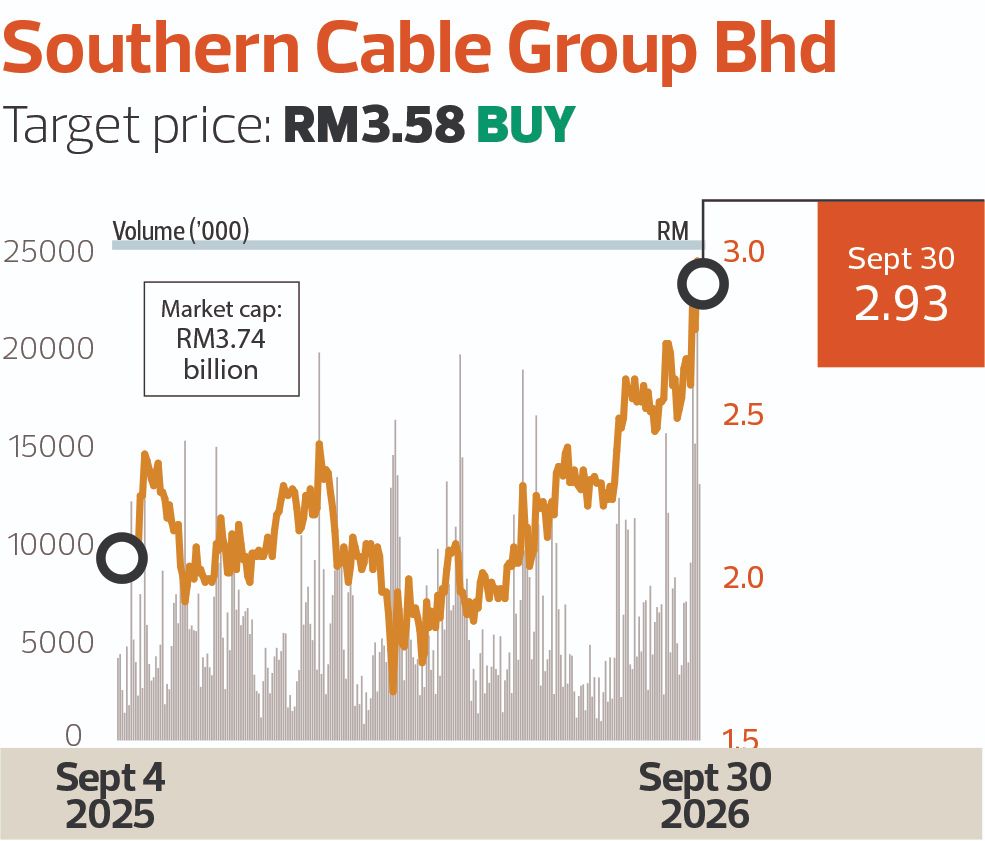
Southern Cable Group Bhd
Target price: RM3.58 BUY
HONG LEONG INVESTMENT BANK RESEARCH (SEPT 29): We raise Southern Cable Group Bhd’s (KL:SCGBHD) FY26-FY28 earnings by 8%-11% to reflect a stronger-than-anticipated power infrastructure cycle, supported by recent mechanical and electrical contractor meetings and Tenaga Nasional Bhd’s (KL:TENAGA) latest earnings call. Revenue could reach a record RM600 million in 3Q26 as DC and 132kV orders enter peak delivery, while a higher purchase order mix should cushion plastic cost pressure and allow stronger sales to flow through to earnings.
We expect SCG to surpass its record 2Q26 performance in 3Q26 as circa RM200 million of newly secured DC orders and 132kV cable orders won in 2Q26 enter peak delivery. These orders have fully booked out its capacity for FY26, with 3Q26 revenue potentially reaching RM600 million, in our view.
Looking into FY27, rising DC, grid and solar activity should sustain demand, with SCG’s capacity expansion well timed to capture the pickup and new 132kV variants, broadening its DC offering. Our FY27 revenue growth projection of 17% primarily reflects higher capacity, leaving stronger 132kV take-up and larger DC order contribution as potential sources of further upgrades.
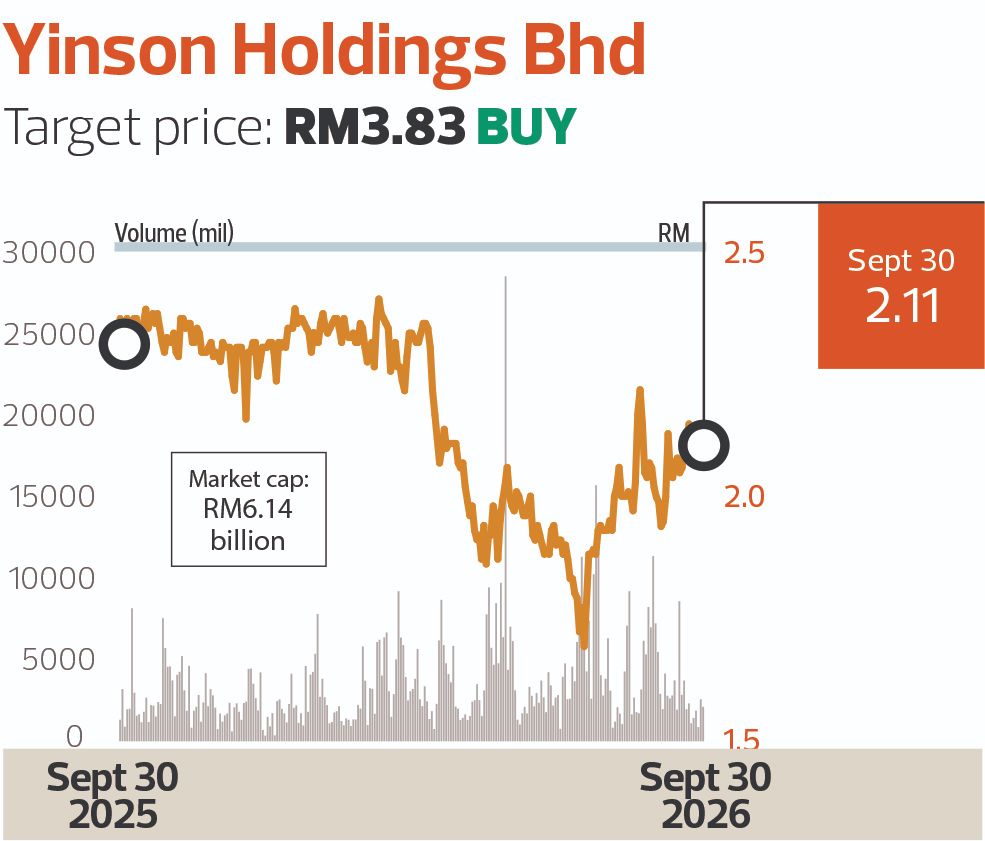
Yinson Holdings Bhd
Target price: RM3.83 BUY
RHB RESEARCH (SEPT 30): Yinson Holdings Bhd’s (KL:YINSON) first-half FY27 (ended January) core net profit of RM263 million (+43% y-o-y) accounts for 30% and 40% of our and consensus FY27 forecasts. We deem the results as in line — earnings are typically back-end loaded, supported by higher recurring charter contributions, annual charter escalations and potential project wins in the later part of the year.
We remain constructive on Yinson’s medium-term outlook, underpinned by a growing base of recurring FPSO (floating, production, storage and offloading) charter income and a robust US$18.9 billion order book providing long-term earnings visibility through 2050. Underlying earnings should strengthen on the back of a full-year contribution from Agogo in FY27, while FSO Lac Da Vang remains on track for first oil in 4QFY27. This should provide an incremental earnings contribution towards the end of FY27 and a more meaningful uplift from FY28 onwards. Meanwhile, the group’s balance sheet risk continues to improve following Agogo’s transition to non-recourse financing and stronger operating cash flow generation. With results in line, we keep our earnings forecasts unchanged.
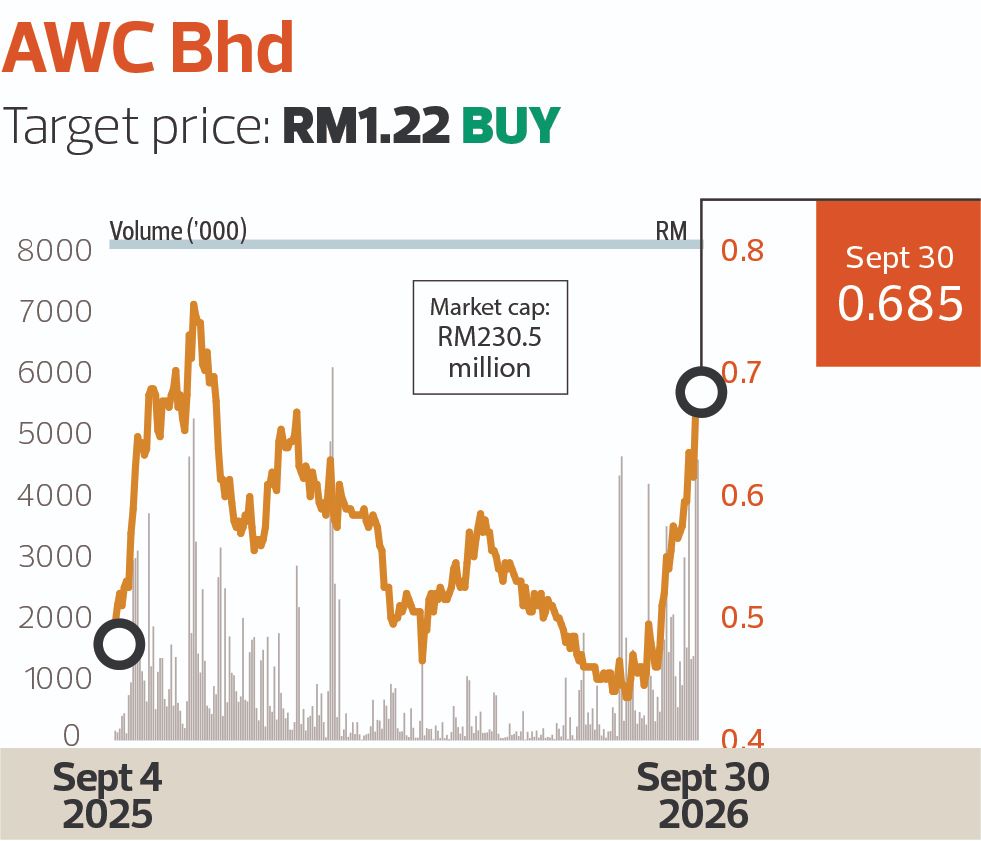
AWC Bhd
Target price: RM1.22 BUY
APEX SECURITIES (SEPT 29): AWC Bhd (KL:AWC) via its indirect wholly-owned subsidiary Stream Industries Sdn Bhd (STREAM) has signed two agreements with Gujarat International Finance Tec-City Co Ltd to connect upcoming developments in GIFT City, Gandhinagar, to an automated waste collection system network. The Domestic Tariff Area contract is worth INR19.82 crore (RM8.4 million inclusive of GST), while the Special Economic Zone contract is worth INR11.03 crore (RM4.7 million, zero-rated for GST). Both contracts run for 36 months from the notice to commence. STREAM intends to novate both agreements to a newly incorporated Indian entity once established.
We maintain our “buy” on AWC with an unchanged SOP target price of RM1.22 (fully diluted). We value the engineering segment at 15 times, environment at 13 times, and facilities and rail at seven times each, all on FY28F earnings.
We like AWC for its two independent entry points into the data centre theme via engineering and facilities, early traction on the India smart-city pivot, predictable cash flows from long-term concessions, and a net cash balance sheet every year since its 2003 listing.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.