

KUALA LUMPUR (Oct 2): IOI Properties Group Bhd's (KL:IOIPG) second attempt to acquire Shenton House is drawing less analyst concern now that the group has a clearer capital-recycling path through its Malaysian REIT and a potential Singapore REIT.
"We are less cautious on Shenton House than in 2024, but not because leverage is lower."
"What has changed is IOIPG's ability to recycle capital from its growing investment-property portfolio," said TA Securities in a note on Friday.
This marks IOI Properties' second attempt at Shenton House, after its board declined a proposed collaboration with group CEO and major shareholder Datuk Lee Yeow Seng in 2024, citing sizeable Singapore exposure and ongoing capital commitments.
IOI Properties, on Thursday, proposed to acquire 100% of Shenton 101 Pte Ltd, which owns Shenton House at 3 Shenton Way, Singapore, from Lee.
Shenton House will be redeveloped into a 35-storey mixed-use development comprising 12 floors of Grade-A offices, retail/F&B space and a 165-key luxury hotel, with total proposed net lettable area (NLA) of approximately 393,000 sq ft.
Construction is targeted to commence in 1HCY2027 and complete by end-CY2031.
Redevelopment cost is estimated at S$973.7 million (RM3.12 billion), including construction and finance costs, Land Betterment Charge and lease renewal premium.
Together with Shenton 101's S$376 million existing debt and S$217 million owed to Lee, the overall financial commitment is approximately S$1.57 billion, noted TA Securities.
The house said, including the purchase of Asia Square Tower 2 (AST 2) earlier this year, it forecast IOI Properties' FY2027 net gearing at 1.16 times, materially higher than when Shenton House was first considered in 2024.
Nonetheless, TA Securities is less cautious than in 2024 despite higher gearing today, because IOI Properties' capital-recycling path has changed.
It noted that IOI Central Boulevard Towers (ICBT) has matured, with committed occupancy exceeding 95% and the asset generating sufficient cash flow to service its debt.
"More importantly, the proposed Malaysia REIT has received Bursa Securities' approval and provides a near-term source of capital.
IOI Properties will retain 60% of the Malaysia REIT, while proceeds are intended mainly for debt repayment and investment," said the research firm.
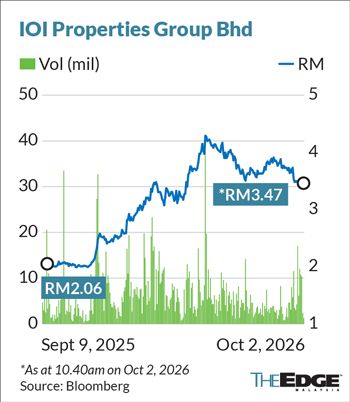
TA Securities kept its 'buy' recommendation on the stock, with a target price of RM4.70, implying a 37% upside to its current price of RM3.42.
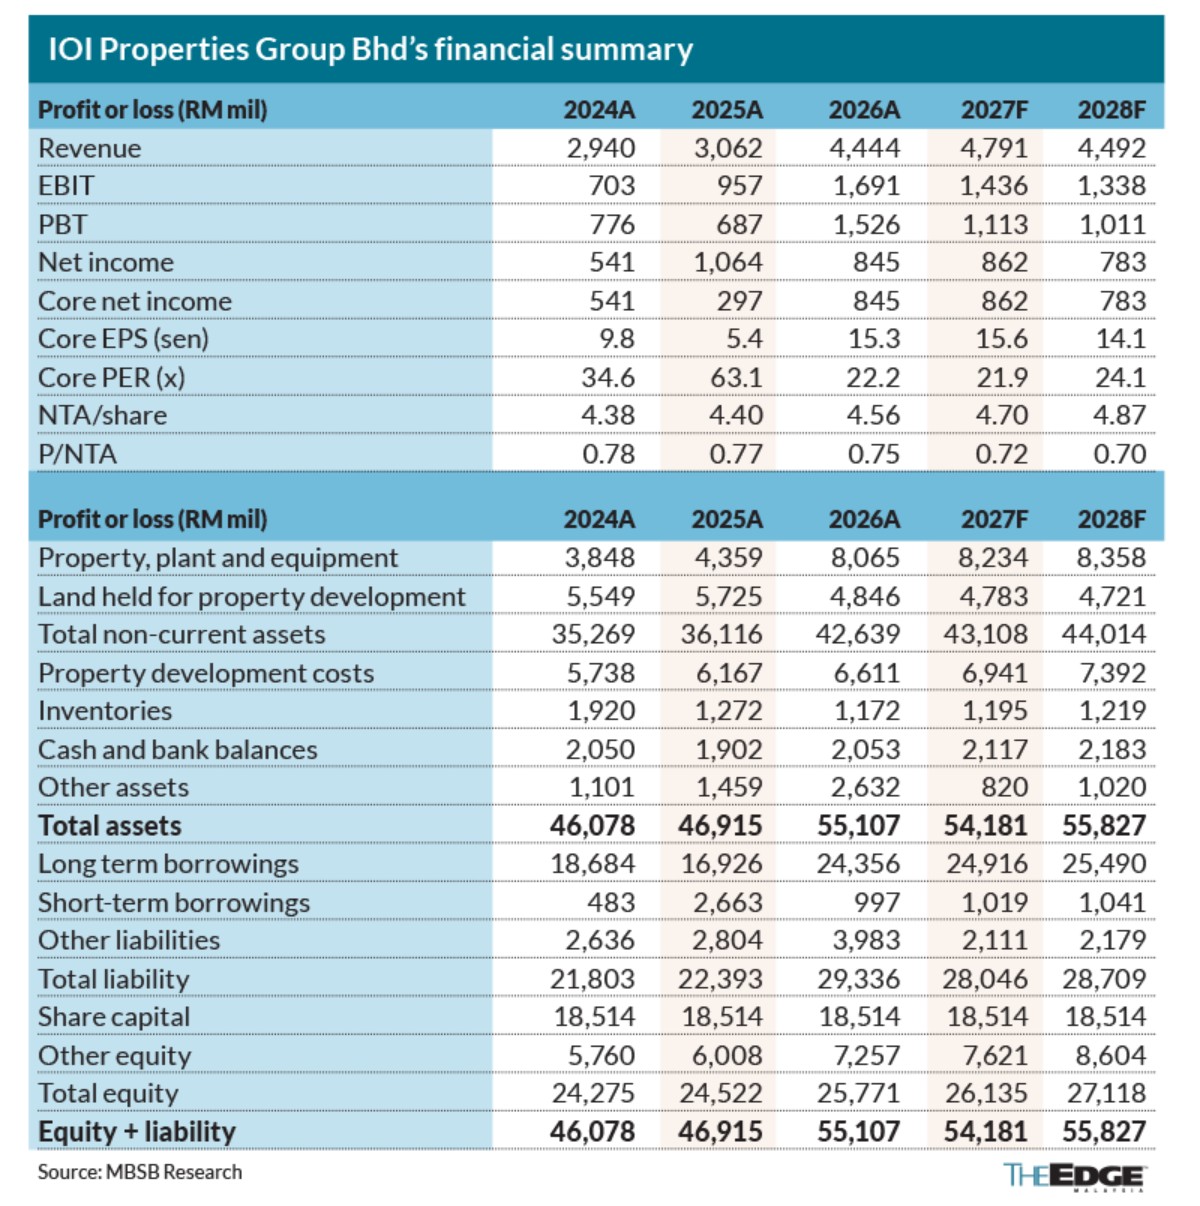
Separately, MBSB Research is neutral on the acquisition despite it strengthening IOI Properties' presence in Singapore, as it is expected to place additional pressure on the group's balance sheet.
The house estimates that the acquisition will raise net gearing to 0.91 times from 0.88 times, while also noting the group's requirement to absorb Shenton 101 Pte Ltd's FY2025 loss after tax of S$23 million.
MBSB estimates the deal may weigh on IOI Properties' FY2027 earnings by 8%, while the project's benefits are likely to materialise only over the longer redevelopment period.
The research firm maintained its earnings forecast pending completion of the acquisition.
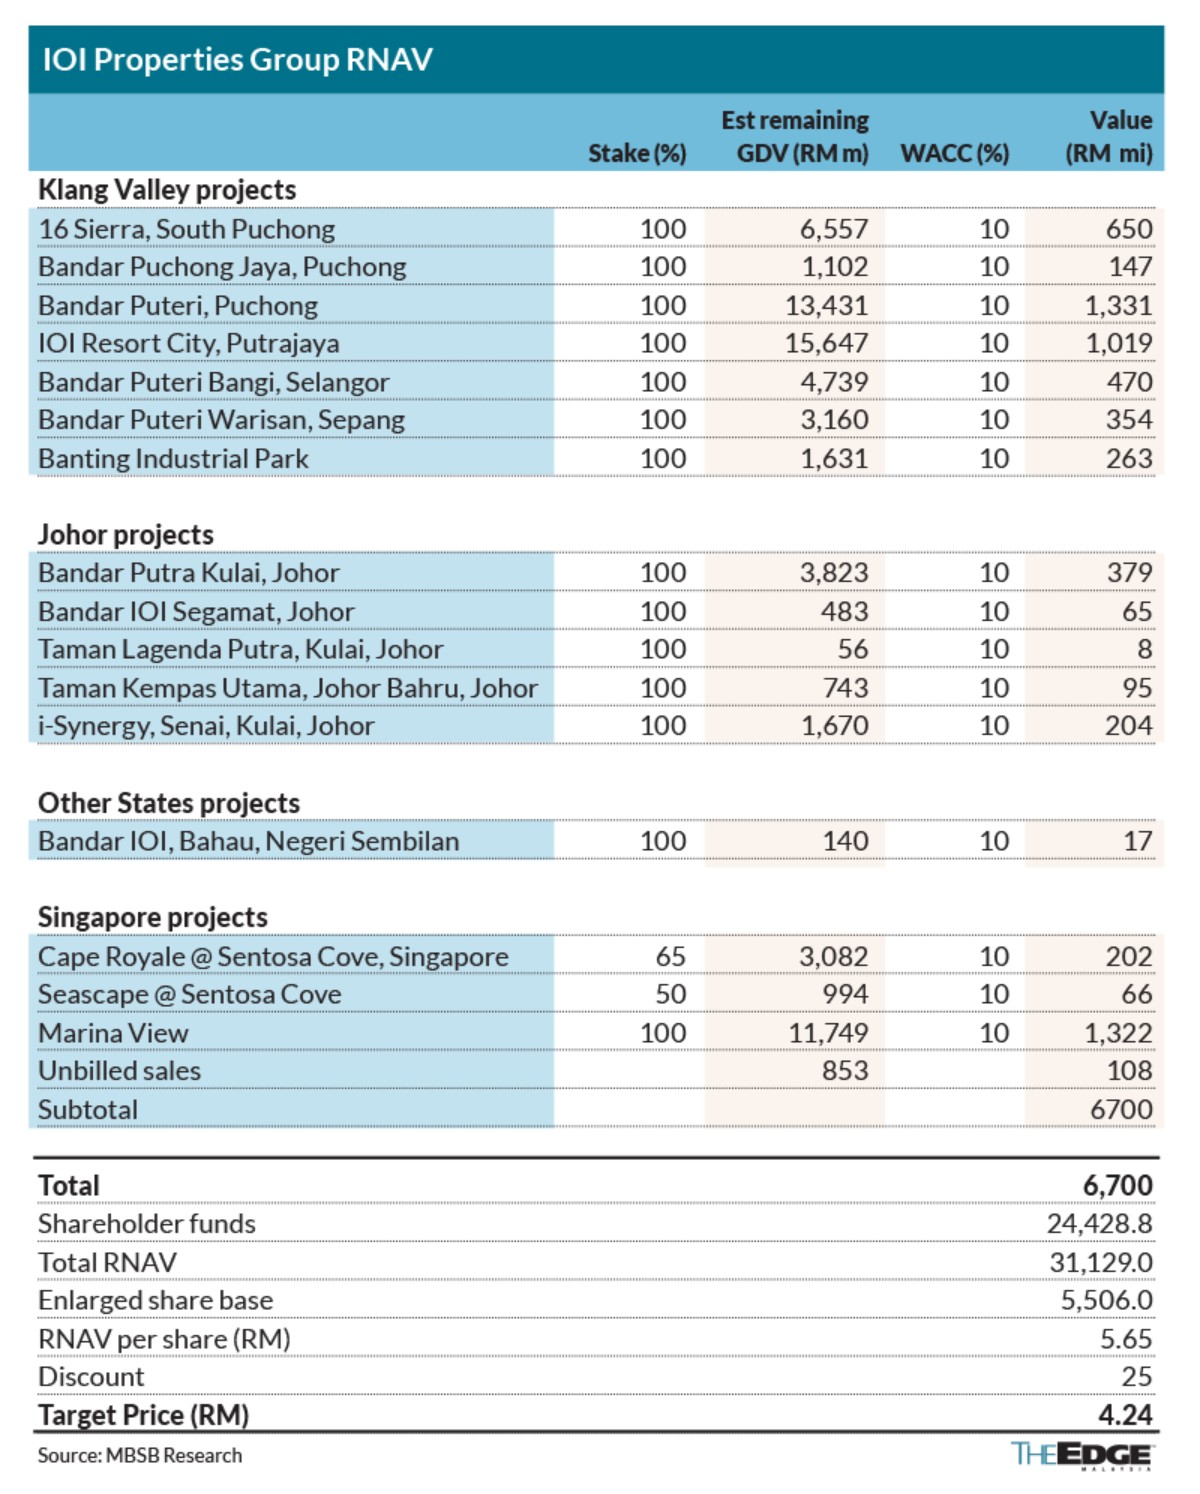
MBSB revised its target price for IOI Properties to RM4.24 from RM4.64, widening its real net asset value (RNAV) discount to 25% from 18% due to concerns over higher net gearing following the acquisition.
Nevertheless, the house continues to see value in the group, supported by its ongoing efforts to monetise its landbank, which should unlock value and support future earnings growth.
In addition, the proposed listing of the REIT remains a key near-term catalyst, said MBSB, while maintaining its 'buy' call on IOI Properties.