

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
AMMB Holdings Bhd
Once again, AMMB Holdings Bhd (KL:AMBANK) is taking home The Edge Billion Ringgit Club (BRC) award for Highest returns to shareholders over three years under the financial services category.
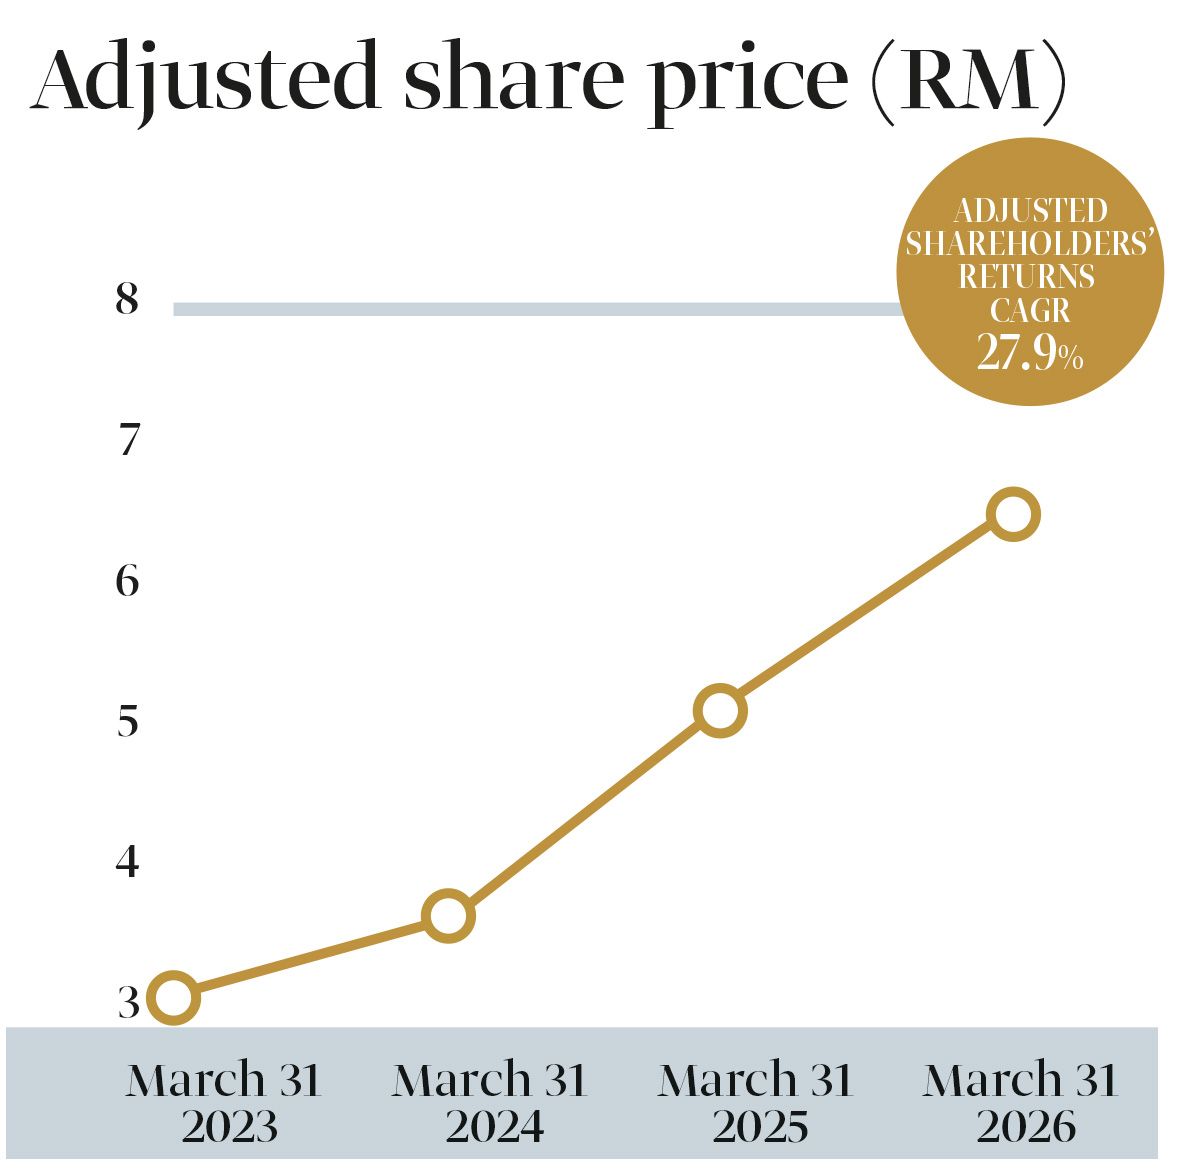
Notably, its share price has climbed steadily over the last five years, with the most significant jump recorded between 2024 and 2025. The stock gained 41.9% from RM3.70 on March 31, 2024 to RM5.25 on March 28, 2025.
Between March 28, 2025 and March 31, 2026, the banking group’s share price continued its upward trajectory, reaching RM6.59, before hitting another record high of RM7.37 on Aug 12.
Much of the enthusiasm about the stock can be linked to the potential return of excess capital to shareholders, which could either come in the form of higher dividends or through other capital return initiatives.
AMMB, under its five-year strategic plan called “Winning Together 2029” (WT29), aims to double its dividend per share by the financial year ending March 31, 2029 (FY2029) from 22.6 sen in FY2024. This would be supported by earnings growth and capital optimisation, with Basel 3.1 reforms providing a meaningful upside catalyst.
AMMB has already been increasing its dividend payout ratio, from 40% to 50% in FY2025, exceeding its earlier dividend payout ratio guidance of 35% to 40%. Total dividends increased from 22.6 sen in FY2024 to 30.2 sen in FY2025 and 35 sen in FY2026.
Its three-year compound annual growth rate for shareholder returns totalled 27.9% for the period between March 31, 2023 and March 31, 2026.
The increase in dividends can also be attributed to the yearly improvements in earnings. In FY2026, the group achieved its highest-ever net profit of RM2.1 billion, 5% higher than the previous year’s RM2 billion, driven by both net interest income and non-interest income. Net profit was RM1.87 billion in FY2024.
Net interest income rose 4.5% in FY2026, backed by higher margins, while non-interest income grew 5.1% mainly from trading gains.
For FY2026, the bank recorded a return on equity (ROE) of 10%, in line with its guidance to analysts. The group’s ROE has stayed at 10% over the last three financial years.
In the recent 1QFY2027 financial performance, AMMB’s net profit came in at RM520.23 million, up slightly from RM516.18 million in the previous year on account of improvement in net interest income growth. The earnings were within analyst expectations.
Non-interest income grew 5.1% year on year, supported by stronger wealth management fee income but net interest income was softer, compressing to 1.93% in 1QFY2027 from 1.97% in 4QFY2026, as competitive asset pricing and funding mix pressures weighed on margins.
CIMB Securities has downgraded its call on AMMB to “hold” with an unchanged target price of RM7.35, based on 1.09 times price-to-book value (PBV).
“While we remain constructive on AMMB’s medium-term capital return and efficiency story, we believe the key rerating catalysts from its recent WT29 capital management update are largely priced in. The next catalyst, the Basel 3.1-driven capital release, remains some distance away given its implementation date of Jan 1, 2028,” said the research house in a report dated Aug 19.
It added that while further rerating under the FY2028 valuation framework is possible, the rerating will need to be supported by earnings delivery rather than valuation roll-forward alone.
Meanwhile, HLIB Research — which has kept its “buy” call on the stock for a target price of RM7.80 based on an implied 2027 PBV of 1.1 times — said its loan growth should remain firm going forward, led by mid-corporate and wholesale banking, adding that it should start contributing more meaningfully to non-interest income from 2QFY2027.
Nonetheless, it also warned that the prolonged Middle East disruptions could create further stress among selected Business Banking accounts, although the management is expecting around half of the current stage 2 exposures to revert to stage 1 by September if logistics disruption normalises.
HLIB Research added that the capital appreciation still has legs, “propelled by the plausible rerating catalyst of a potential RM2 billion capital return from FY2028”. It has estimated that the capital return could translate into a dividend yield of over 8.5% for 2028.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.