

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Alliance Bank Malaysia Bhd
Alliance Bank Malaysia Bhd (KL:ABMB) has made a clean sweep this year, bagging all three awards under the financial services (below RM10 billion market capitalisation) category.
The awards are for the Highest return on equity (ROE) over three years, the Highest growth in profit after tax over three years and the highest returns to shareholders over three years. This also marks the banking group’s first wins in The Edge Billion Ringgit Club (BRC) Awards.
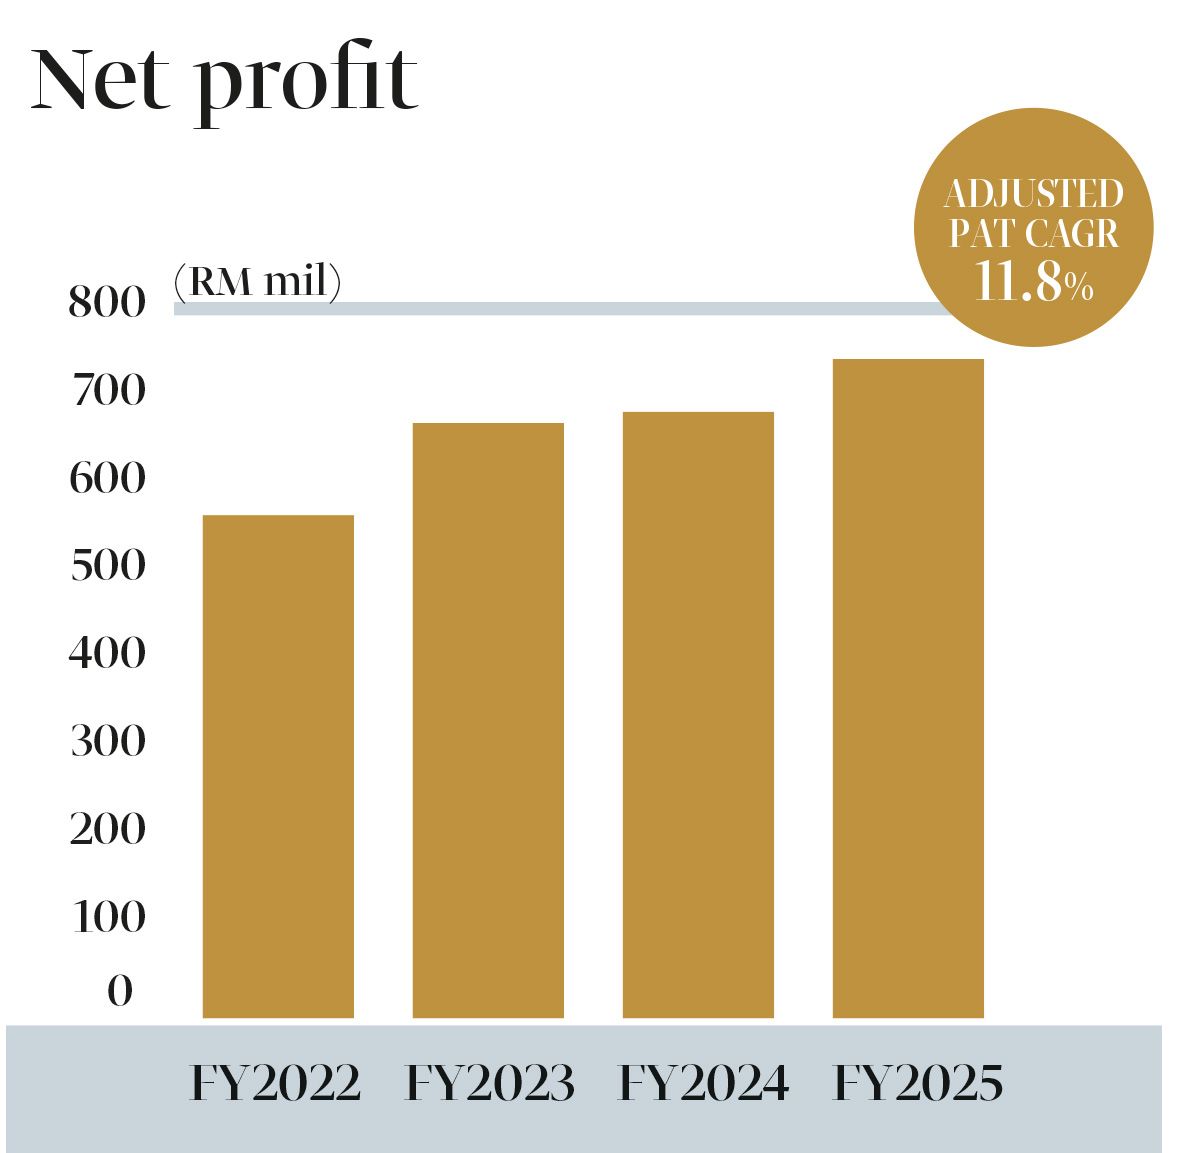
Alliance Bank’s net profit growth over the past three years has been impressive. It registered a three-year compound annual growth rate (CAGR) of 11.8% between FY2022 and FY2025. Net earnings hit successive record highs as the banking group made significant strides under its Acceler8 2027 transformation strategy.
From RM572.8 million in FY2022, net profit grew 18.33% to RM677.8 million in FY2023 and 1.87% to RM690.5 million the following year.
Net profit continued to grow in FY2025, rising 8.7% year on year (y-o-y) to a record RM750.7 million, supported by a record revenue of RM2.3 billion arising from a 13.2% growth in net interest income. Net interest margin in FY2025 stood at 2.45%, while other operating income increased 7.7% y-o-y, largely due to higher revenue from treasury and investment income as well as trade fees.
Alliance Bank, whose financial year ends on March 31, again posted a record net profit and revenue of RM826.5 million and RM2.5 billion respectively for FY2026.
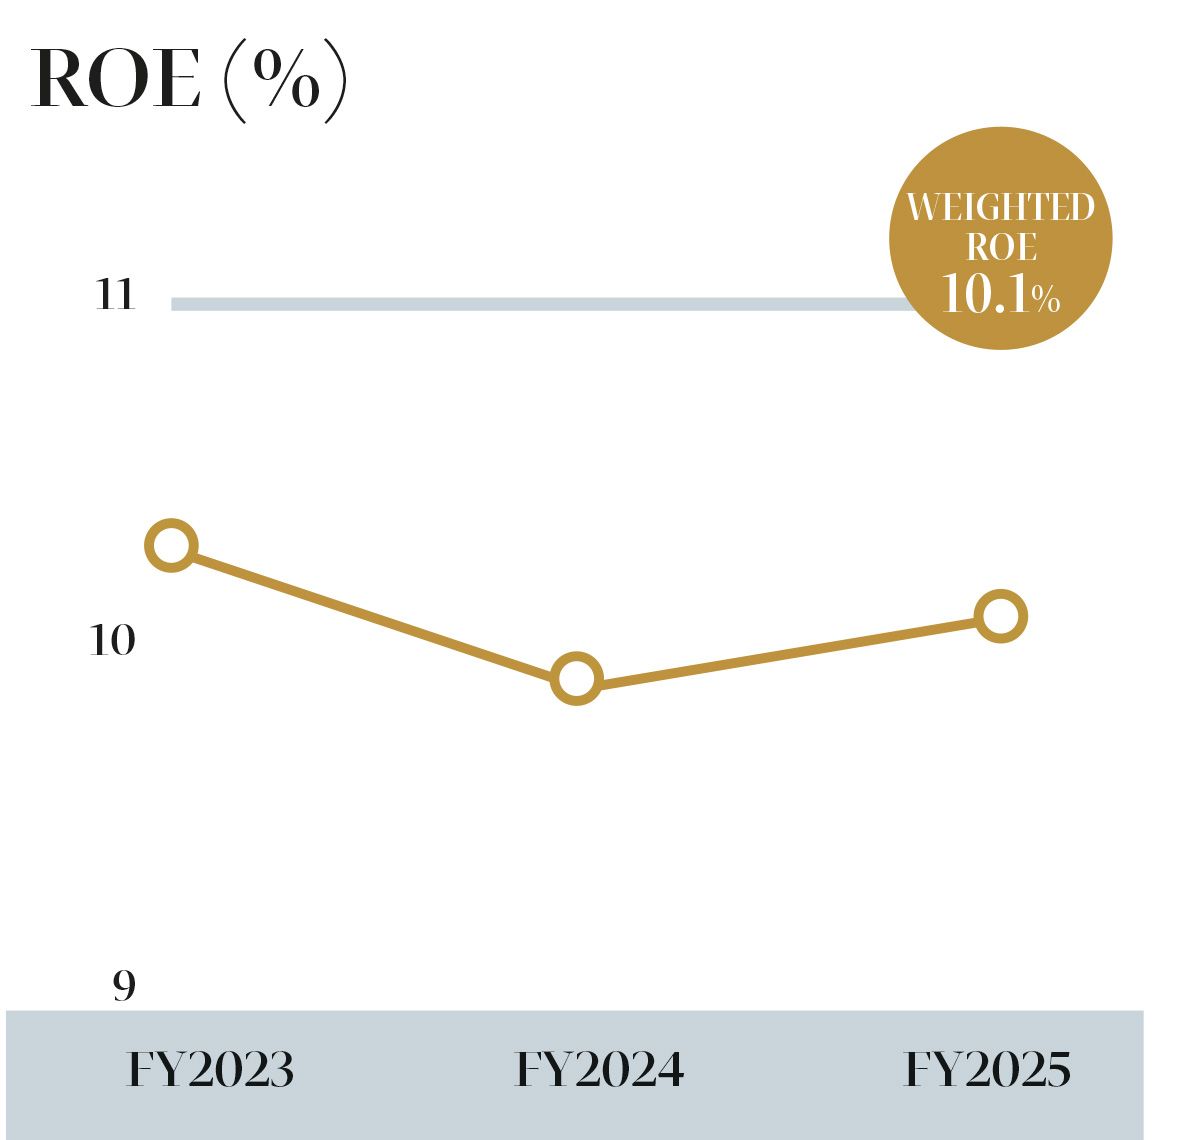
Achieving a top-quartile ROE in the banking industry is one of Alliance Bank’s goals under the Acceler8 2027 programme. Between FY2023 and FY2025, its ROE averaged between 9.9% and 10.3%, resulting in an adjusted weighted ROE of 10.1% over the period.
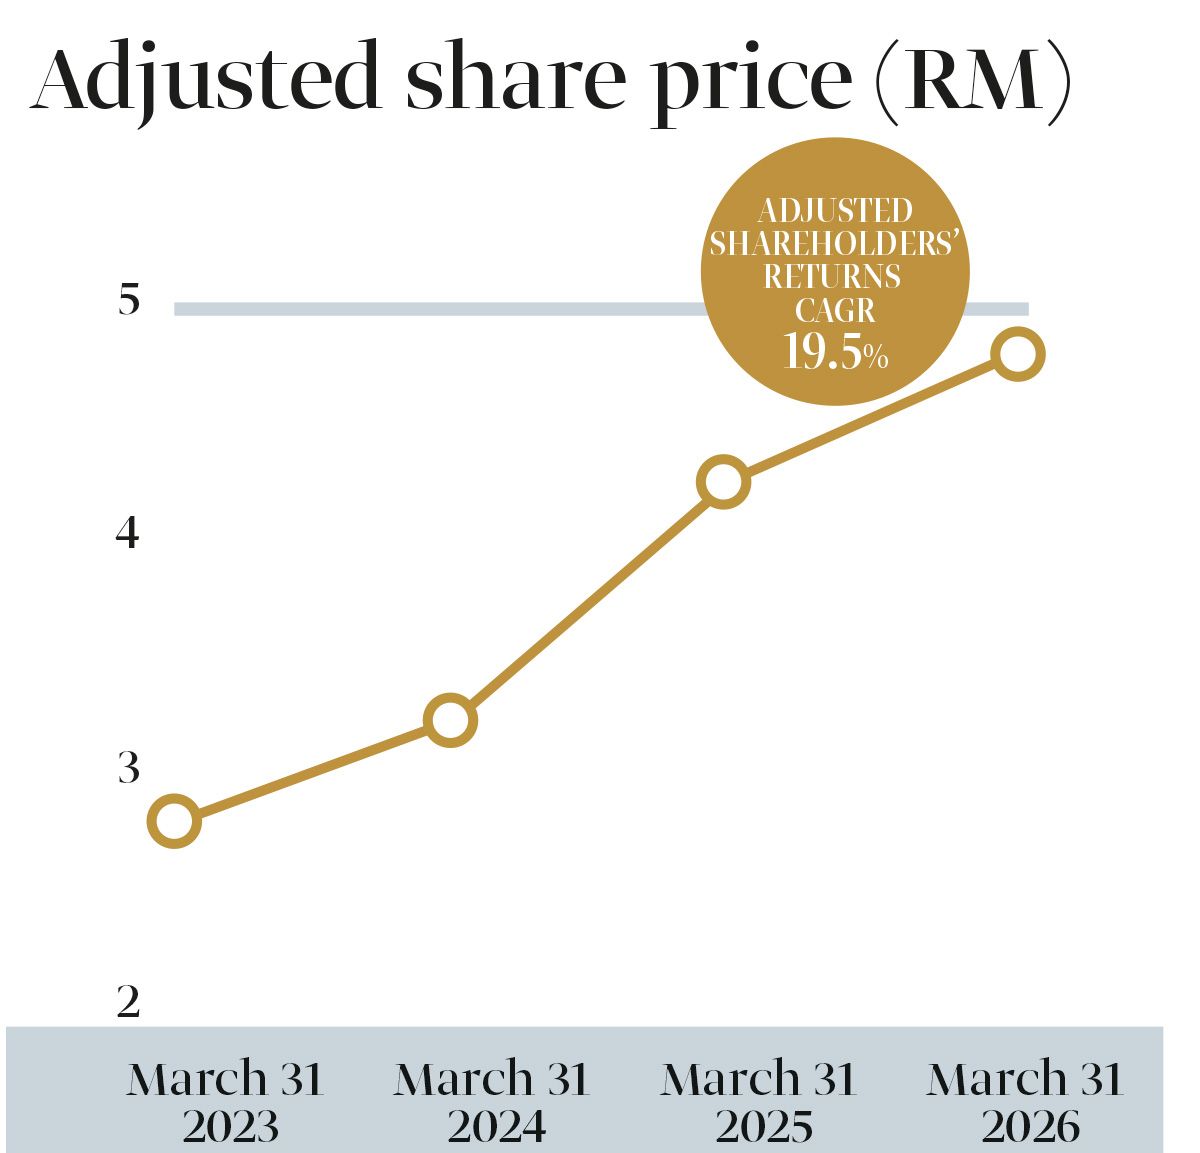
Meanwhile, Alliance Bank’s net profit growth momentum has caught investors’ attention. Its share price rose from RM2.82 on March 31, 2023, to RM3.26 on March 31, 2024. The upward trajectory continued over the following two years, with the stock reaching RM4.82 on March 31, 2026 — the final date of the review period for the BRC awards. This translated into a three-year shareholders’ return CAGR of 19.5%.
Its share price slipped slightly to a low of RM4.42 on April 13, 2026, before rebounding to close at RM4.92 on Aug 28.
Alliance Bank paid a lower dividend of 19.1 sen per share in FY2026, compared with 19.4 sen in FY2025, 22.3 sen in FY2024 and 22 sen in FY2023.
The group has started FY2027 on a strong note. Its 1QFY2027 net profit rose 25% y-o-y to RM248.3 million, mainly due to a 98.7% decline in loan loss provisions following the recovery of a corporate loan in the construction sector.
In a report, CGS International Securities anticipates that the normalisation of loan loss provisions will result in a drop in 2QFY2027 net profit, bringing it back in line with the levels recorded between 2QFY2026 and 4QFY2026.
CIMB Research, which has a “hold” call on the stock, pointed out that the banking group has demonstrated a steadier asset quality trend on a y-o-y basis, with its gross impaired loan (GIL) ratio edging down to 1.83% from 1.96% a year earlier, driven by credit recovery in its books.
However, GIL ratios for its consumer and small to medium enterprises portfolios continued to deteriorate, rising to 2.2% and 2.1% respectively. The 30 days-past-due ratio also continued to creep up, although the research house noted that the stress was isolated to certain higher-risk borrowers.
CGS also said Alliance Bank could see an enhancement of 60 to 70 basis points in its common equity Tier-1 (CET1) capital ratio following the Basel III reforms.
“The bank does not expect to pay out any excess capital from the above as special dividends. Instead, the enhancement in its CET1 capital ratio would enable the bank to increase its dividend payout ratio (from 40%-50% guided for FY2027) in the longer term,” according to the bank.
CGS has an “add” call on the banking group with a target price of RM5.70, citing potential rerating catalysts including strong growth in non-interest income, above-industry loan growth, potential write-back in management overlays and its expectation of a higher dividend payout ratio from FY2027 to FY2029.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.