

This article first appeared in Wealth, The Edge Malaysia Weekly on September 28, 2026 - October 4, 2026
Tokenisation, the act of representing an asset or claim as a token on a distributed ledger or blockchain, has remained under the radar among local financial institutions. Until recently.
The catalyst, market observers say, came from Bank Negara Malaysia, when it launched the Digital Asset Innovation Hub (DAIH) in June 2025 and published its discussion paper on asset tokenisation in the Malaysian financial sector in October 2025.
The public feedback window for the discussion paper closed on March 1, 2026, and Bank Negara hosted its third Asset Tokenisation Industry Working Group session in August this year.
The discussion paper states that proof-of-concepts and live pilots will be conducted in a controlled environment through the DAIH this year, with testing expected to continue into 2027, alongside the compilation and publication of findings and the evaluation of key insights.
Three banks have launched initiatives under the DAIH. The banks are under CIMB Group Holdings Bhd (KL:CIMB); Standard Chartered Bank Malaysia Bhd (Standard Chartered Malaysia), together with Capital A Bhd (KL:CAPITALA); and Malayan Banking Bhd (KL:MAYBANK).
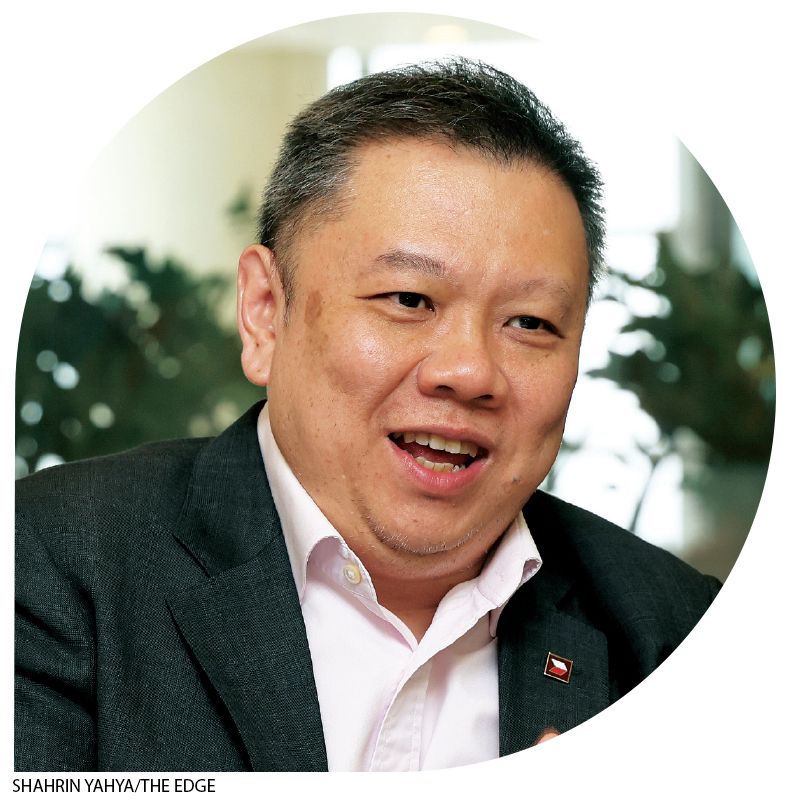
Chu Kok Wei, CEO of group wholesale banking and corporate treasurer at CIMB Group, says Malaysian banks are not the earliest to embrace the technology, but they have been moving fast recently.
“We might be the country that’s moving at the fastest speed in Southeast Asia in the last one year, based on my observation, by looking at all the stakeholders and our experience and conversation with regulators,” he says.
His observation coincides with the findings of HSBC’s Redefining Treasury in Asia Pacific 2026: Voices of Treasury report, published on Sept 17.
The report notes that Malaysia stands out as the most enthusiastic market in the region on digital currency adoption, with 50% of respondents saying they were very likely to use digital currencies in the next two years, far higher than the regional average of 19%.
Digital currency is tokenised money, which can take the form of tokenised deposits, stablecoins or central bank digital currency.
Some 42% of respondents in Malaysia also say digital assets in treasury are high risk, broadly in line with the regional average of 44%, even as they see both opportunity and complexity.
The biggest benefits of tokenisation, which is underpinned by blockchain or distributed ledger technology, are greater treasury efficiency (73%) and enhanced liquidity management (50%).
“The challenge now is for market infrastructure to catch up to the demand,” says Anand Mukati, head of global payments solutions at HSBC Malaysia.
Elsewhere, global banks in developed markets such as the US have been moving fast in tokenisation by adopting blockchain technology.
In its Tokenisation 2030: Wall Street On-Chain report published in June, US-based multinational bank Citigroup points out that tokenisation is moving towards operational reality.
The Depository Trust and Clearing Corporation (DTCC), the US industry-owned clearing house and central securities depository, received regulatory clearance in late 2025 to offer a tokenisation service for DTCC-custodied assets, with a three-year pilot planned for late 2026.
The New York Stock Exchange (NYSE) announced plans for a tokenised securities platform by late 2026, subject to regulatory approval, which would enable 24/7 trading of US-listed equities and exchange-traded funds (ETFs) with near-instant settlement and stablecoin-based funding.
Nasdaq has also received the Securities and Exchange Commission’s (SEC) approval to enable certain stocks and ETFs to be issued, traded and settled in tokenised form.
“These organisations are not crypto-native firms pushing blockchain, but some of the oldest and largest financial institutions adopting new infrastructure,” according to Citi.
On Sept 17, the SEC unveiled its long-awaited exemption that will allow companies to offer trading in blockchain-based or “tokenised” stocks and other securities.
Four days later, the European Central Bank launched preparatory work to invest a small portion of its own fund in tokenised securities, enabling it to gain practical experience as an investor and build institutional expertise in the use of distributed ledger technology in financial markets. The world is moving fast.
Completed and ongoing initiatives
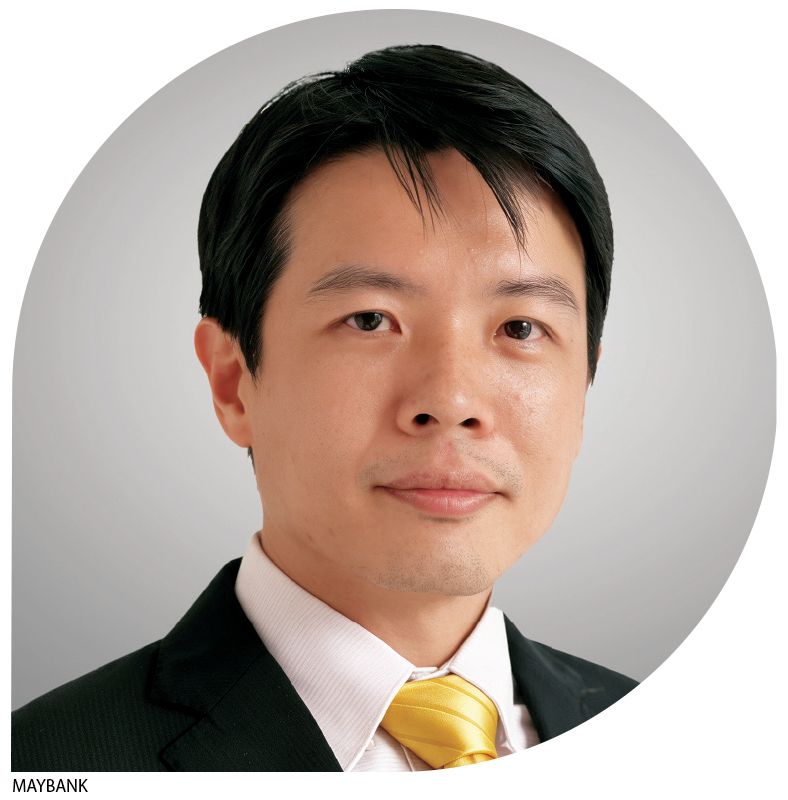
When Khazanah Nasional Bhd completed its RM100 million tokenised sukuk pilot project in mid-May, CIMB acted as its sole principal adviser, sole lead arranger and sole facility agent.
About three months later, the bank took that experience further, completing the country’s first pilot testing of the settlement of tokenised sukuk using tokenised deposits in a controlled environment.
For comparison, Khazanah’s tokenised sukuk pilot project settled the exchange of sukuk on the blockchain, but its cash transactions were conducted through traditional banking channels in fiat currency instead of tokenised deposits.
Put simply, a tokenised deposit is a form of digital money that is transferred and settled on a secure blockchain or distributed ledger, rather than through traditional payment infrastructure such as PayNet’s Real-time Retail Payments Platform (RPP) or Bank Negara’s RENTAS+.
In an interview with Wealth, CIMB’s Chu says the bank’s pilot project represents a meaningful breakthrough, with CIMB Islamic Bank Bhd issuing RM1.68 billion in sukuk under its existing RM10 billion senior sukuk wakalah programme, across tenors of five, seven, 10 and 15 years.
Of the total issuance, RM1.38 billion was represented in tokenised form and subscribed by 12 institutional investors.
Both legs of the transaction — CIMB’s tokenised sukuk and the tokenised deposits used to pay for them — were settled on the bank’s own blockchain, CIMB Blockchain Connect.
“Khazanah’s tokenised sukuk pilot project was RM100 million with a one-year tenure. We were part of the consortium that arranged the transaction. We took that learning and, in less than five months, we printed our own transaction of RM1.68 billion, out of which RM1.38 billion was tokenised up to 15 years.
“This progression is important. That means we are moving from a pilot size transaction to a market size transaction backed by real investor demand,” he says.
Institutions that subscribed to CIMB’s tokenised sukuk include sovereign wealth funds, pension funds, insurers, corporates and asset managers, reflecting market confidence in the programme.
“We like to think that we have built enough momentum for this to carry forward,” says Chu.
The DAIH’s official website lists the initiatives of the three banks. CIMB focuses on tokenised deposits for the settlement of tokenised securities, Maybank on tokenised deposits for payments, and Standard Chartered Malaysia and Capital A on ringgit stablecoins for business-to-business (B2B) settlement.
Maybank also played a leading role as joint lead manager, custodian and primary subscriber of Khazanah's RM100 million tokenised sukuk pilot project.
In an email response, Maybank global head of markets structuring and quants Rivai Tan says the bank has explored and tested use cases within its own environment to accelerate learning.
“This led to initiatives spanning tokenised deposits, near real-time cross-border payments and tokenised investment solution pilots,” he says.
Among the initiatives Maybank is involved in is a RM1 million pilot transaction for tokenised supply chain financing, announced on Aug 20 and aimed at enhancing transparency and resilience across supply chain ecosystems.
The transaction was carried out in partnership with Virtual Economy Technology Sdn Bhd (V System) via its tokenisation platform, NexA. V System is a participant in the Securities Commission Malaysia’s regulatory sandbox to pilot innovative blockchain-based solutions.
Earlier, on March 30, the bank successfully completed the first transaction of its tokenised deposits and cross-border payments with energy infrastructure company Yinson Holdings Bhd (KL:YINSON). The project integrates the tokenisation of bank deposits with an on-chain foreign exchange (FX) conversion of ringgit to Singapore dollars, and a subsequent cross-border payment between the two countries in near real-time, using Maybank’s permissioned blockchain.
“Our focus is on turning tokenisation from concept into real-world applications,” says Tan.
Maybank Singapore has also joined the Monetary Authority of Singapore’s BLOOM initiative, an industry project to improve cross-border payments using tokenised bank liabilities and regulated stablecoins through an interoperable digital financial system.
On the ringgit stablecoin initiative for B2B settlement with Capital A, Standard Chartered Malaysia interim CEO, head of coverage and chief financial officer Mushahid Syed says: “It is still in an initial testing phase. We will share further details subject to approval from Bank Negara.”
In his email response, Mushahid Syed adds that the bank’s focus is on connecting tokenised assets to the wider ecosystem, including digital money, custody, trading, collateral and settlement infrastructure.
“This includes exploring how digital forms of money can interact more seamlessly with tokenised assets, enabling more efficient access to yield-bearing investment products, and how these tokenised assets themselves can be used as collateral across the financial ecosystem,” he says.
Trading tokenised bonds and sukuk on the blockchain
While not spelling out the bank’s next step on its tokenisation initiative, CIMB’s Chu says market players would expect the trading of CIMB’s tokenised sukuk on the blockchain.
“We started with the issuance of tokenised securities. Bonds and sukuk being a tradable instrument, naturally, industry players would look at how we can trade these tokenised securities more efficiently [on the blockchain] and start to harness the benefits of it,” he says.
Halogen Capital, the country’s first digital asset manager, is one of the institutions that subscribed to CIMB’s tokenised sukuk. Its founder and CEO Hann Liew echoes Chu’s view.
“We purchased one lot of CIMB tokenised sukuk, and CIMB gives us access to view the tokens. There’s an online platform where institutional investors like us can log in and see our holdings. Put simply, it is like CIMB Octo for retail users, where you can log in and see your details.
“However, the challenge is the next step, which is to enable active on-chain trading of the sukuk, which isn’t yet live. Can we see transactions that happened on the blockchain? Can we conduct analysis and trade on it?” he says.
One might ask how it is different when tokenised sukuk is traded on the blockchain. Chu points to several key features, including instant settlement, round-the-clock trading and fractionalisation.
With a distributed ledger shared across various parties, a trade executed on the blockchain can be settled almost instantaneously — otherwise known as “atomic settlement” — which reduces settlement risk. Settlement risk is the danger that the money is paid but the securities are not delivered, or vice versa.
A classic example dates back to 1974, when banks globally paid Deutsche marks to German lender Herstatt Bank in the morning but did not receive the US dollars they expected later in the day. Herstatt had made wrong directional bets on the greenback and was shut down by regulators midday, with the value of transactions left unsettled estimated at US$200 million. Settlement risk becomes severe when large sums are involved.
Meanwhile, when trades can be matched, settled and recorded automatically and efficiently, bonds and sukuk can be traded round the clock, translating into cost savings and a potentially more vibrant market.
Tokenised securities and deposits are programmable, which is where smart contracts come into play. A smart contract is code on a blockchain that automatically carries out the terms of an agreement when conditions are met, without human intervention.
Chu says smart contracts can be used for market events. For instance, where a bond or sukuk pays a coupon every six months, the profit can be distributed automatically via the distributed ledger.
“All these are baby steps that we are taking, from the primary market to secondary, and eventually it covers even redemptions,” he says.
Tokenised securities can be fractionalised, which opens up the possibility of tokenised bonds and sukuk becoming easily accessible to retail investors at a much lower amount. But Chu says tokenisation and blockchain are merely a technological enabler; further democratisation of bonds and sukuk would require changes in rules and regulations.
“We all need to kind of contain our excitement about how tokenisation enables retail participation for now. It provides a platform, but suitability for investors, fair disclosure [of information] and all other relevant processes have to be continuously assessed by the regulators,” he says.
Interoperability between blockchains, and between the new and old systems
Against such a backdrop, tokenisation initiatives undertaken by local banks are based on the “digital twin” concept, which means the on-chain token mirrors the traditional legal records rather than replacing them.
“From a legal sense, digital twin means the whole process of the issuance of CIMB sukuk follows existing rules and regulations and contract. The original contract remains valid, while the digital token is only a replica. In this case, you don’t need to answer what is the relationship of the replica and the underlying assets,” says Chu.
However, the country’s rules and regulations will need to change if financial services were to move fully onto the blockchain, which is one of the challenges in tokenisation.
Chu says other challenges include interoperability, which means the deployment of digital tokens across the different blockchains of different banks.
However, he says CIMB prefers to focus on something else: the interoperability between the new technology, which is the blockchain, and the existing ones, especially in the bond market.
“This is much more important as bonds and sukuk are an established asset class with a total value of more than RM2 trillion in the system. How can these assets slowly evolve over time, so that people can embrace the new ones [issued with the new technology] without feeling that the old ones are out of fashion?
“This is extremely important, as institutional fund managers can be holding a 30-year bond today. There are many 30-year bonds out there and they start to worry about what happens if all these are going to be tokenised,” he says.
Maybank’s Tan agrees that beyond technology and process design, the successful deployment of tokenisation also depends on many other factors, including interoperability, regulatory alignment and broader industry adoption.
From a practical perspective, a key challenge lies in integrating tokenised solutions into existing systems, processes and operating models, he adds.
This means a bank needs to stay forward-looking and rethink workflows from the ground up, including what should be retained, rebuilt, simplified or, in some cases, fundamentally redesigned to realise the full benefits of tokenisation.
“Realising the full potential of tokenisation will require close collaboration among regulators, financial institutions and technology providers to establish common standards and trusted market infrastructure,” says Tan.
Standard Chartered Malaysia’s Mushahid Syed adds that developing digital infrastructure that offers accessible, cost-effective and instant alternative wholesale payments is key for a trading nation like Malaysia, with its strong small and medium enterprise base.
There is little doubt that tokenisation, underpinned by blockchain technology, will make banking and financial services more efficient and effective when it matures. Workflows, organisational structures and the content of certain jobs may evolve. Changes are already afoot.
“An example I always tell everyone is that we are now using iPhone 18, which has evolved significantly from its first version. The same applies to the evolution of the financial services industry and the role of people working in it,” says Chu.
Tokenisation is pushing banks to run around the clock, says Citi’s Iyer
Global banks like Citi have been commercialising tokenisation in recent years, with plans to roll out new services beyond near-instantaneous cross-border settlements, including digital asset custody and tokenised securities.
Mirdula Iyer, Citi’s head of services for Asia South, says the bank went live with Citi Token Services for Cash in 2024 after exploring and working with blockchain for five years.
Citi Token Services for Cash enables near-instantaneous movements of tokenised deposits, supporting the US dollar (USD) and euro. It is integrated with the bank’s 24/7 USD clearing solution, connecting Citi and non-Citi accounts, and bridges the bank’s blockchain and traditional payment networks for client interoperability.
“A Citi corporate client could use the services to transfer USD from their UK to Singapore accounts over a weekend. Once that amount is in their Singapore account, they can then use our USD clearing solution to move it to a non-Citi beneficiary client account in the same weekend, round-the-clock,” she says.
Iyer says the service is live across five markets, and adoption across major hubs — the US, Singapore, Hong Kong, Ireland and the UK — has been strong, with close to US$1 billion moved daily.
In addition to the tokenisation of money, Citi is looking to expand its securities tokenisation and custody capabilities, with the latter going live this year.
“On securities tokenisation, we went live with our Digital Depositary Receipts this year, marking the first time a global financial services company is both issuing and acting as a custodian for tokenised depositary receipts representing private companies,” she says.
“Separately, our issuer services business is at the forefront of digital issuance capability, having already supported issuances amounting to around US$1 billion in digitally native notes.”
Iyer acknowledges that many of Citi’s clients still rely on older systems. The bank’s job is to help them update their processes and risk management with new technology.
Moving forward, she believes money and assets such as deposits, payments and investments will increasingly exist in both traditional and digital, tokenised formats. As interoperability improves, clients will expect their money to move smoothly, anywhere and anytime.
In Asia, such a shift is speeding up as more digitally savvy everyday investors enter the market, pushing for newer tools and platforms. All this while stock exchanges globally are staying open longer to support non-stop trading.
“The role of a bank is shifting. Instead of only processing transactions during set business hours, banks are also helping clients move money continuously around the clock while keeping the system secure, connected and reliable,” she says.
A key to this future is interoperability across banks and the broader financial services ecosystem through industry initiatives and working groups, and it is important that industry participants are engaged.
“Some examples include Swift’s ledger infrastructure, the Depository Trust and Clearing Corporation’s upcoming tokenisation services and the ongoing modernisation of financial infrastructures. There is also Project Agora, which is looking to make cross-border transactions faster and more transparent,” says Iyer.
Project Agora is a public-private collaboration convened by the Bank for International Settlements and the Institute of International Finance to test a multi-currency shared programmable platform for wholesale and cross-border payments.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.