

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
IGB REIT
IGB Real Estate Investment Trust (KL:IGBREIT) has built a reputation for keeping its malls well occupied, growing rentals and continually refreshing its retail offerings to attract shoppers.
That consistency has once again earned the retail-focused trust a place among The Edge Billion Ringgit Club (BRC) members.
For the ninth consecutive year, IGB REIT has taken home the corporate award for Highest return on equity (ROE) over three years in the REIT sector, extending a winning streak that began in 2018.
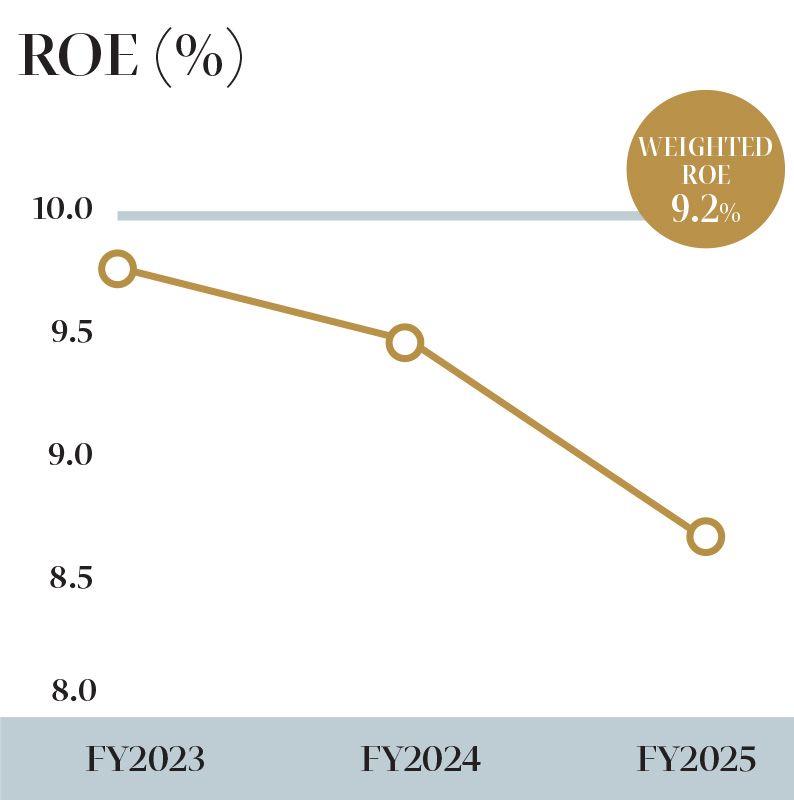
Its three-year adjusted weighted ROE came in at 9.2% per annum, after recording ROEs of 9.8% in the financial year ended Dec 31, 2023 (FY2023), 9.5% in FY2024 and 8.7% in FY2025.
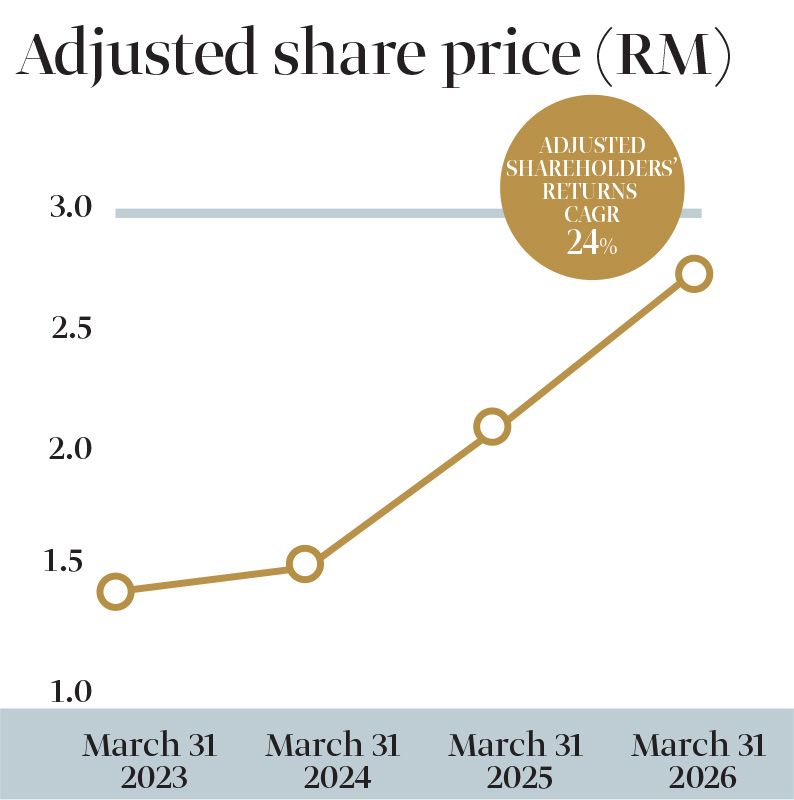
Also, for the second year in a row, IGB REIT bagged the award for Highest returns to shareholders over three years, as it delivered a three-year compound annual growth rate of 24%.
This was based on its adjusted unit prices of RM1.45 as at March 31, 2023, and RM1.55 and RM2.13 in the subsequent two years, before rising further to RM2.76 as at end-March 2026.
The unit price hit an all-time high of RM3.16 on May 15, before paring gains to close at RM2.75 on Aug 28, giving the REIT a market capitalisation of RM11.9 billion.
IGB REIT’s history with the BRC stretches further back to 2016, when it first won for Highest growth in profit over three years.
Its distributable income has risen steadily — from RM361.9 million in FY2022 to RM385.8 million in FY2023, RM395.9 million in FY2024 and RM457.4 million in FY2025.
Similarly, net property income (NPI) increased from RM420.2 million in FY2022 to RM447.9 million in FY2023, RM455.7 million in FY2024 and RM533.6 million in FY2025.
In FY2025, the trust rewarded its unitholders with a higher distribution per unit (DPU) of 11.75 sen compared with 10.7 sen in FY2024.
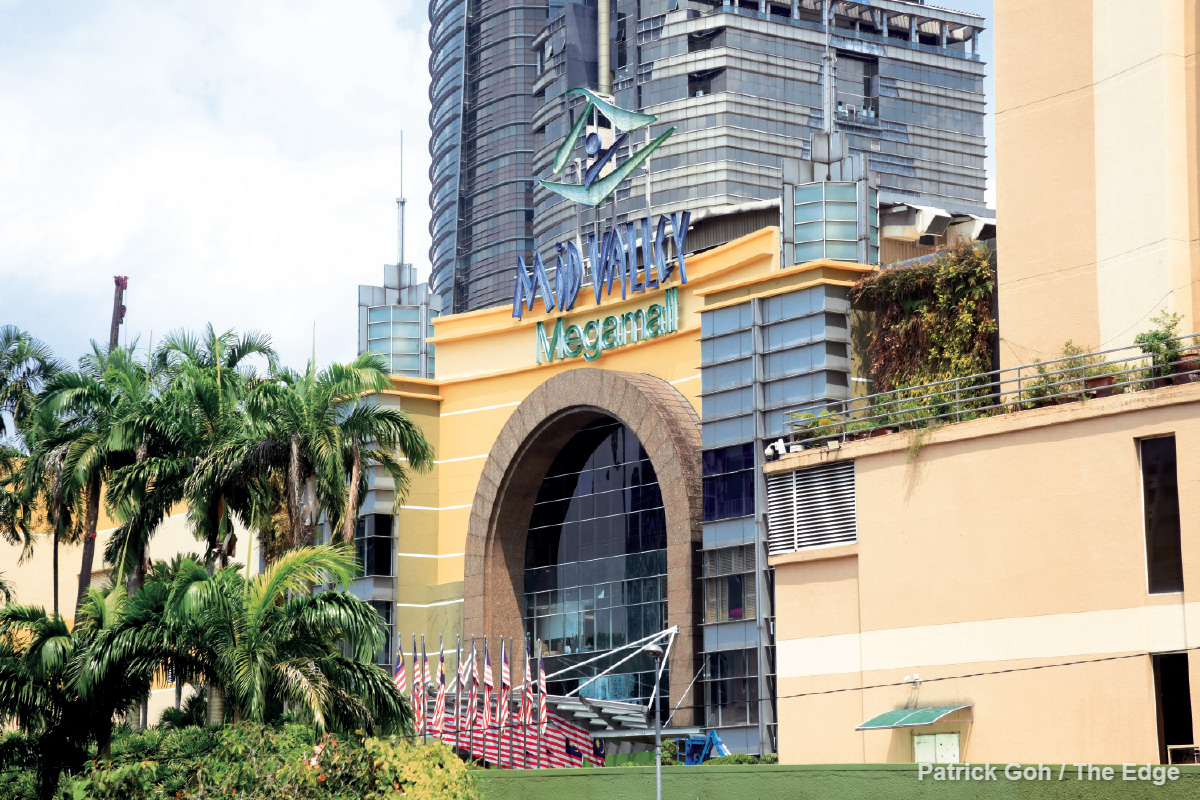
The most significant change for IGB REIT in recent years has been the addition of Mid Valley Southkey in Johor Bahru, which marks its first investment outside the Klang Valley, following the completion of the asset in November 2025.
This brought the total number of assets in its portfolio to three, alongside Mid Valley Megamall and The Gardens Mall in Kuala Lumpur.
Southkey has broadened IGB REIT’s exposure beyond Kuala Lumpur at a time when Johor is attracting greater investment and cross-border activity, helped by the Johor-Singapore Special Economic Zone (JS-SEZ) and the upcoming Johor Bahru-Singapore Rapid Transit System (RTS).
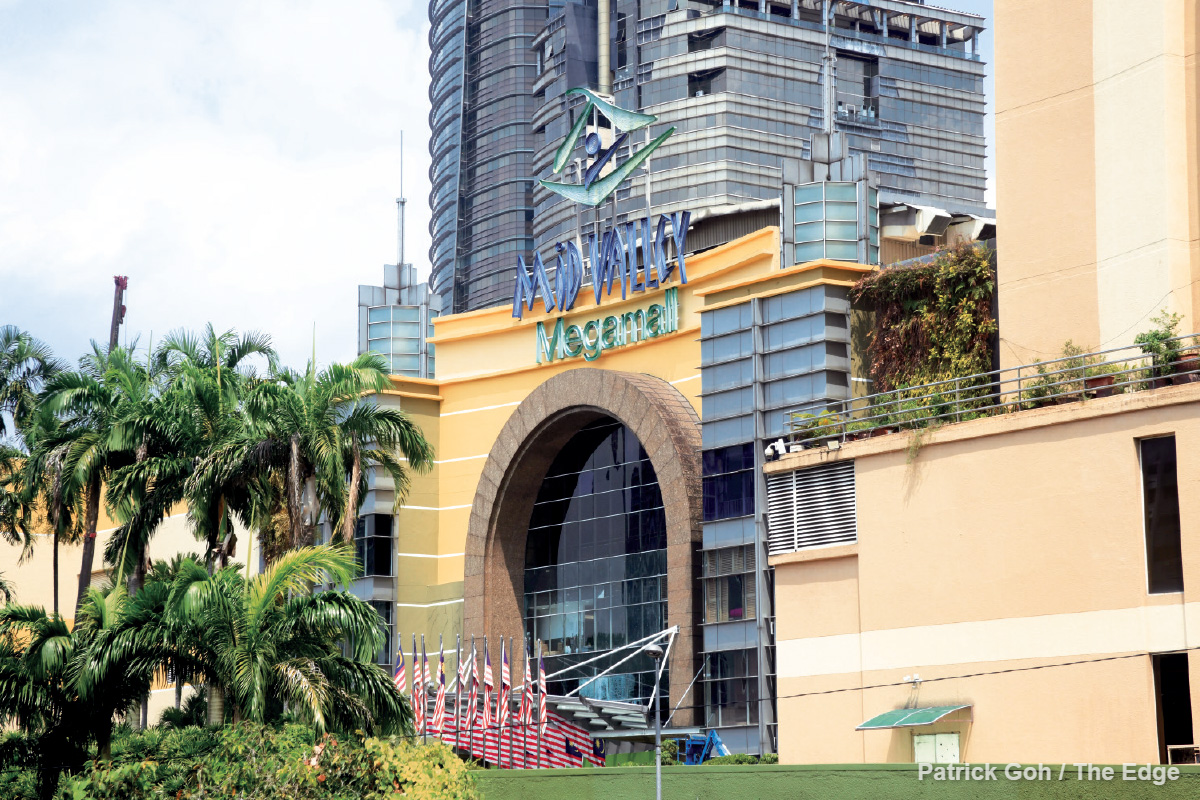
As at end-2025, IGB REIT’s three malls had a combined net lettable area of about 4.19 million sq ft and an appraised value of RM8.38 billion. Mid Valley Megamall was valued at RM4.08 billion, The Gardens Mall at RM1.5 billion and Mid Valley Southkey at RM2.8 billion. Occupancy stood at 99.8%, 99.1% and 100% respectively.
Notably, the expanded portfolio has lifted the trust’s 2026 numbers. For 1HFY2026, NPI jumped 53.4% year on year to RM388.2 million. IGB REIT attributed the increase to contributions from Mid Valley Southkey as well as higher rental income from Mid Valley Megamall and The Gardens Mall.
The performance comes against a retail environment in which consumers remain selective. Higher living costs continue to influence discretionary spending, while retailers are dealing with operating-cost pressures and changing shopping habits.
Nevertheless, IGB REIT expects Malaysia’s retail sector to remain resilient in 2026, supported by domestic economic growth, tourism and stable employment. Management has said it will continue to focus on maintaining high occupancy, securing sustainable rental growth through proactive leasing and improving its tenant mix.
There is also further room for rental growth. In a report on July 23, Kenanga Research said it expects healthy rental reversions at Mid Valley Megamall and The Gardens Mall, while Mid Valley Southkey could lift FY2026 DPU by up to 15% and give IGB REIT greater exposure to Johor’s growth, including the JS-SEZ and RTS Link. The research house maintained its “market perform” call on the stock and target price of RM2.81.
Similarly, Hong Leong Investment Bank Research said Mid Valley Southkey remains a key earnings catalyst ahead of the RTS Link opening, with management having significant scope to renew leases at higher rental rates as tenancy expiries increase over the next two financial years.
Meanwhile, MBSB Research — which upgraded IGB REIT to “buy” from “neutral” with a higher target price of RM2.90 — revised upward its earnings forecasts for 2026 to 2028 by between 6.4% and 7.8%, on stronger-than-expected rental income and improving long-term fundamentals.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.