

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Maxis Bhd
Maxis Bhd (KL:MAXIS) takes home The Edge Billion Ringgit Club (BRC) corporate award for highest return on equity (ROE) over three years this year — ending a five-year drought from the winners’ list.
While Maxis was previously recognised for stellar ROE under the Super Big Cap (market capitalisation above RM40 billion) for five straight years between 2016 and 2020 before dropping below the radar, this is the first time Maxis is taking home the ROE corporate award for the Telecommunications & Media sector.
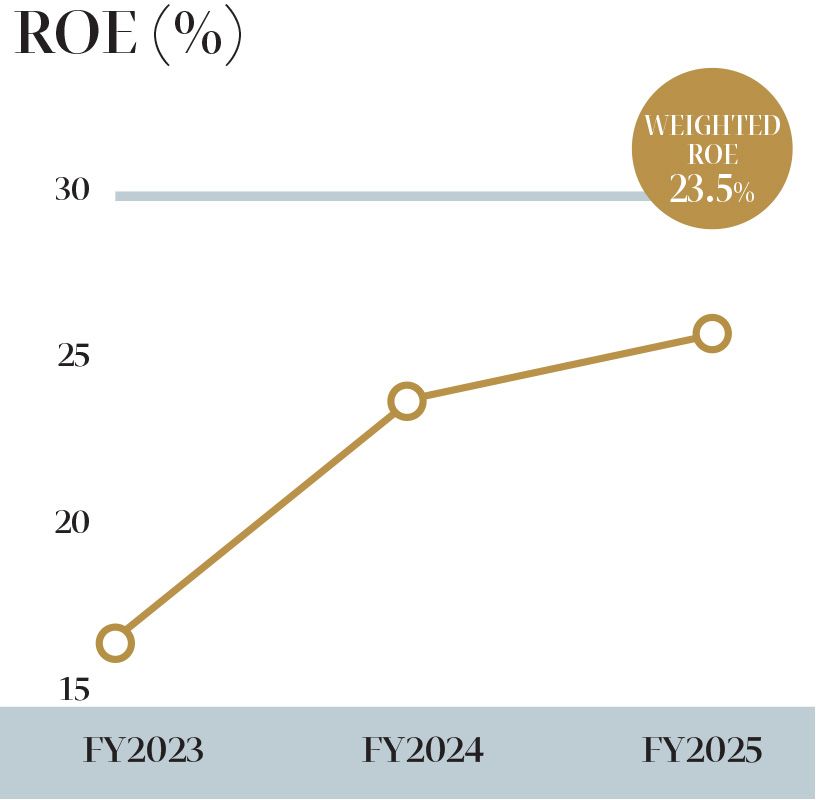
Its ROE improved from 16.8% in FY2023 to 24% in FY2024 and 25.9% in FY2025, translating into a stellar three-year weighted average of 23.5% — enough to clinch The Edge BRC corporate award for highest ROE over three years.
This came even as its profit after tax, which slipped from RM1.15 billion in the financial year ended Dec 31, 2022 (FY2022) to RM993 million in FY2023, recovered to RM1.4 billion in FY2024 and RM1.56 billion in FY2025 — translating into a risk-weighted profit after tax growth of 10.7% per year over three years, according to the BRC corporate awards methodology.
Its share price, which had slipped from RM4.50-levels in 2022 to around RM3.50-levels at the time of writing, is likely a source of consternation.
Dividend per share (DPS) had improved to 17.5 sen in FY2025 from 17 sen in FY2024 and 16 sen in FY2023 but is still below FY2022’s 20 sen.
Dividend was eight sen per share or RM626 million in the first half of FY2026 (1HFY2026), the same as the previous corresponding period. “As we expected, Maxis kept its 2QFY2026 DPS at four sen (2QFY2025: four sen), with any excess cash typically paid out as special DPS only in 4Q each year,” CIMB Securities analyst Foong Choong Chen wrote in an Aug 14 note.
Maxis’ net profit for 1HFY2026 of RM853 million improved 10.9% year on year (y-o-y) from RM769 million on the back of a 4.2% improvement in revenue to RM5.39 billion versus RM5.17 billion driven by a 2.5% growth in its consumer business and 3.7% growth in its enterprise business.
“Our second-quarter results reflect our approach to the business, combining steady top-line performance with operating discipline to accelerate profit growth. We continue to drive margin expansion through focused execution across the business,” Maxis CEO Goh Seow Eng said in an Aug 14 statement accompanying its quarterly earnings release.
“As we complete a solid first half, our full-year guidance remains unchanged at low single-digit growth in service revenue and Ebitda (earnings before interest, tax, depreciation and amortisation), with capex (capital expenditure) intensity between 10% and 12%. Across the remainder of the year, we remain focused on leveraging our integrated network to create value for consumers and power businesses, while delivering sustainable long-term growth for our shareholders,” Goh added.
Net debt to Ebitda levels decreased from 1.97 times as at end-December 2025 to 1.92 times as at end-June 2026 as Ebitda rose and net debt eased to RM8.47 billion from RM8.52 billion.
In notes accompanying its second-quarter earnings release, Maxis said: “Amid a highly competitive telecommunications landscape, Maxis remains focused on driving long-term sustainable growth by streamlining operational efficiencies while simultaneously elevating customer experiences through service innovation and superior network reliability.”
CIMB’s Foong expects Maxis’ core earnings per share (EPS) to grow quarter on quarter in 3QFY2026 on higher revenue and continued cost containment. On an annual basis, he expects core net profit (CNP) to grow by a decent 4% y-o-y in FY2026, driven by a 2% service revenue growth, alongside 0.3 percentage points Ebitda margin improvement stemming from cost optimisation initiatives.
“For FY2027, we project CNP to ease by a manageable 3% y-o-y, mainly owing to the full-year impact of equity accounting for Digital Nasional Bhd (DNB). Ex-DNB, we forecast CNP will grow 4% y-o-y, supported by sustained service revenue growth of 2% y-o-y,” Foong told clients in a recent note.
“Despite cost optimisation, we have assumed stable Ebitda margins, after considering the growth in 5G wholesale fees. We are not concerned about this increase in wholesale costs, as it essentially reflects a capex to operating expenditure (opex) shift in the 5G era, with Maxis’ capex expected to drop 8% y-o-y to RM1.1 billion in FY2027. In FY2028, we foresee Maxis’ CNP rebounding 6% y-o-y, driven by a gradual reduction in depreciation (with capex declining 14% y-o-y to RM950 million) and a step down in the share of DNB’s net loss (owing to major cost reductions alongside 5G wholesale revenue growth),” he added.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.