

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Frontken Corp Bhd
Frontken Corp Bhd (KL:FRONTKN) is no stranger to The Edge Billion Ringgit Club (BRC) Awards, having built a strong financial track record among Bursa Malaysia’s technology companies.
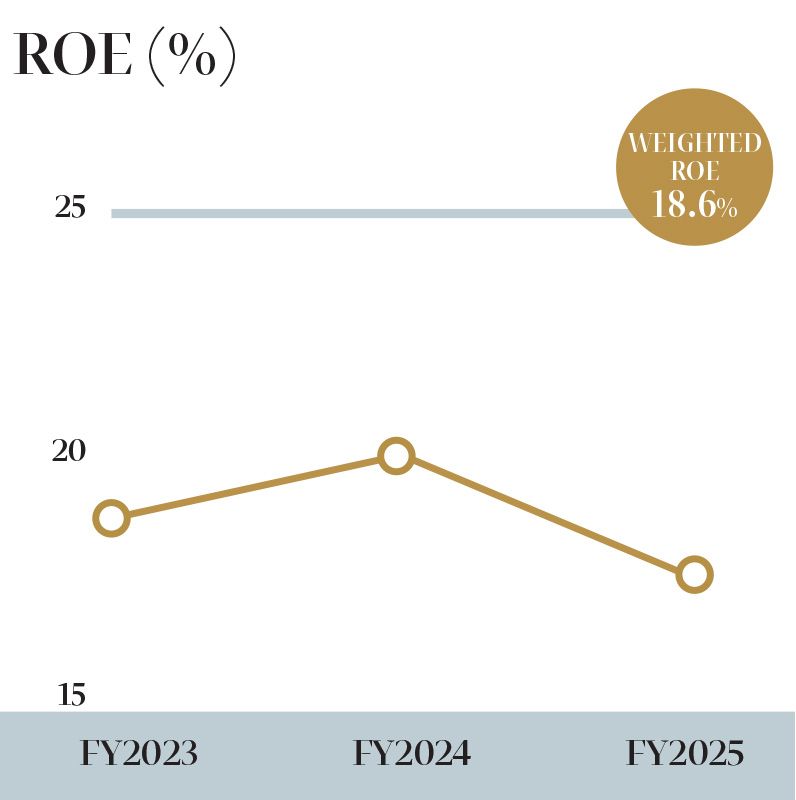
The precision engineering specialist has received yet another accolade, clinching the award for Highest return on equity (ROE) over three years in the technology sector at the 2026 awards.
Since its maiden win in 2019, the group has brought home eight trophies in total. It was even named Company of the Year in 2022.
For the latest award, Frontken was recognised for its solid ROE of 18.8% in the financial year ended Dec 31, 2023 (FY2023), 20.1% in FY2024 and 17.6% in FY2025, translating into a three-year adjusted weighted average ROE of 18.6% under the awards methodology.
This was driven by its continued record-breaking financial results underpinned by growing demand for its services from the semiconductor industry. Its FY2025 revenue of RM607.76 million was the highest since its listing on Bursa Malaysia in 2006, representing a five-year compound annual growth rate (CAGR) of 10.5% from RM368.32 million in FY2020.
Net profit grew at a faster five-year CAGR of 13.4% to RM154.23 million in FY2025 — also a record high. Meanwhile, net profit margin widened from 22.25% in FY2020 to 25.38% in FY2025, reflecting improved operational efficiency and a better mix of higher-margin jobs.
Frontken is a leader in precision cleaning and coating services, particularly for the semiconductor industry. The Taiwan market accounts for about 62% of the group’s revenue, with Taiwan Semiconductor Manufacturing Co (TSMC) contributing roughly one-third, positioning Frontken to benefit from the sustained ramp-up of advanced semiconductor nodes.
The shift towards advanced nodes is also deepening its role in the semiconductor manufacturing ecosystem as chipmakers increasingly rely on precision cleaning and coating to support higher process yields and equipment uptime.
“The structural drivers of semiconductor demand including digitalisation, electrification, artificial intelligence and advanced manufacturing continue to support long-term industry growth. At the same time, increasing process complexity and tighter contamination standards further reinforce the value of our services within the ecosystem,” Frontken said in its FY2025 annual report.
JPMorgan, which has an “overweight” rating on the stock, noted that Frontken plays a key role in helping chipmakers minimise chamber downtime, reduce maintenance frequency and extend component life. It added that the group offers investors indirect exposure to front-end semiconductor manufacturing without the associated high capital expenditure.
Meanwhile, UBS Research observed that revenue from Frontken’s Taiwan operations has grown almost 2.5 times since 2019, outpacing its 1.7 times growth in floor space. While this could partly reflect better process yields, it noted that floor space is increasingly becoming a constraint for Frontken to scale production further.
In response, the group is embarking on an accelerated capacity expansion programme, with three new plants either under development or being brought online, alongside further expansion at its existing Plant 1. Plant 2 is expected to begin low-volume production in September, while Plant 3 and Plant 4 are targeted to support growth from late 2026 and 2028 respectively. A potential Plant 5 could provide further upside.
The accelerated capital expenditure programme points to stronger demand visibility, particularly in Taiwan and Singapore, which are expected to remain key earnings drivers through FY2026 and FY2027.
Crucially, management has indicated that future capacity expansion is backed by customer demand, suggesting that underlying demand for wafer fabrication equipment precision cleaning and surface treatment services remains robust.
Beyond capacity expansion, Frontken’s strengthened balance sheet also gives it greater financial firepower for its next phase of growth, including pursuing overseas expansion, although management remains disciplined on large-scale acquisitions.
The US market is likely to be approached through joint ventures or smaller-scale investments, while Japan is viewed as a more strategically attractive market, according to Frontken.
“The group will continue to prioritise operational efficiency, automation and selective capacity expansion to support customer ramp-ups while maintaining margin discipline. Investment decisions will remain measured and aligned with demand visibility to support sustainable growth,” it said.
A warrant conversion in 2026 has boosted its cash holdings to RM1.52 billion, from RM841.13 million.
Market confidence in Frontken remains high. All eight analysts covering the group have “buy” calls, with target prices ranging from RM5.04 by Berjaya Research to RM6.10 by Macquarie Research, averaging RM5.69. This implies a potential upside of 11.8% from its closing price of RM5.09 on Aug 28.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.