

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Telekom Malaysia Bhd
As the backbone of the nation’s digital infrastructure, Telekom Malaysia Bhd (KL:TM) has been well positioned to benefit from the sustained growth in data consumption and the rising influx of data centre investments.
In 2025, the group continued to expand its data centre capacity, scale up its submarine cables, grow its graphics processing unit (GPU)-as-a-service, and continued to bolster Malaysia’s digital infrastructure, cementing its leading position in the telecommunications and media sector.
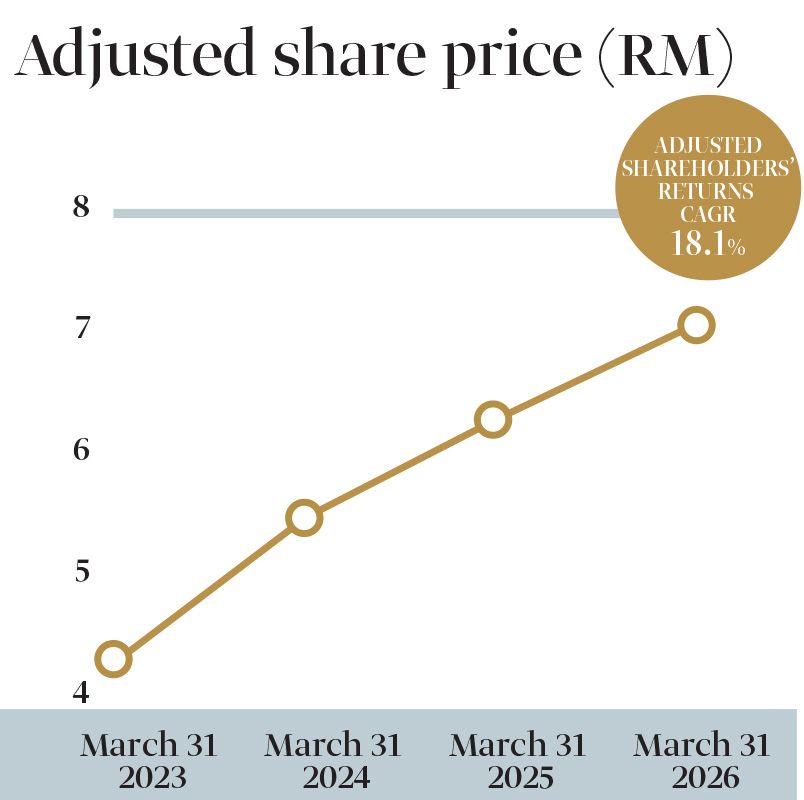
As TM recorded solid earnings over the years, its shares have been on a steady climb. From RM4.31 at end-March 2023, the counter surged to RM7.10 at end-March 2026 — translating into 18.1% in shareholder returns at a three-year compound annual growth rate (CAGR).
The compelling shareholder returns saw TM clinch The Edge Billion Ringgit Club (BRC) award for Highest returns to shareholders over three years in the telecommunications and media sector.
One contributing factor is its consistent dividend payments, which further gained traction after the group raised its dividend policy earlier this year to a minimum of 75% of its reported profit after tax and non-controlling interests.
TM was established in 1946 as the Malayan Telecommunications Department to lay the foundation for the country’s modern connectivity. Today, TM is a telecommunications behemoth at the forefront of shaping Malaysia’s telecommunications landscape and accelerating the growth of the digital economy.
The group has identified growth areas such as cloud, data centres, cybersecurity, digital services and regional connectivity, in its ambition to become a digital powerhouse by 2030 under its PWR 2030 strategy.
This as TM seeks to reduce its reliance on conventional connectivity growth as Malaysia’s broadband market matures.
In its 2025 annual report, TM said competition was increasingly shifting from first-time connectivity towards service quality, convergence, customer experience and wallet share.
Unifi remains a key part of this plan. TM said Unifi has continued to position itself as Malaysia’s convergence leader, with its quad-play offering combining broadband, digital television, fixed line and mobile network, and its UniVerse ecosystem supporting the consumer business.
Business-to-consumer (B2C) revenue remained resilient with 0.7% year-on-year (y-o-y) growth in FY2025, despite intense competition and high market penetration, helped by value-based monetisation, higher convergence adoption and an improved customer mix.
At the same time, TM has been expanding its digital infrastructure footprint to capture rising demand driven by cloud computing and artificial intelligence (AI).
At end-2025, the group had more than 750,000km of domestic fibre-optic cables, an international network of more than 400,000km across 39 submarine cable systems, and six data centres, comprising five domestically and one in Hong Kong.
The result is solid financial performance in the three years under review. Net profit rose from RM1.14 billion in the financial year ended Dec 31, 2022 (FY2022) to RM1.87 billion in FY2023 and RM2.02 billion in FY2024, before moderating to RM1.71 billion in FY2025 — translating into a risk-weighted CAGR of 14.4%.
Going into 2026, its earnings momentum moderated as it took “bold but necessary strategic actions in the first half to strengthen TM’s efficiency, competitiveness and profitability in the long run”, said Telekom Malaysia group CEO Datuk Amar Huzaimi Md Deris.
Net profit in 1HFY2026 declined 14.6% y-o-y to RM687 million, as higher operating costs — including expenses related to its employee voluntary separation programme Prihatin and sponsorship of the Fifa World Cup 2026 — offset a 4.8% rise in revenue to RM5.9 billion.
That said, TM declared a second interim dividend of seven sen per share, bringing the year-to-date payout to 13.50 sen per share, higher than the 12.50 sen in the same period a year earlier.
With its attractive dividend yield, growth prospects linked to connectivity and AI, as well as the solid breadth of its products and segments among telecommunication companies, TM remains well liked by analysts.
Of the 21 analysts covering the stock, 13 have “buy” recommendations and six have “hold” calls while only two have a “sell” recommendation at the time of writing. The median 12-month target price stands at RM8.60 at the time of writing.
Earnings are also expected to pick up in the second half of 2026 as the first phase of TM’s data centre, TM Nxera, in Iskandar Puteri, Johor, is slated for completion in the third quarter of 2026, analysts said. About 70% of capacity has already been contracted.
For investors, there is plenty to cheer about. TM shares scaled a fresh record high of RM8.18 on Sept 9, and with cost rationalisation efforts well underway and its earnings trajectory expected to improve, the group’s best days may still lie ahead.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.