

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
CIMB Group Holdings Bhd
Despite an increasingly challenging banking landscape, CIMB Group Holdings Bhd (KL:CIMB) has continued to set new earnings benchmarks, hitting a record net profit in 2024 before surpassing it with a fresh record in 2025.
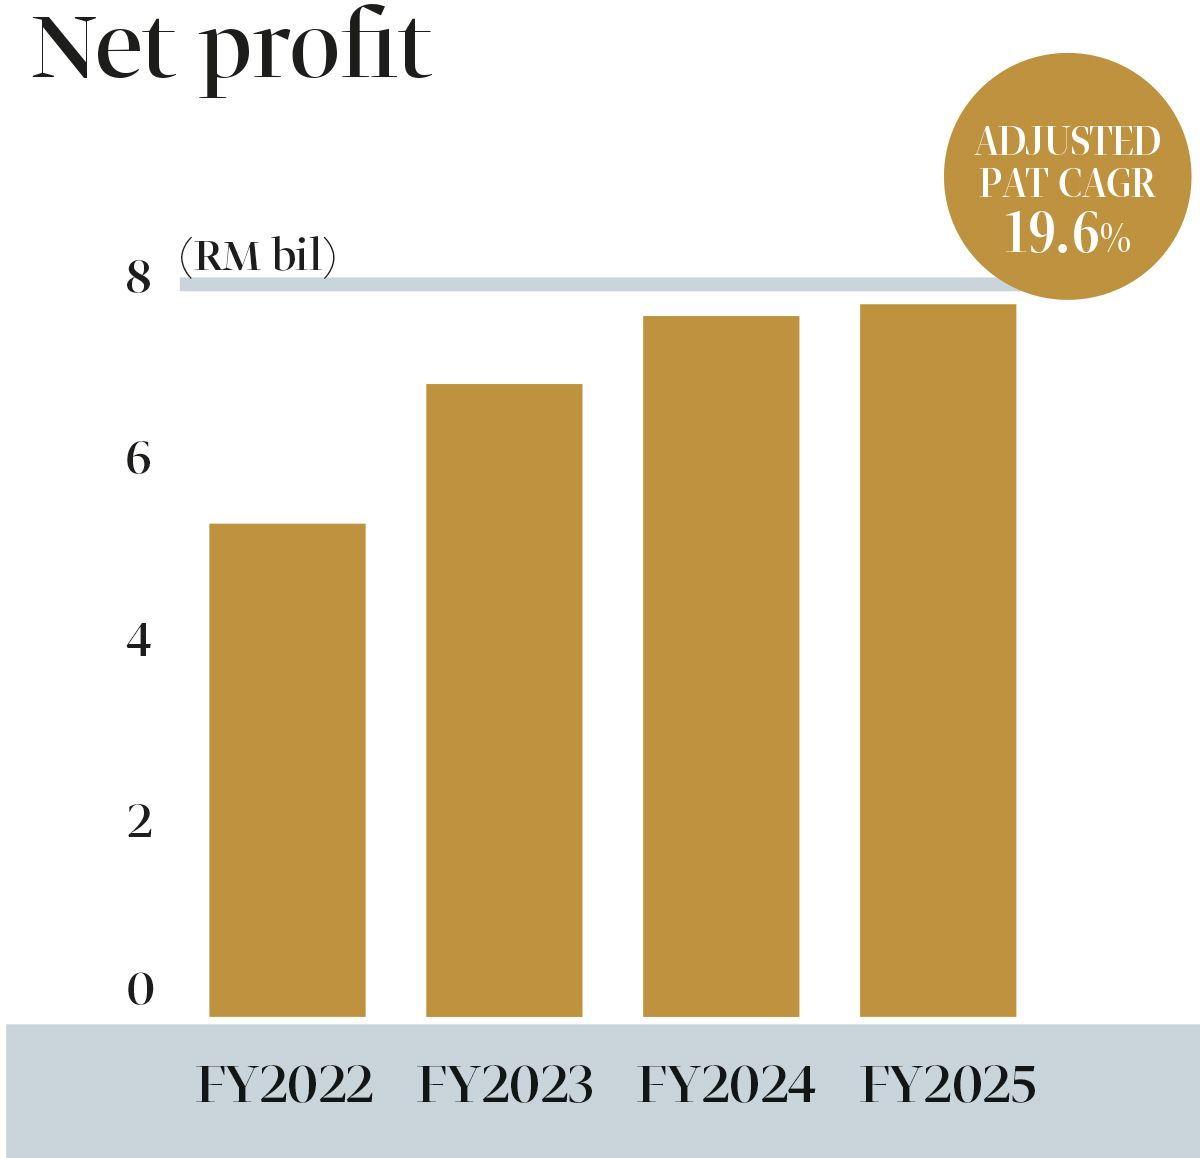
Net profit at the country’s second largest banking group and Asean’s fifth largest by assets rose 1.7% to RM7.86 billion in the financial year ended Dec 31, 2025 (FY2025), from RM7.73 billion a year earlier. That followed a 10.7% increase in FY2024 and a much sharper 28.3% jump in FY2023 to RM6.98 billion.
The steady rise in earnings translated into a risk-weighted compound annual growth rate (CAGR) of 19.6% over the three years — the highest among its peers.
This made CIMB this year’s winner of The Edge Billion Ringgit Club (BRC) award for Highest growth in profit after tax over three years in the financial services sector, among banks that have a market capitalisation of at least RM10 billion. It also won in the BRC Super Big Cap category for companies with a market capitalisation of above RM40 billion.
It is the third year running that CIMB has won in both categories, marking how far the group has come since the Covid-19 pandemic. Its return on equity (ROE) improved from 10.7% in 2023 to 11.2% in 2024 and 11.3% in 2025, from just 9% in 2022.
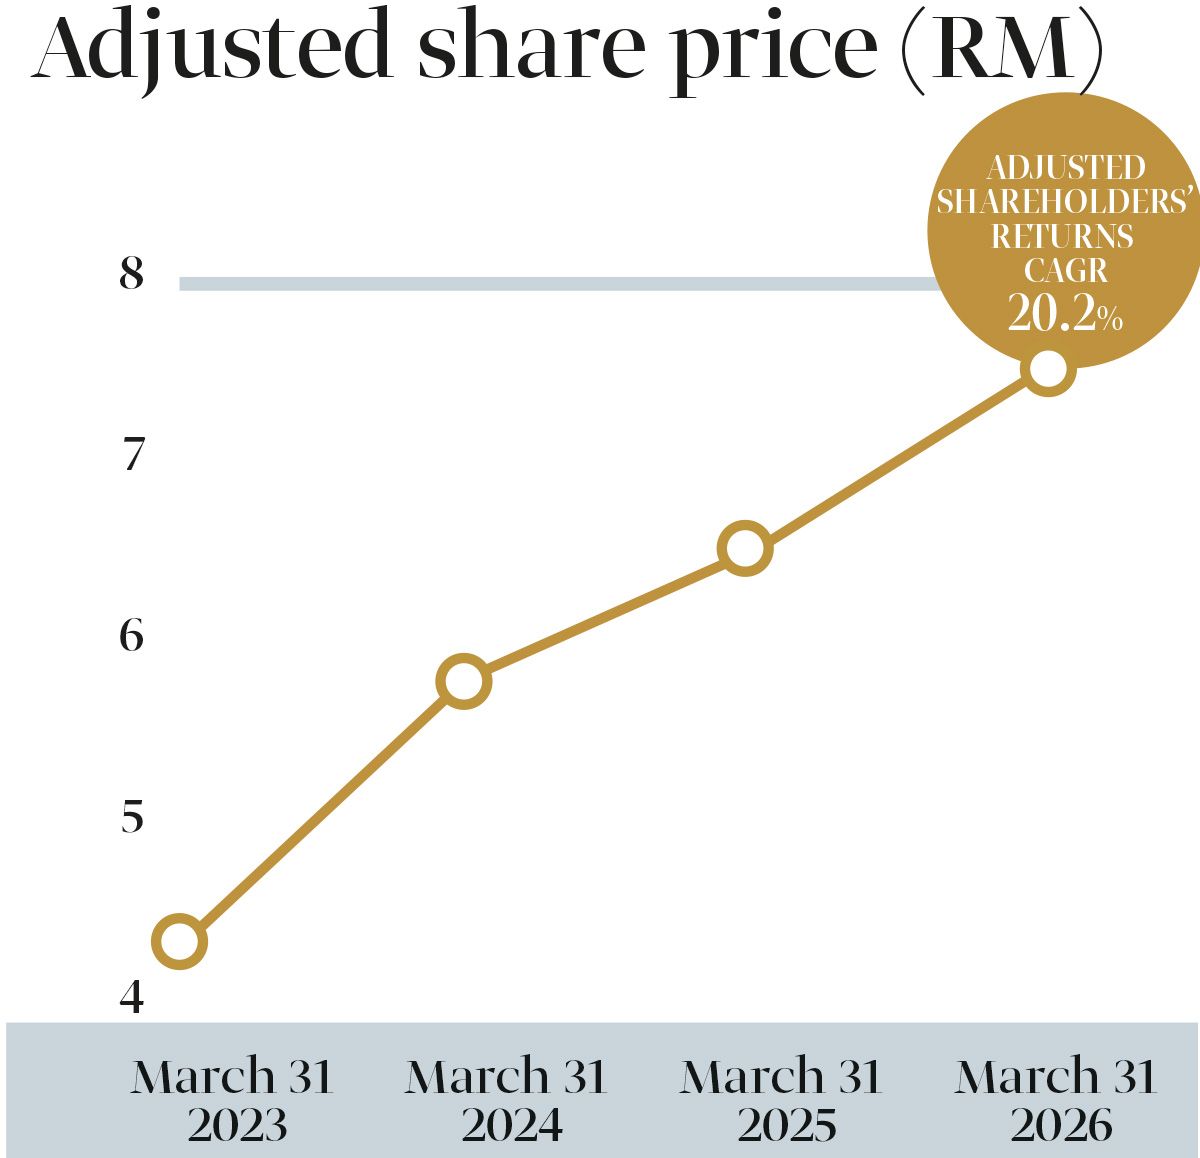
Thanks to its strong share price appreciation and attractive dividends, CIMB also clinched this year’s award for highest returns to shareholders over three years in the Super Big Cap category for companies with a market cap of over RM40 billion.
CIMB’s shareholder returns grew at a CAGR of 20.2% over the three years — ahead of the competition — as its share price shot up to RM7.55 on March 31, 2026, from RM4.35 on March 31, 2023.
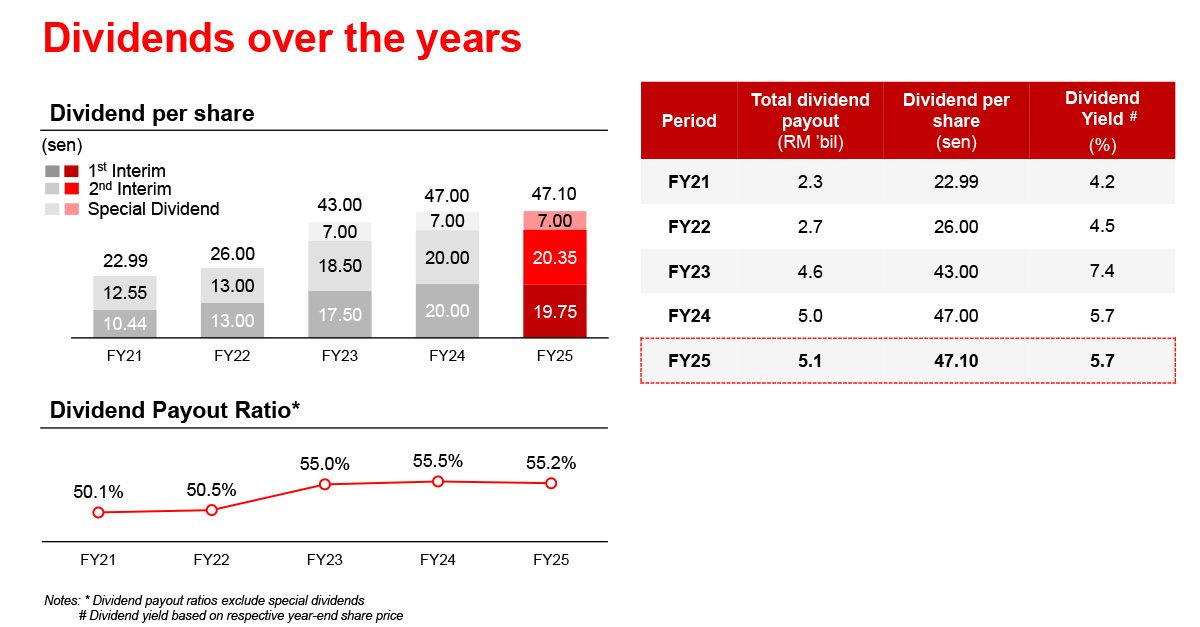
The returns reflect the higher dividends that shareholders received as profits grew. CIMB increased its dividend per share from 43 sen in 2023 to 47 sen in 2024, before declaring 47.1 sen for FY2025. Each year’s payout included a special dividend of seven sen per share. The latest payout amounted to a record of about RM5.1 billion.
Supporting its share price is the fact that the group has committed to returning up to RM2 billion of additional capital to shareholders by 2027 through special dividends and/or share buybacks, subject to market conditions and regulatory approvals.
This year, given a more challenging macroeconomic backdrop, including a prolonged conflict in the Middle East macroeconomics, CIMB’s 1HFY2026 financial performance softened from the previous corresponding period. Net profit for the period fell a marginal 0.2% year on year (y-o-y) to RM3.85 billion, while revenue slid to RM10.97 billion from RM11.10 billion.
Be that as it may, it delivered an annualised ROE of 11%, in line with its target of 11% to 11.5% for the full year. It announced an all-cash first interim dividend of 19.65 sen per share, based on a consistent payout ratio of 55.5%, which translated into a total dividend payout of RM2.1 billion.
Notably, asset quality remained broadly stable, with its gross impaired loan ratio at an all-time low of 1.6% at end-June, compared with 1.7% three months earlier.
Group CEO Novan Amirudin said the execution momentum for Forward30 — the group’s six-year strategic programme that started running from last year — remained firmly on track.
“Our destination is clear: to become the top-of-mind Asean bank by 2030. To get there, we must deliver a sustainable ROE of 12% to 13% by 2027 and compete consistently in the top quartile of our regional peers by 2030,” he said in the group’s latest annual report.
Nevertheless, headwinds persist, and the group expects funding cost pressures in Indonesia and competition on loan repricing to weigh on its net interest margin (NIM) this year. CIMB’s NIM stood at 2.04% in 2QFY2026, down four basis points from the previous quarter and down 11bps on a y-o-y basis.
A notable development this year is that CIMB’s Thai unit, CIMB Thai Bank, was delisted from the Stock Exchange of Thailand on Sept 12, more than 2½ years after a regulatory process triggered by stricter free-float requirements. CIMB Thai remains a core subsidiary and the delisting is not expected to have a material impact on the lender. The Thai unit is profitable, having posted more than a fivefold y-o-y increase in net profit to THB886.3 million in 2QFY2026.
As at Aug 28, CIMB’s share price closed at RM7.96, giving the company a market value of RM86.05 billion. Bloomberg data shows 15 “buy” and five “hold” recommendations on the stock, with no “sell” calls. The 12-month average target price was RM8.88.
“CIMB has balance sheet flexibility to navigate NIM pressure, and loan loss coverage buffers to weather any asset quality turbulence,” AmInvestment Bank Research said in a Sept 1 report. “The bank has also consistently proved itself as a strong strategy executor and good capital allocator. Besides, we like CIMB’s stance on returning excess capital, with scope for more beyond the planned RM2 billion programme, especially when its dividend payout ratio is about 10 percentage points below larger peers.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.