

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
Nestlé (Malaysia) Bhd
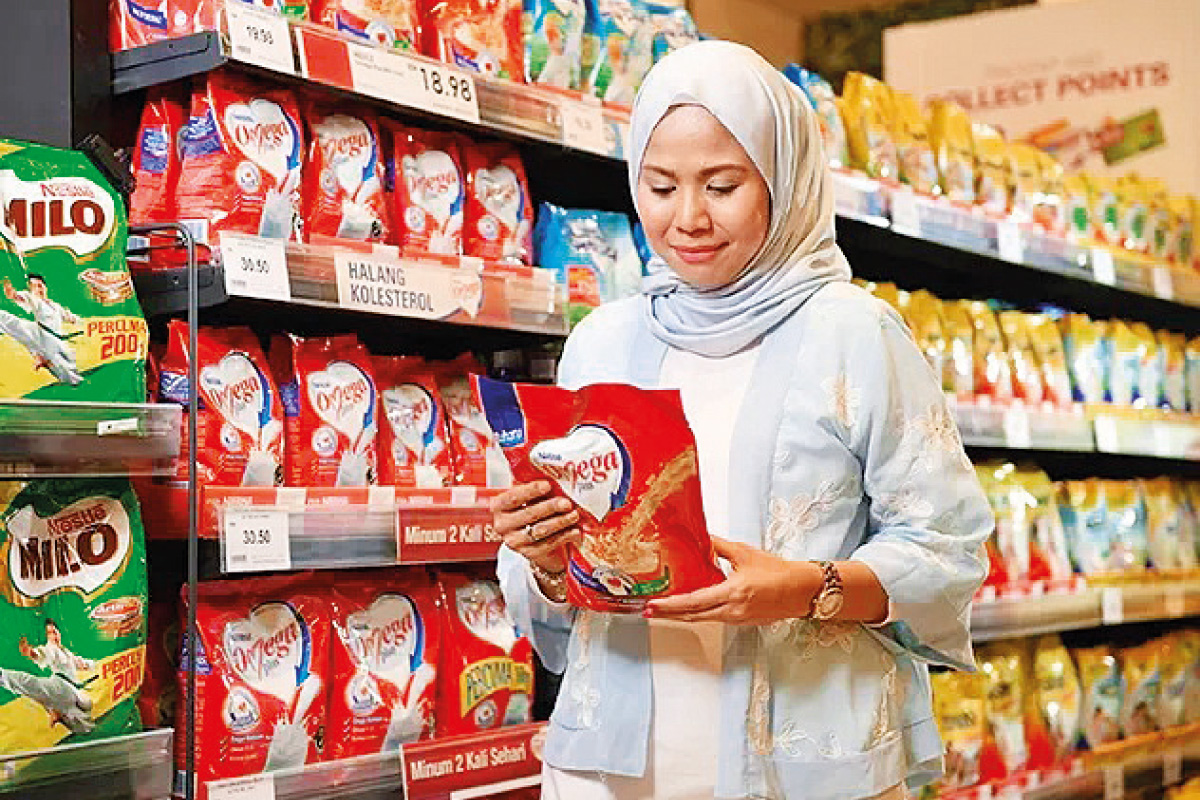
Nestlé (Malaysia) Bhd (KL:NESTLE) may have weathered a sharp downturn in consumer demand and elevated commodity costs over the past three years, but its ability to generate returns for its investors remains difficult to match.
For the fourth year running, the maker of household brands such as Milo, Maggi and Nescafé clinched The Edge Billion Ringgit Club (BRC) award for Highest return on equity (ROE) over three years in the big cap category of companies with a market capitalisation of between RM10 billion and RM40 billion.
The latest win extends Nestlé Malaysia’s long record at the BRC, following its Company of the Year award in 2016, as well as Best Corporate Responsibility awards in 2012 and 2021.
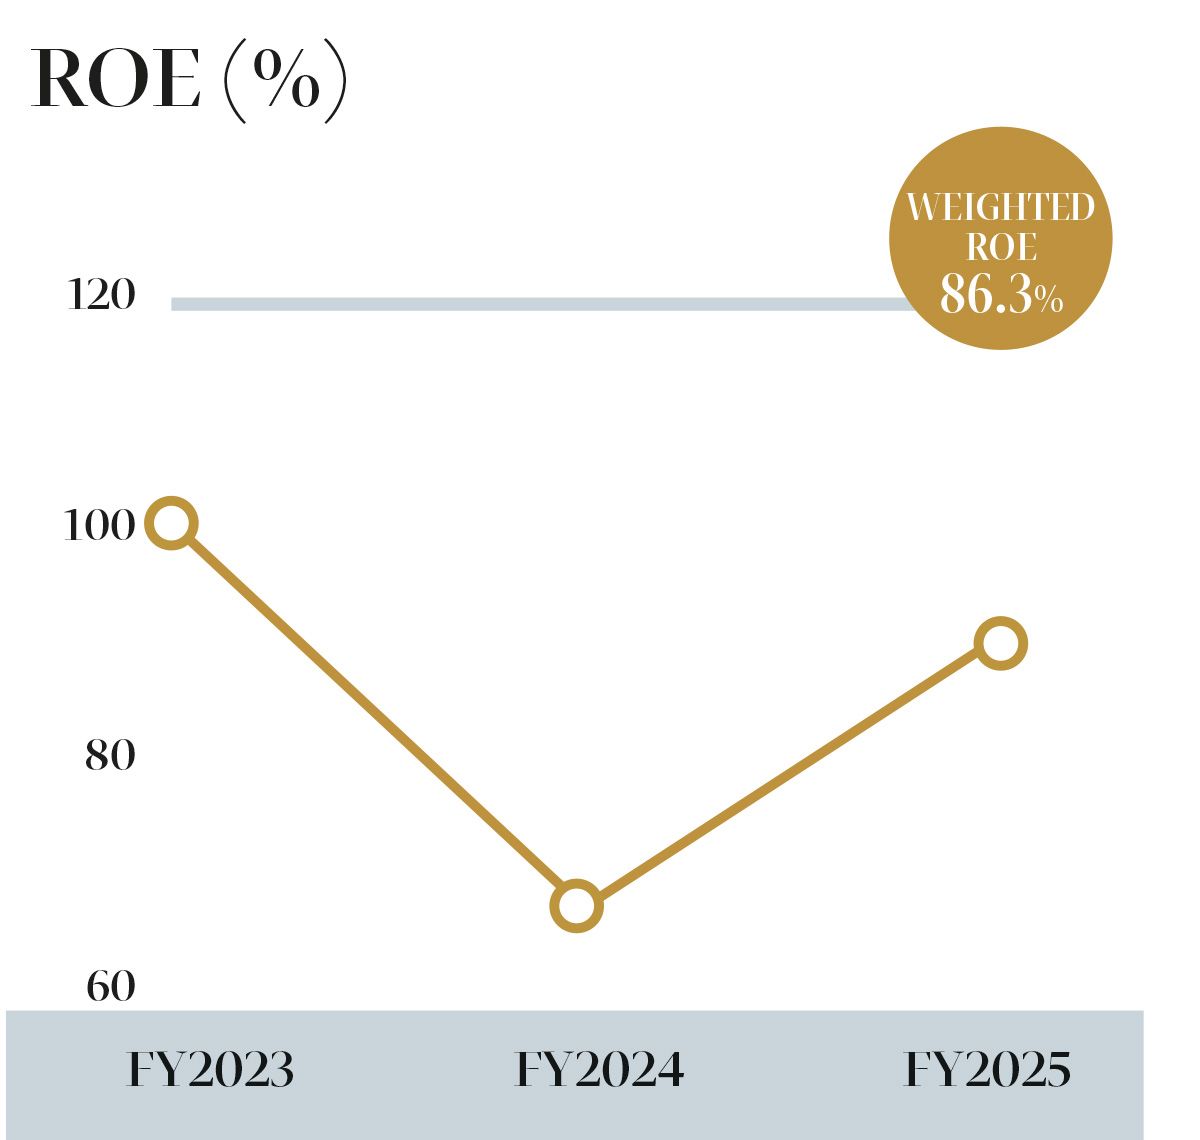
The group delivered an adjusted weighted ROE of 86.3% over the financial year ended Dec 31, 2023 (FY2023) to FY2025, based on an annual ROE of 101.4% in FY2023, 68% in FY2024 and 91.3% in FY2025.
The recovery comes after a difficult FY2024. Following a record net profit of RM659.9 million in FY2023, the group’s net earnings fell to RM415.6 million before recovering to RM513 million.
Revenue followed a similar trajectory, declining from a record RM7.1 billion in FY2023 to RM6.2 billion in FY2024 before recovering to RM6.9 billion in FY2025.
The recovery was more pronounced in FY2025, with both domestic sales and export sales gaining momentum. Exports revenue expanded to RM1.67 billion from RM1.43 billion in FY2024.
As a result, the group rewarded its shareholders with higher dividends of RM2.20 per share in FY2025 compared with RM1.79 per share in FY2024.
The momentum has carried into FY2026. For 1HFY2026, Nestlé Malaysia’s net profit jumped 31.7% year on year to RM360.1 million as revenue increased 7.4% to RM3.69 billion. In 2QFY2026 alone, net profit climbed more than 38% to RM155 million on revenue of RM1.81 billion, up 8.7%, helped by broad-based sales growth, cost management and efficiency gains. It declared an interim dividend of 80 sen per share, against 70 sen last year.
Management is confident of delivering a robust performance for FY2026, although geopolitical uncertainty, commodity price movements and shifts in consumer behaviour remain risks. As coffee and cocoa costs have eased from elevated levels, alongside efficiency gains from automation, digitalisation and the use of artificial intelligence, management believes the group’s margins can remain resilient.
Nestlé Malaysia has also continued to invest in its local manufacturing and supply chain footprint. A notable development is the commencement of Nescafé Espresso Concentrate production at its Sri Muda factory in Shah Alam, Selangor, making the plant Nestlé’s first coffee-concentrate production site in Asia.
The product is targeted for both the Malaysian market and exports, including Singapore, Oceania, the Middle East and North Africa, with further markets planned. Nestlé Malaysia CEO Juan Aranols says the new product is aimed at young coffee drinkers and will create more jobs.
Over the past five years, Nestlé Malaysia has spent nearly RM1.5 billion to grow its business, underscoring Malaysia’s importance as the group’s largest halal manufacturing and export hub.
Its expansion plans include building a new integrated logistics hub worth RM250 million in Port Klang, Selangor. The facility is designed to centralise export warehousing and imported raw materials while improving automation, scale and supply-chain efficiency. Management says the hub is at an advanced stage of completion and is expected to become operational in the coming months.
The group is also upgrading its Milo plant in Chembong, Negeri Sembilan, and its Batu Tiga, Selangor, facilities.
As earnings recovered, Nestlé Malaysia’s adjusted share price rose to RM99.12 on March 31 this year from RM72.94 on March 28, 2025, although it remained well below RM129.10 on March 31, 2023.
Bloomberg data shows that of the 13 analysts covering the stock, nine have a “buy” call, three are calling “hold” and one a “sell”, with a consensus target price of RM114.01. This implies a 14% upside potential from its closing price of RM100.10 on Aug 28 this year which valued the group at RM23.47 billion.
Switzerland-based Société des Produits Nestlé SA controls a 72.61% stake in Nestlé Malaysia while the Employees Provident Fund holds 14.87% as at Sept 8, 2026.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.