

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
CelcomDigi Bhd
Returning to the winners’ list after a one-year hiatus, CelcomDigi Bhd (KL:CDB) takes The Edge Billion Ringgit Club (BRC) award for Highest growth in profit after tax over three years in the Telecommunications & Media sector this year.
Previously on the BRC winners list every year since 2012, CelcomDigi usually takes home the corporate award for return on equity (ROE) for both the sector as well as the BigCap (RM10 billion to RM40 billion market capitalisation) or SuperBigCap (above RM40 billion market cap) categories. This is its first win under the growth in profit after tax over three years’ category.
Digi.Com Bhd, which took its current name following its merger with Celcom Bhd on Nov 30, 2022, previously won The Edge BRC corporate award for shareholder returns more than a decade ago, around the time it was named The Edge Billion Ringgit Club Company of the Year in 2013. That means CelcomDigi operated as the merged entity only in the final month, or December 2022, giving the enlarged group the benefit of a lower base in this year’s awards that used actual reported figures rather than pro-forma numbers.
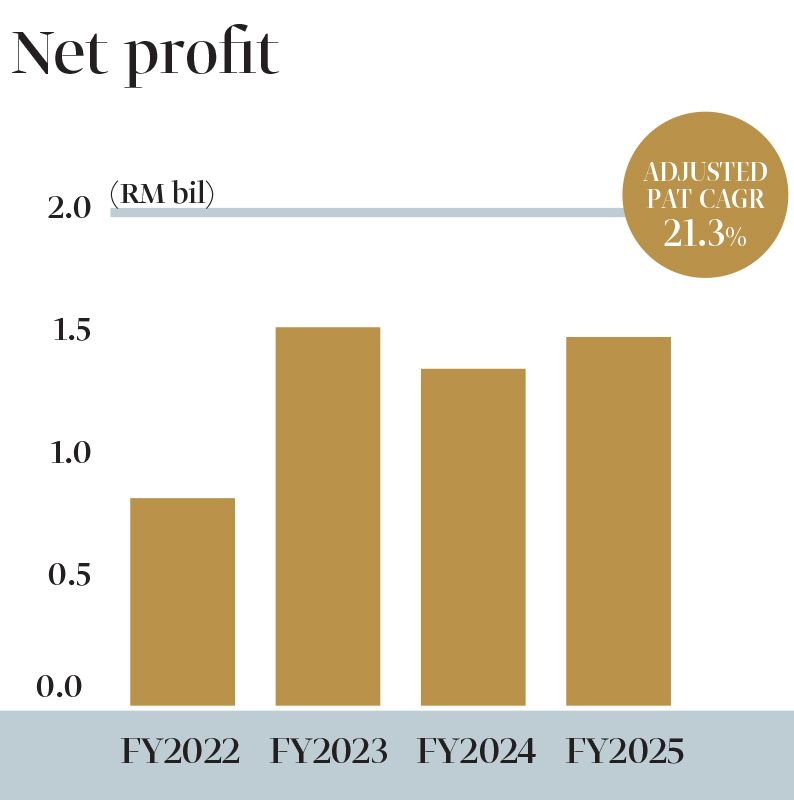
CelcomDigi’s net profit rose from RM848 million in the financial year ended Dec 31, 2022 (FY2022), to RM1.55 billion in FY2023, but skidded to RM1.38 billion in FY2024 before recovering to RM1.51 billion in FY2025. Still, based on the awards methodology, the numbers translated into a risk-weighted profit after tax growth of 21.3% a year over three years — enough to edge past peers in the Telecommunications & Media sector.
Adjusted weighted return on equity (ROE), which declined to 8.5% in FY2024 from 9.5% in FY2023, returned to 9.5% in FY2025, resulting in a three-year weighted average of 9.2% but not enough to clinch a second trophy this year.
Its share price performance over the three-year period, however, left much to be desired — having skidded from above RM4 levels in 2023 to below RM3 levels currently. CelcomDigi declared 14.7 sen dividend per share (DPS) in FY2025, up from 14.3 sen per share in FY2024.
In the first half of FY2026 (1HFY2026), DPS was 6.8 sen compared with 7.5 sen in 1HFY2025, even as net profit for 1HFY2026 came in at RM816 million, slipping 0.85% year-on-year from RM823 million in the previous corresponding period despite revenue inching higher by 0.1% y-o-y to RM6.34 billion.
When reporting earnings for its second quarter ended June 30, 2026 (2QFY2026), CelcomDigi said the group continued to make progress on its transformation initiatives, including a refreshed product portfolio with stronger value-based offerings and the delivery of its structural cost optimisation programme across the organisation.
“We are delivering our Operational Excellence programmes as planned, generating tangible savings and improving how we operate. This enables us to continue investing in priority areas, while sustaining healthy service revenue growth. As we move beyond integration, we remain focused on disciplined capital allocation and strategic investments in our network, digital capabilities, and customer experience,” CelcomDigi CEO Albern Murty said in a statement dated Aug 14.
“Operational Excellence savings remained on track for the year, with RM100 million realised in 2Q2026, bringing year-to-date savings for the first half of 2026 to RM141 million,” notes accompanying its earnings release read, adding that the savings were driven largely by lower leased-line costs, procurement efficiencies and improvements across infrastructure projects.
CelcomDigi has raised its FY2026 cost savings target slightly to RM470 million, from RM450 million previously, implying potential realisation of RM329 million in cost savings y-o-y in the second half of 2026, CIMB Securities analyst Foong Choong Chen wrote in a note dated Aug 14.
Moving into 2HFY2026, CelcomDigi says it “expects to deliver on its full-year operational efficiency targets and commence new approaches to address medium- to long-term structural costs”. The group aims to deliver sustainable service revenue growth and margin improvements for the rest of the year, leveraging its refreshed product portfolio and segmental focus.
CIMB’s Foong told clients that CelcomDigi’s consumer mobile revenue trend “may improve in 2H2026 as its revised prepaid offers (launched in late-January 2026) gradually yield-positive effects”.
CelcomDigi also says the new mandatory standards for the registration of end-users for prepaid pubic cellular services “will result in some near-term industry adjustments but will have a positive long-term impact when enforced effectively”. Ongoing cost optimisation and execution discipline will help mitigate geopolitical-related supply chain and energy cost pressures, it adds.
Investors are likely to be looking out for the impact of the impeding equity accounting of its 33.3% share of Digital Nasional Bhd’s (DNB) losses in 2HFY2026.
CelcomDigi says DNB “has embarked on its network modernisation programme, leveraging its strong spectrum portfolio, totalling 240MHz, for the next phase of value creation”. Together with other DNB shareholders, CelcomDigi says the enhancement of DNB’s performance, productivity and scalability is aimed at capturing long-term value from its 5G network investment.
“We foresee sustained service revenue growth of 3% y-o-y, a pickup in merger synergies, and a fall-off in integration costs (after completion of IT system consolidation in 2H2027), more than offsetting the full-year impact from equity accounting for DNB’s net loss. Excluding the share of DNB’s loss, we forecast core net profit to grow by 9% y-o-y,” says CIMB’s Foong, who has a “buy” call on CelcomDigi and RM3.65 target price.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.