

This article first appeared in The Edge Malaysia Weekly on October 5, 2026 - October 11, 2026
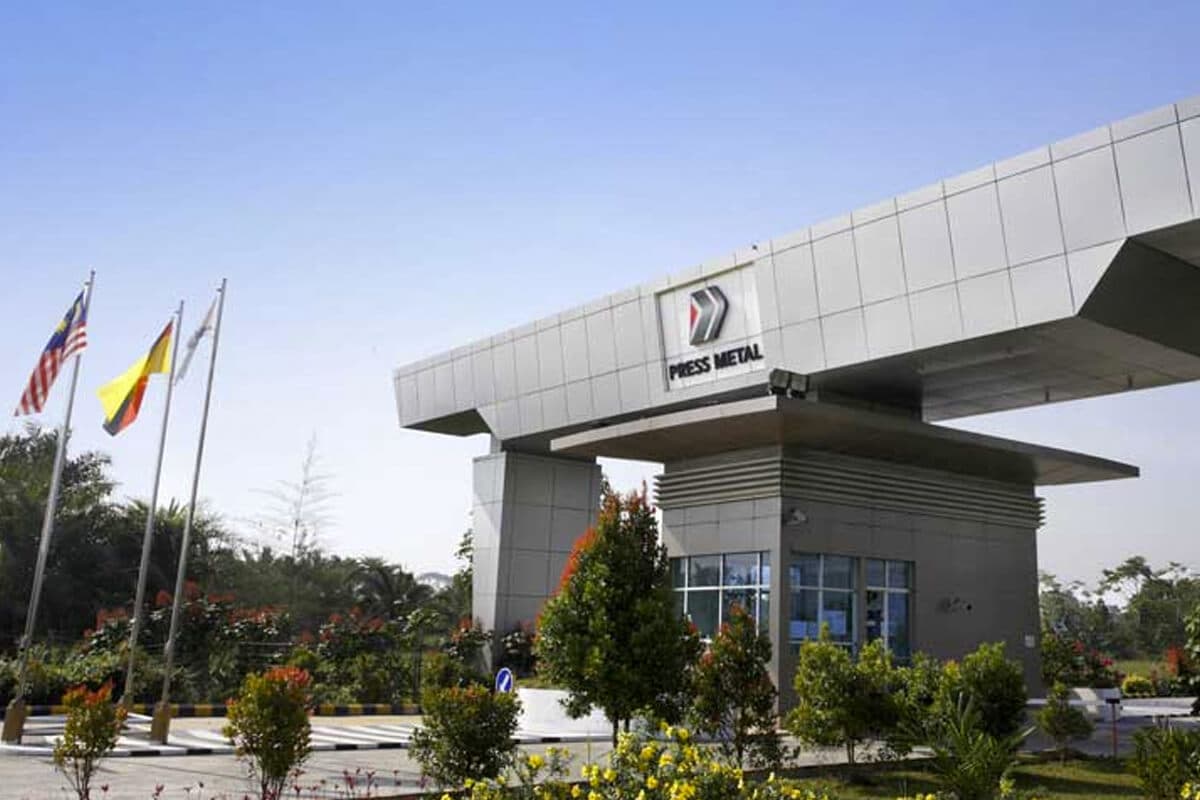
Press Metal Aluminium Holdings Bhd
Press Metal Aluminium Holdings Bhd (KL:PMETAL) — Southeast Asia’s largest integrated aluminium producer — is no stranger to The Edge Billion Ringgit Club (BRC) Awards. The continued tightening of global aluminium supply and higher prices have provided a powerful tailwind for the group, which has chalked up fresh earnings records.
It delivered back-to-back record-high profits in the financial year ended Dec 31, 2024 (FY2024) and FY2025, and has carried that momentum into 1HFY2026.
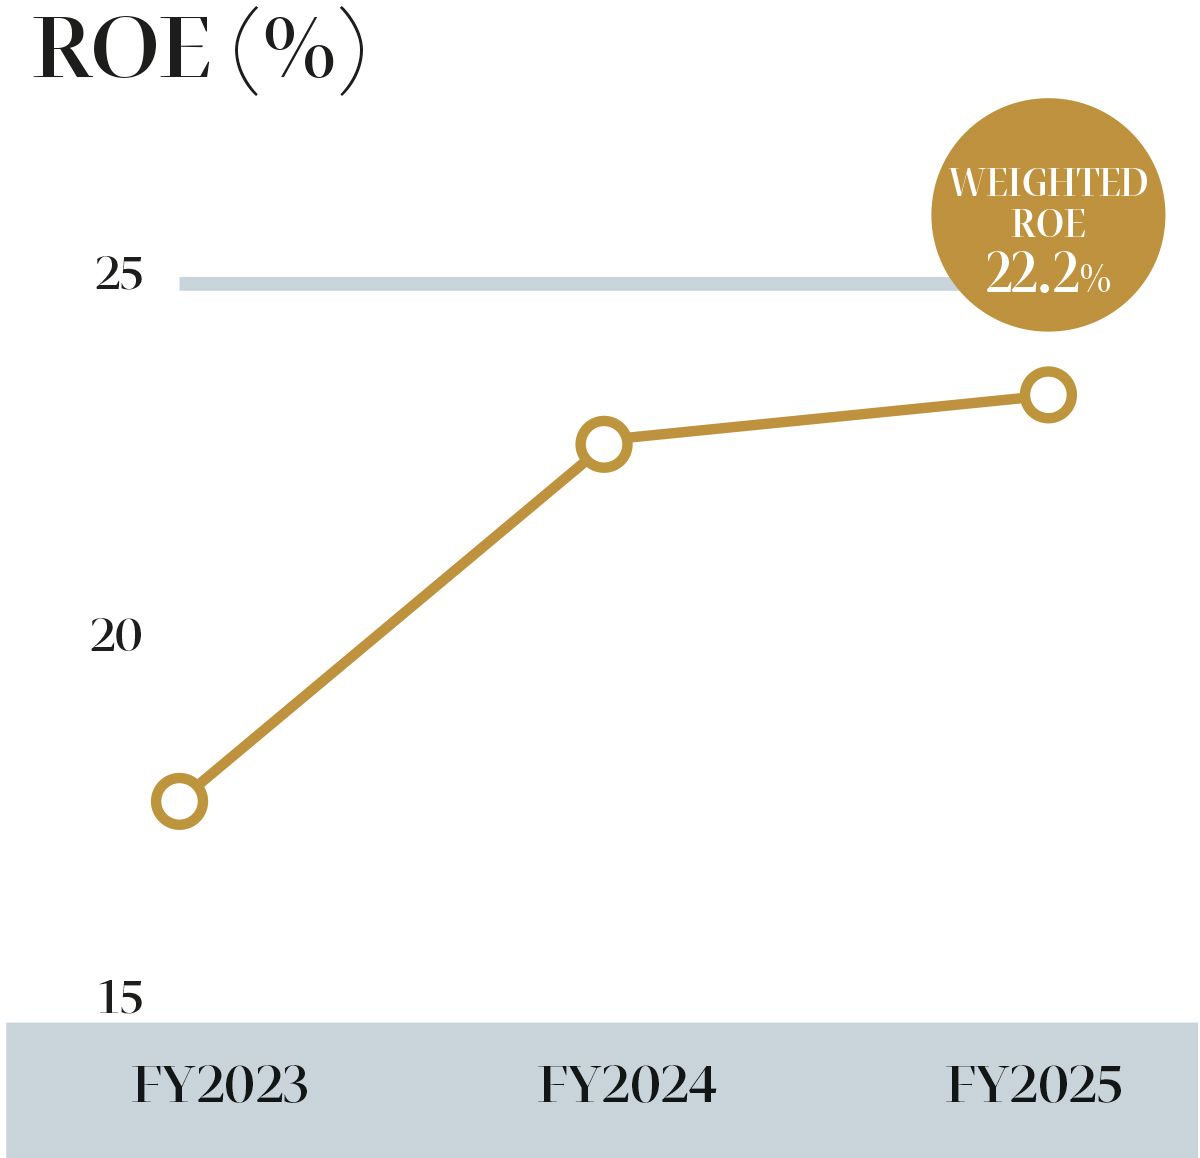
The stellar performance has helped Press Metal retain its accolade for the Highest return on equity (ROE) over three years in the super big cap category (above RM40 billion market capitalisation), for the second consecutive year.
Its ROE — a measure of how efficiently a company uses shareholders’ equity to generate profit — expanded steadily over the last three years, from 17.9% in FY2023 to 22.9% in FY2024 and 23.5% in FY2025, translating into an adjusted weighted three-year ROE of 22.2%.
During the BRC Awards evaluation period, Press Metal registered a three-year compound annual growth rate (CAGR) in net profit of 14.3%. Net earnings grew past the RM2 billion mark to RM2.1 billion in FY2025, from RM1.77 billion in FY2024, RM1.22 billion in FY2023 and RM1.41 billion in FY2022.
The record performance was attributed to higher sales volumes and aluminium prices, alongside a more favourable cost environment in FY2025. Similarly, revenue was also at a peak of RM16.21 billion in FY2025, compared with RM14.91 billion in FY2024.
Earnings momentum persisted in 1HFY2026, with net profit jumping 51% to RM1.43 billion from RM945.3 million a year ago, on the back of an 8.7% increase in revenue to RM8.79 billion from RM8.09 billion. This was supported by production curtailments in the Middle East and higher regional premiums.
The commodity boom has also fuelled a rally in Press Metal’s share price. As at March 31, 2026 — the BRC membership cut-off date — its shares stood at RM8, compared to RM4.65 three years ago, translating into a three-year shareholder returns CAGR of 19.8%.
The stock subsequently climbed to a record high of RM9.23 on June 3 before easing to close at RM8 on Aug 28.
The meteoric share price gain also propelled group CEO and co-founder Tan Sri Paul Koon Poh Keong and his siblings to second place — for the first time — on Forbes’ 2026 Malaysia 50 Richest List, with their combined net worth soaring 80% to US$9.7 billion (RM39.7 billion) from a year earlier. The Koon family were the biggest gainers in dollar terms among the tycoons on the list.
Poh Keong, 65, is the largest shareholder with a 35.05% stake.
Starting in 1986 as a small aluminium extrusion outfit, Press Metal now boasts the largest aluminium capacity in the region with 1.08 million tonnes per annum of smelting capacity and 230,000 tonnes per annum of extrusion capacity as at end-2025.
RHB Research expects the aluminium market to remain in deficit in 2026, estimating a shortfall of about 900,000 to one million tonnes. The research firm, citing Press Metal management, said the restart of Middle Eastern capacity could take six to 12 months while persistent shipping disruptions through the Strait of Hormuz and renewed conflict in the region could delay the recovery further.
RHB maintained its aluminium price assumptions at US$3,250 a tonne for 2026 before easing to US$3,050 a tonne for 2027.
Press Metal remains as RHB Research’s top pick, supported by elevated prices for the commodity due to a structural aluminium deficit, alongside an attractive valuation. It added that elevated aluminium prices justified the stock’s premium.
Another potential catalyst is the group’s 80% owned Indonesian subsidiary, PT Kalimantan Alumina Nusantara, whose alumina refinery is expected to begin commissioning in 2027. Its eventual expansion could potentially bring Press Metal closer to alumina self-sufficiency and further support its smelting margins, said RHB Research.
At the time of writing, 10 research houses had a “buy” call on Press Metal while five others recommended “hold”. Their target prices ranged from RM8.22 to RM10.67, averaging RM9.41, according to Bloomberg data.
Press Metal was the BRC’s Company of the Year in 2019. While its market capitalisation first crossed the RM1 billion threshold in early 2011, it was only from 2013 that the group remained consistently above the level required for The Edge BRC membership.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.