

This article first appeared in Capital, The Edge Malaysia Weekly on September 28, 2026 - October 4, 2026
Banking
POSITIVE
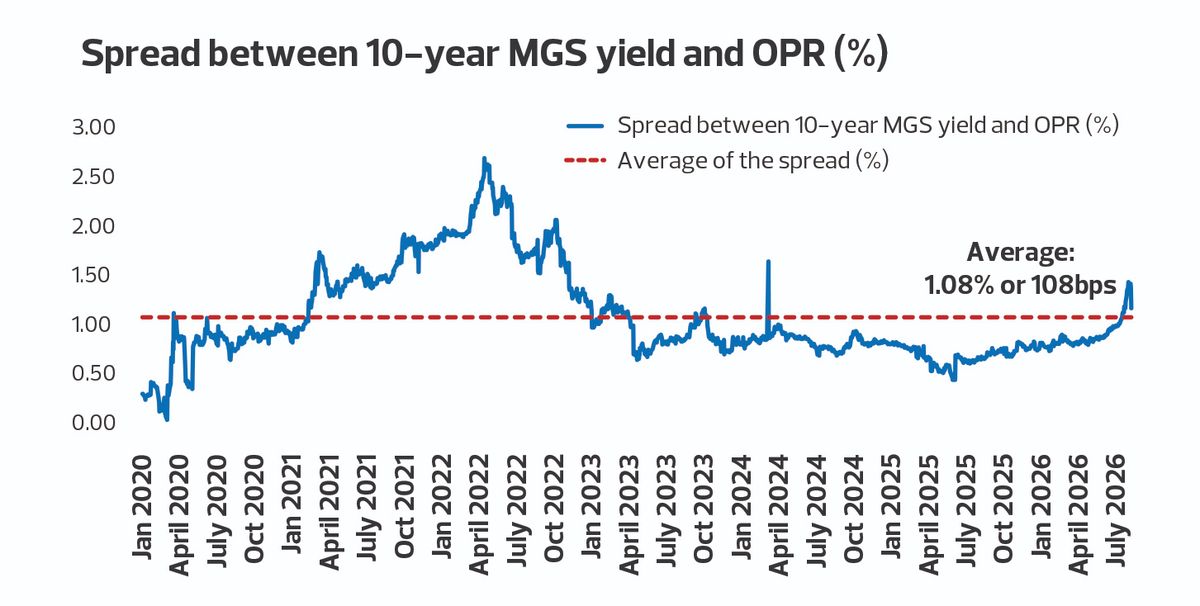
BIMB SECURITIES RESEARCH (Sept 22): Global bond markets experienced higher yields amid tighter US monetary policy and higher-for-longer interest rates. On Sept 16, the Federal Open Market Committee raised the federal funds rate target by 25 basis points (bps) to 3.75%-4.00%. The 10-year Malaysian Government Securities (MGS) yield stands at 4.15% as at Sept 21, and remains elevated by historical standards but is still below the peak of 4.57% recorded in October 2022.
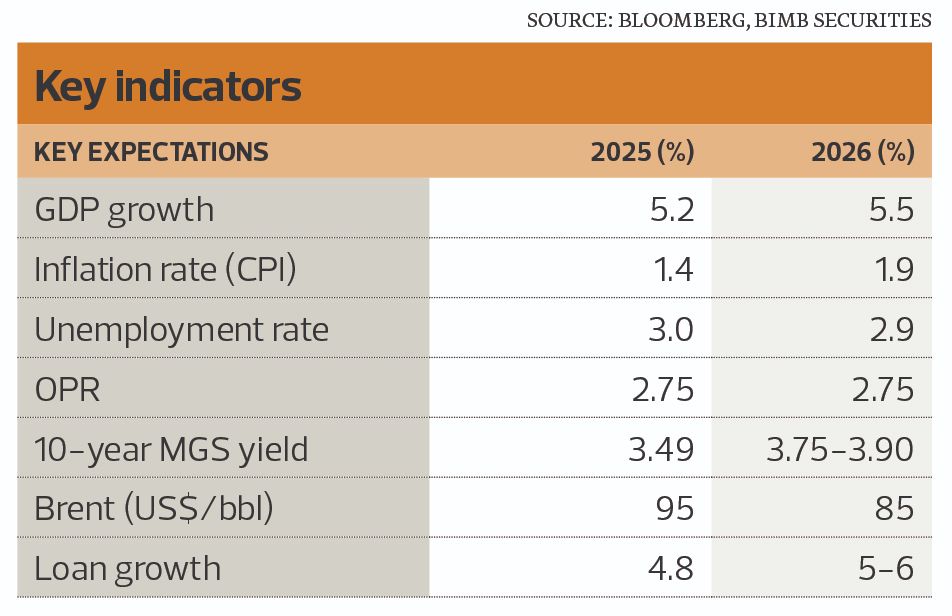
According to our economist’s assessment, the 10-year MGS yield is expected to hover around the 4.0% level in the near term before gradually moderating towards the 3.75%-3.90% range by year end. Current yield levels appear to reflect market expectations of close to two policy rate hikes in Malaysia. However, given our view that the Overnight Policy Rate will remain unchanged at 2.75% throughout 2026 and 2027, coupled with a contained domestic inflation outlook, the 10-year MGS yield is expected to ease from its current elevated level over time.
Banks typically maintain an average securities portfolio duration of around five to six years, which is considered moderate rather than long term. As a result, their investment portfolios are generally less sensitive to interest rate movements and face lower interest rate risk compared with portfolios concentrated on longer-dated securities.
The impact on fair value through other comprehensive income securities is expected to result in lower FVOCI reserves due to revaluation losses in 3Q26, as the 10-year MGS yield is likely to remain elevated in the near term. Nevertheless, the effect on ROE could be favourable, as the decline in shareholders’ funds reduces the equity base used in the ROE calculation.
Malayan Banking Bhd (KL:MAYBANK) (fair value: RM11.40), CIMB Group Holdings Bhd (KL:CIMB) (FV: RM8.75) and RHB Bank Bhd (KL:RHBBANK) (FV:RM8.50), which have exposure to the Singapore market, are likely to see improved net interest margins as the rise in three-month Singapore overnight rate change (SORA), in tandem with Fed rate hikes, lifts asset yields and helps mitigate fair value through profit and loss (FVTPL) mark-to-market losses in 3Q26.
Banks’ funding profiles remain largely anchored by longer-tenor liabilities, including Medium Term Notes with maturities of at least two to three years, which help maintain robust Net Stable Funding Ratio positions and reduce near-term refinancing pressures. As such, banks are unlikely to rush into refinancing and are more likely to adopt a wait-and-see approach when considering the rollover of maturing papers.
We do not expect deposit competition to become more aggressive from here, given that 1Q26 and 2Q26 had already witnessed intense competition, with banks offering promotional fixed deposit rates of up to 3.7%-3.8% for 10- to 12-month placements.
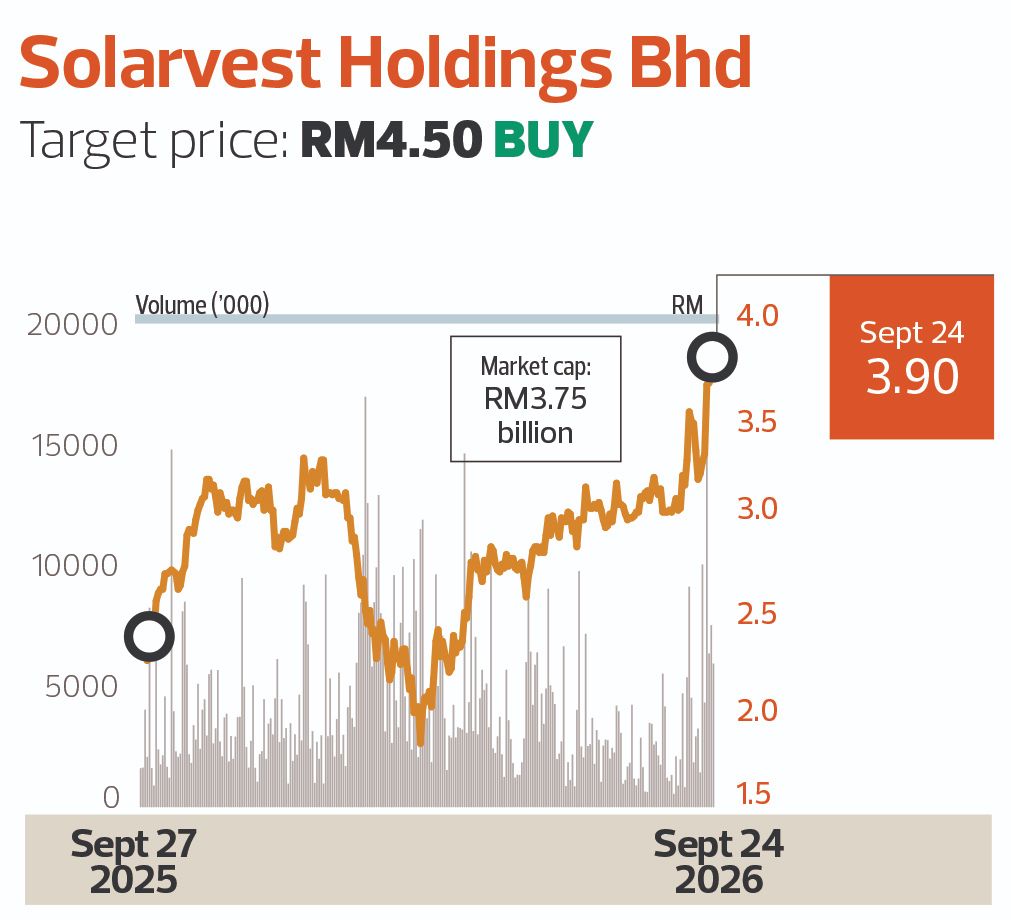
Solarvest Holdings Bhd
Target price: RM4.50 BUY
AMINVESTMENT BANK RESEARCH (Sept 21): We believe that Solarvest Holdings Bhd (KL:SLVEST) would benefit from the government’s CRESS Acceleration Package. Under the package, a System Access Charge (SAC) of 14 sen/kWh will be introduced. We think that the lower SAC would spur the rollout of CRESS projects, as under the previous CRESS scheme, the SAC were perceived as too high. The SAC under the previous CRESS were 20 sen/kWh for projects with battery systems and 40 sen/kWh for projects without battery systems.
We reckon that battery and solar systems contracts are worth about RM3.5million/mw to RM4million/mw based on recently announced projects.
There is incentive for data centres to do solar under the new CRESS. This is because the tariffs under the new CRESS package would come up to about 45 to 50 sen/kWh compared with their present electricity tariffs of 50 to 60 sen/kWh. Solarvest is bidding for 11,800mw worth of projects. Out of these, about 1,200mw are expected to come from battery projects. We have raised Solarvest’s FY2028F net profit by 13.5% and FY29F net earnings by 40.4% to account for a higher EPCC (engineering, procurement, construction and commissioning) order book due to the new CRESS projects.
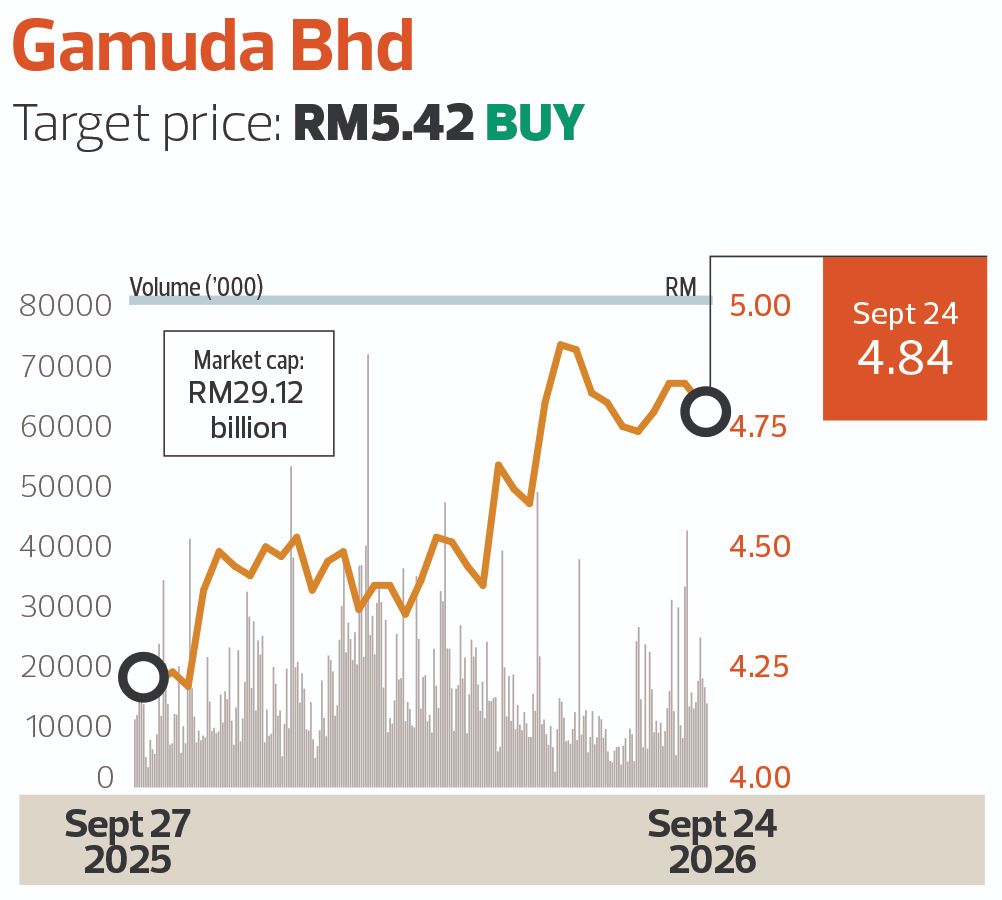
Gamuda Bhd
Target price: RM5.42 BUY
TA SECURITIES (Sept 22): Gamuda Bhd (KL:GAMUDA), via the Gamuda-BMD joint venture, has clinched the A$624 million (RM1.8 billion) Elizabeth Drive Upgrade — Mamre Road Upgrade Stage 2 Package from government agency Transport for New South Wales. Based on its 50% effective interest in the JV, Gamuda is entitled to roughly RM908 million in contract value.
Given that the award also comes with cost-pass-through clauses, we believe this should limit Gamuda’s execution risk and exposure to volatile material prices. Based on the management-guided PBT margin of 5%, we estimate the project could generate approximately RM45.4 million in PBT over the contract period.
Looking ahead, we expect Western Sydney’s rapid development to support sustained infrastructure spending, particularly across the road network. This should provide a healthy pipeline of replenishment opportunities for Gamuda.
Gamuda’s FY2027 year-to-date new job wins have reached RM10.2 billion, lifting its unbilled construction order book to RM62.5 billion. We believe Gamuda’s near-term order book replenishment prospects remain healthy, with potential wins likely to come from data centre projects from new and repeat clients in Malaysia, renewable energy projects in Australia, particularly solar EPCCs (engineering, procurement, construction and commissioning) works, and railway infrastructure projects in Taiwan.
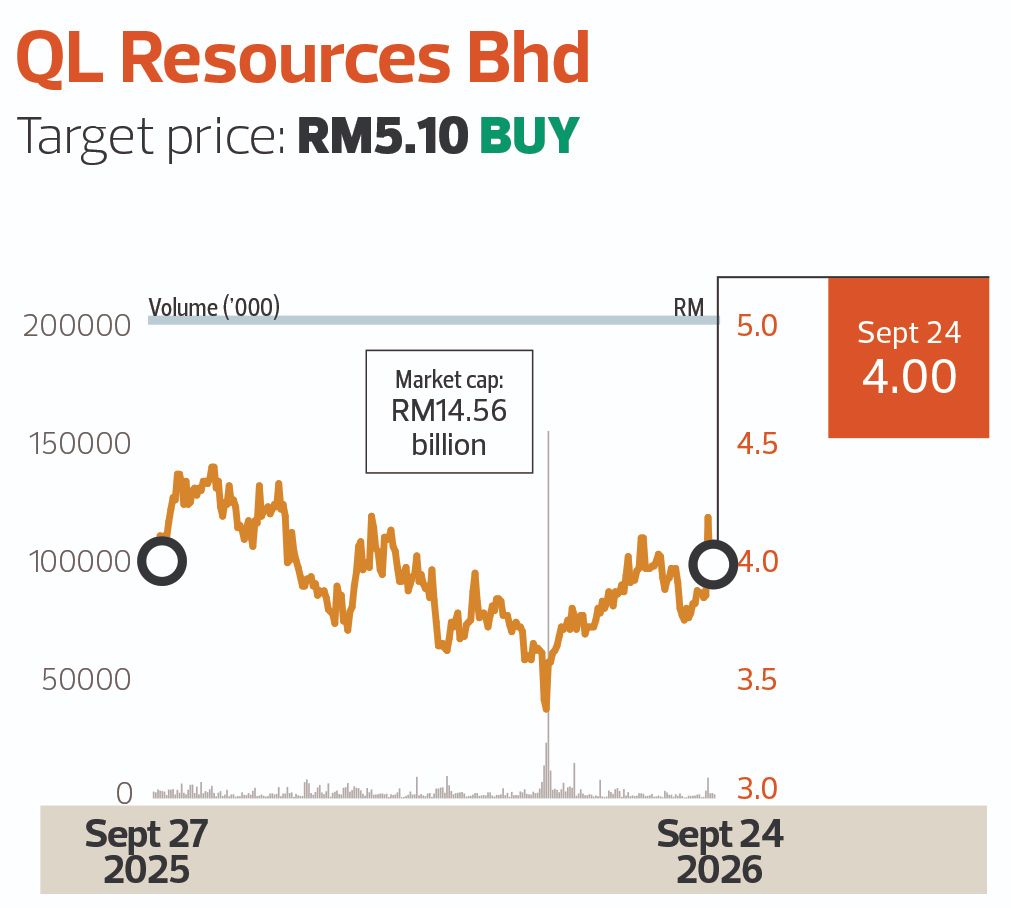
QL Resources Bhd
Target price: RM5.10 BUY
HONG LEONG INVESTMENT BANK RESEARCH (Sept 23): QL Resources Bhd’s (KL:QL)’s 1QFY2027 marine products manufacturing (MPM) revenue rose 18.2% year on year while PBT jumped 51.5%, with management attributing the bulk of the circa RM30 million y-o-y earnings uplift to fishmeal driven by Peru’s lower catch quota and a temporary El Niño fishing ban. Peru, which supplies roughly a fifth of the world’s fishmeal, in August called off its main anchovy season having landed only 25% of an already reduced quota. That keeps global supply tight, and fishmeal prices in July were still running about 11% above where they averaged through QL’s 1QFY27.
Grade C egg prices recovered from the low RM0.20s in April to May to RM0.33 by end-June and >RM0.40 at the farm gate by August
We remain constructive on QL, given that MPM is delivering into a supply shock with further runway into FY27, and did so in a seasonally soft quarter with the stronger quarters still ahead. Clean energy under BM Greentech Bhd (KL:BMGREEN] now has a working commercial proof point inside QL’s own plant while Innofood will begin contributing from 2HFY28. Integrated livestock farming and convenience store chain segments have, in our view, both passed their respective troughs, with egg prices recovering off the April low and FamilyMart's top line turning after three quarters of decline.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.