

This article first appeared in Capital, The Edge Malaysia Weekly on September 28, 2026 - October 4, 2026
E-COMMERCE logistics and workforce solutions provider Evocom Bhd (KL:EVOCOM) is set to make its debut on Bursa Malaysia’s ACE Market on Monday (Sept 28), with the group looking to broaden its logistics footprint through an expansion of its air freight transhipment business, technology investments and a new headquarters near Kuala Lumpur International Airport’s (KLIA) air cargo terminal.
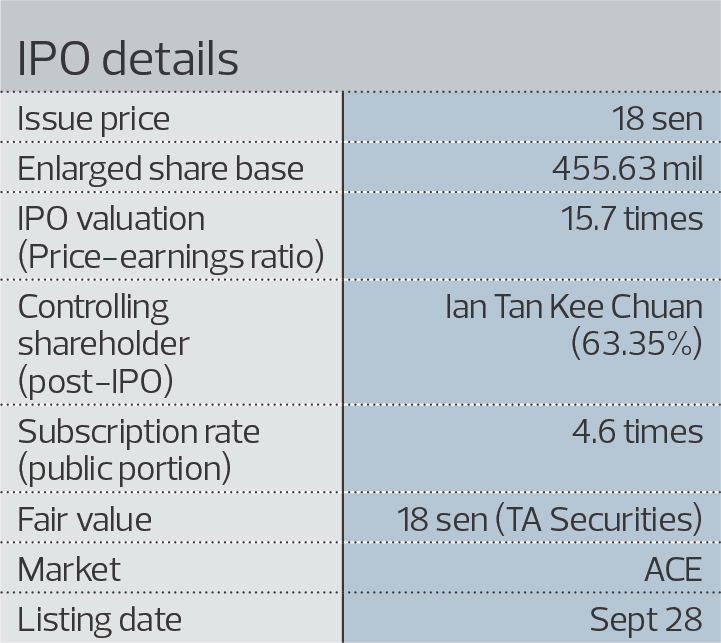
The company’s initial public offering (IPO) comprises 113.91 million new shares and an offer for sale of 22 million existing shares, both priced at 18 sen apiece. Based on its enlarged share capital of 455.6 million shares, Evocom will have an estimated market capitalisation of RM82 million at the IPO price.
Established in 2017 by executive director and CEO Ian Tan Kee Chuan, Evocom operates through two main segments — flexible staffing services and network support services.
The flexible staffing business provides manpower to logistics partners, while network support services encompass last-mile delivery, transhipment and parcel shipment. In the financial year ended Dec 31, 2025 (FY2025), flexible staffing accounted for 86.9% of the group’s RM183.4 million revenue, with network support services contributing the remaining 13.1%.
Geographically, Malaysia remains the group’s main market, accounting for 88.5% of FY2025 revenue, while China and Hong Kong contributed the remaining 11.5%.
In a Sept 8 report, TA Securities said the group’s presence across Malaysia and China allows it to offer end-to-end services and address a larger market than its pure-play logistics peers.
Its business is highly reliant on e-commerce logistics players such as Shopee Xpress and Lazada Logistics.
Evocom is currently heavily concentrated on Shopee Xpress, which contributed 87.8% of the group’s FY2025 revenue, according to the company’s business model. The other four largest customers contributed about 11.6% of revenue, bringing the contribution from its top five customers to 99.53% of the business. This highlights the significant customer concentration risk that the group faces.
In terms of its business model, the group operates through two distribution channels — direct and indirect. The direct channel serves retail senders and receivers with end-to-end logistics services, while the indirect channel works through logistics partners, delivery contractors and courier companies to extend coverage into countries where it lacks a physical presence.
While the direct channel allows for greater control over service delivery, the indirect channel enables Evocom to leverage its partners’ networks to reach markets beyond its own physical footprint.
Expansion plans
Evocom expects to raise gross proceeds of RM20.5 million from the IPO. The largest allocation, RM7.2 million, or 35.1%, will go towards working capital for its flexible staffing services.
Another RM3 million, or 14.6%, will be used to develop its technology application, while RM3 million will fund working capital for the expansion of its air freight transhipment business. A further RM1.5 million is earmarked for the proposed Nilai headquarters, with RM1.3 million for general working capital. Listing expenses account for RM4.5 million, or 21.8% of the proceeds.
The proposed Nilai headquarters is located near the KLIA air cargo terminal and will replace Evocom’s existing premises in Semenyih. The facility is intended to centralise its headquarters, operations and warehousing, with dedicated storage space to fulfil and dispatch transhipment orders for delivery contractors serving China-based e-commerce platforms.
Evocom is also developing two in-house digital platforms: EVOSHIFT is an AI-driven logistics platform designed to optimise last-mile delivery routing, live parcel tracking and flexible delivery scheduling; and CLiPS is a digital learning platform incorporating AI-generated content, gamification and assessments to develop workforce skills, safety and retention.
TA Securities noted, however, that both platforms are for internal deployment and do not yet have commercial or pricing models.
Earnings hit by customer staff optimisation
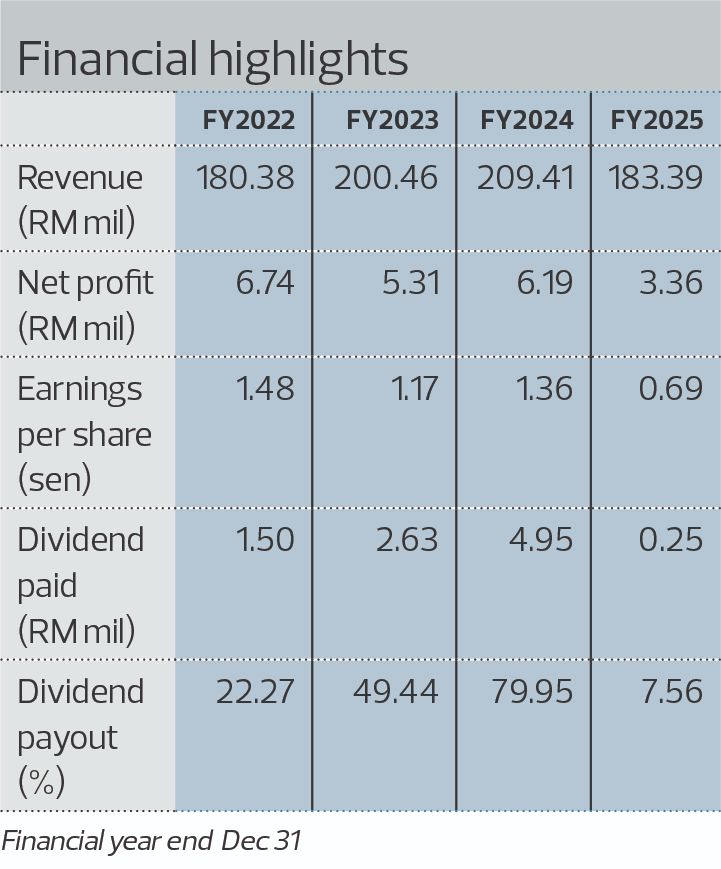
Evocom’s revenue declined 12.4% year on year to RM183.4 million in FY2025, from RM209.4 million, following staff optimisation by its key customer, which reduced the number of workers deployed under the flexible staffing segment.
As a result, core profit fell 12.7% to RM5.2 million, from RM6 million.
TA Securities expects earnings to remain broadly flat in FY2026, with core profit forecast at RM5.5 million, before rising to RM5.9 million in FY2027 and RM6.2 million in FY2028.
Revenue is projected to increase from a forecast RM194.4 million in FY2026 to RM206.1 million in FY2027 and RM218.4 million in FY2028. Core net profit is forecast at RM5.5 million, RM5.9 million and RM6.2 million respectively.
The earnings recovery is premised on the ramp-up of hub management contracts with Lazada, a recovery in transhipment volumes to Australia, the Middle East and the US, and progress in diversifying into account management services.
The broader industry backdrop remains relatively steady. According to industry research cited by TA Securities, Malaysia’s e-commerce logistics support services industry is projected to grow from RM1.4 billion in 2024 to RM1.7 billion in 2028, representing a 3.7% compound annual growth rate.
Despite its expansion plans, the clearest risk for Evocom is customer concentration, particularly in its flexible staffing business. Other risks highlighted by TA Securities include the labour-intensive nature of the business, difficulty in expanding its service offerings and customer base, and seasonal fluctuations in demand.
The research house also highlighted execution risks as Evocom seeks to expand its hub network beyond Wangsa Maju and Rawang, and secure new transhipment partnerships with China-based e-commerce delivery contractors.
At the IPO price of 18 sen, Evocom is valued at 15.7 times FY2025 core earnings. TA Securities values the company at 14 times its forecast FY2027 core earnings and arrives at a fair value of 18 sen a share.
The valuation is based on GDEX Bhd (KL:GDEX) as the closest listed proxy, although TA Securities applies a substantial discount to GDEX’s CY2027 forward price-earnings ratio of 28 times, citing Evocom’s smaller scale, lower market share and single-customer concentration.
Following the IPO and utilisation of proceeds, Evocom’s pro forma net cash position is expected to rise to RM39 million, from RM21 million. The company has no formal dividend policy.
Its listing, scheduled for Sept 28, will give investors exposure to a smaller e-commerce logistics player seeking to move beyond its traditional workforce solutions business into transhipment, technology and a broader logistics network.
Investor demand has been relatively modest, with the public portion of the IPO reportedly oversubscribed by 3.6 times.
NewParadigm Securities Sdn Bhd is the IPO’s principal adviser, sponsor, sole underwriter and sole placement agent.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.