

A weekly round-up of tanker and dry bulk market (Sept 25, 2026)
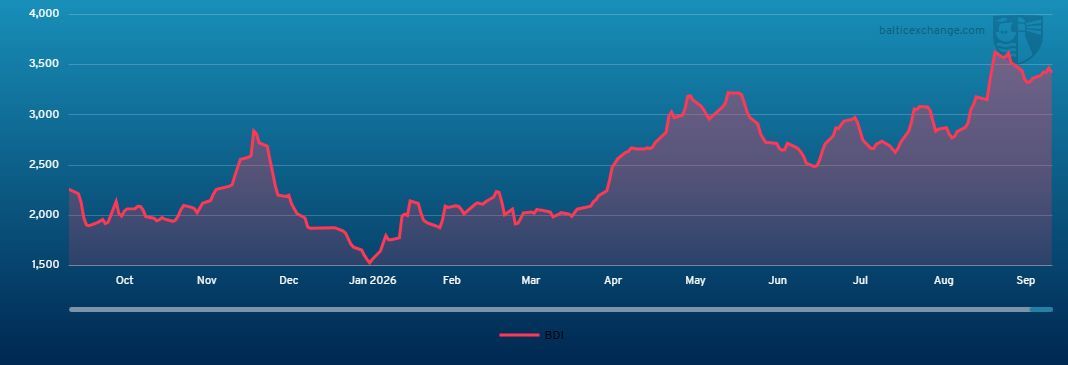
The Baltic Exchange, a wholly-owned subsidiary of Singapore Exchange, is the world's only independent source of maritime market information for the trading and settlement of physical and derivative contracts.
Its international community of over 650 members encompasses the majority of world shipping interests and commits to a code of business conduct overseen by the Baltic.
For daily freight market reports and assessments, please visit www.balticexchange.com.
Capesize
The Capesize market continued to climb towards the highs seen earlier this month before losing some momentum on the final day of the week. Nevertheless, the timecharter average edged up US$142 week-on-week to close at US$52,457. In the Atlantic, both trans- Atlantic and fronthaul rates surged on Thursday following a week of growing anticipation, driven by reports of tightening tonnage availability in the North Atlantic and an expanding cargo book. However, softer fixture emerged towards the end of the week, prompting the C8 route to retreat by more than US$1,000 to US$62,938. Despite the pullback, the route remained at its strongest level since early December last year. The C9 index followed a similar pattern, posting gains before easing back to finish the week at US$91,494. In the Pacific, activity on the West Australia to Qingdao route remained steady, although rates came under pressure. The C5 index slipped from US$16.685 to US$15.625 on Friday, weighed down by a succession of fixtures reported by both miners and operators.
Panamax-Kamsarmax
Across the week, market sentiment strengthened across both basins, supported by improving fundamentals and firmer rate discussions. The Atlantic led the gains as increased cargo enquiry and tightening prompt tonnage availability in the North Continent and West Mediterranean drove stronger trans-Atlantic and fronthaul sentiment. An 82,000-dwt fixed for a trans-Atlantic round trip at US$21,300 while another fixed for US$22,400 for a similar trip. An 82,000-dwt open in southern Spain fixed for a fronthaul trip via the US Gulf at US$27,500. Demand from East Coast South America also improved, helping owners push rate expectations higher despite widening bid-offer spreads. An 83,000-dwt was reported fixed at US$23,000 plus a US$1,300,000 ballast bonus, highlighting the firmer tone. In the Pacific, sentiment was more mixed. While prompt Indonesian demand softened earlier in the week, Australia and the North Pacific provided underlying support. An 82,000-dwt fixed an EC Australia round trip at US$26,000 and an 81,000-dwt fixed at US$20,500 for a similar trip. Conditions improved later in the week as Indonesian activity recovered, with an 82,000-dwt fixing for a trip via Indonesia to India at US$25,500 and a 74,000-dwt fixing for Indonesia to South China at US$15,500. Period activity was evident with an 81,000-dwt fixing for 1 year at US$20,500 and an 82,000-dwt fixing for 7 to 9 months at US$23,500.
Ultramax/Supramax
A subdued and flat week overall, with holidays in Asia causing disruption in the Pacific market. Demand from the North American market has slowed and the fronthaul rates have softened, although a 63,000-dwt was fixed basis delivery Norfolk for a trip China with petcoke at US$34,500. The South Atlantic rates managed to hold steady with the market more balanced, but the Mediterranean was lacking sufficient cargoes, with owners now considering ballasting. The bright spot in the Atlantic was the Continent with scrap demand pushing rates on Ultramaxes close to US$40,000 for trips to East Mediterranean. In Asia the North Pacific remained a hive of activity with a 66,000-dwt fixed via NoPac to Chittagong at US$26,000 and plentiful backhauls with a 63,000-dwt fixed from Nansha via Gulf of Aden to the Mediterranean at US$26,000. Indonesia continued to support tonnage in the south and the Bay of Bengal with a 64,000-dwt fixed from Haldia via Indonesia back to India at US$22,000 and South African rates edged up this week with a 63,000-dwt fixed Richards Bay to Sri Lanka at US$28,000 plus US$280,000 ballast bonus. Despite the spot market moving sideways, period interest remained with a 64,000-dwt in Vietnam fixed for 5 to 7 months at US$24,500 and a 60,000-dwt in Mumbai fixed for a longer period of 19 to 21 months at US$18,000.
Handysize
The market maintained a mixed tone throughout the week, with the Atlantic firm and the Pacific steady. The Continent and Mediterranean began quietly before gathering momentum, supported by strong scrap demand, with rates improving as the week progressed. A 36,000-dwt vessel open Rotterdam 2–4 October was fixed via the Baltic to the East Mediterranean with scrap at US$26,000. The South Atlantic remained steady, while the US Gulf was consistently well supported by healthy demand and a shortage of prompt tonnage. Notable fixtures included a 38,000-dwt vessel open Coronel 21 September, fixed for a trip from Recalada to the West Coast of South America with grains at US$29,500, and a 34,000-dwt vessel open Brownsville 22–25 September, fixed from SW Pass to Spain with grains at US$25,000. In Asia, holidays restricted activity and kept the market broadly flat, although healthy enquiry and a gradually tightening tonnage list offered some support. A 39,000-dwt vessel open CJK prompt, fixed for a trip to the West Coast of Central America at US$21,500.
Clean
LR2
The TC1 75kt MEG/Japan index increased by 41.67 points this week to WS875.56, with the corresponding Baltic round-trip TCE rising from US$237,000/day to US$252,100/day. On a trip west the TC20 90kt MEG/UK-Continent index increased by US$662,500 to US$17.27 million. The TC15 80kt Mediterranean/East index increased by US$336,000 to US$7.73 million, with the corresponding Baltic round-trip TCE rising from US$53,400/day to US$59,600/day.
LR1
The TC5 55kt MEG/Japan index increased by 40.31 points this week to WS890, with the corresponding Baltic round-trip TCE rising from US$171,700/day to US$182,300/day. Heading towards Europe, the TC8 65kt MEG/UK-Continent index increased by approximately US$829,000 to US$12.03 million.
MR
The TC17 35kt MEG/East Africa index increased by 99.29 points this week to WS847.86, with the corresponding Baltic round-trip TCE rising from US$91,700/day to US$107,500/day. On the UK-Continent, the TC2 37kt ARA/US Atlantic Coast index increased incrementally by 11.67 points to WS161.11 this week. The corresponding Baltic round-trip TCE rose from US$1,350/day to US$4,202/day. In the US Gulf, the TC14 38kt US Gulf/UK-Continent index climbed by 22.86 points to WS254.29. The corresponding Baltic round-trip TCE rose from US$20,600/day to US$25,800/day. For a run down to the Caribbean, the TC21 38kt US Gulf/Caribbean index increased by US$110,700 to US$785,700, with the corresponding Baltic TCE rising from US$14,100/day to US$21,100/day.
The MR Atlantic Triangulation Basket TCE increased from US$28,400/day to US$34,800/day.
Handymax
In the Mediterranean, the TC6 30kt Cross-Mediterranean index increased by 64.83 points to WS250. The corresponding Baltic round-trip TCE rose from US$10,400/day to US$29,100/day. The TC23 30kt Cross UK-Continent index increased by 22.78 points to WS251.11. The corresponding Baltic round-trip TCE rose from US$18,800/day to US$26,000/day.
VLCC
This week has seen the rates soften slightly in the Middle East market for the VLCCs. The TD3C route (270,000 mt Middle East Gulf to China) eased from WS1,165 last Friday to WS1,157.5 on Thursday. This gives a daily round-trip TCE of US$1,235,414 for the standard Baltic VLCC. TD34 (Gulf of Oman to China) slipped about 6 points to WS797.86 in the same period, meaning a round-trip TCE of US$864,698/day.
In the Atlantic market, the rate for the 260,000 mt West Africa to China route (TD15) shed 22 points to WS511.88, giving a round voyage TCE of US$507,060/day, while the US Gulf to China route (TD22) gained another US$500,000 to just over US$52,500,000, which gives a daily round trip TCE of US$407,100.
Suezmax
In the Suezmax sector, the market is also softer for all the Baltic routes. The rate for the 130,000 mt Nigeria/UK Continent voyage (TD20) dropped 18 points to WS435, which translates into a daily round-trip TCE of about US$228,400. The TD27 route (Guyana to UK Continent basis 130,000 mt) fell slightly further, losing 27 points to just shy of WS437, giving a daily round trip TCE of about US$232,800. The 145,000 mt USG/UKC (TD33) similarly lost 26 points to WS365.83, which gives a round-trip TCE of just over US$225,700/day. In the Black Sea, the market remains around the WS500 mark for the TD6 route of 135,000 mt CPC/Augusta, which shows a daily round-trip TCE of about US$368,000.
Aframax
In the North Sea, the rate for the 80,000 mt Cross-UK Continent route (TD7) took a large step up, gaining 112.5 points to WS416.67, showing a daily round-trip TCE of close to US$306,600 basis Hound Point to Wilhelmshaven.
In the Mediterranean, the rate for 80,000 mt Cross-Mediterranean (TD19) made big gains again, rising 132 points to WS557.78, basis Ceyhan to Lavera this shows a daily round trip TCE of about US$289,400.
Across the Atlantic, the rollercoaster ride is back in operation, with significant gains made on an already firm market. The 70,000 mt East Coast Mexico/US Gulf route (TD26) rose 64 points to about the WS505 level (which is a daily round-trip TCE of just over US$160,800). The 70,000 mt Covenas/US Gulf route (TD9) also gained 64 points to WS495, translating into a daily round trip TCE of about US$147,800.
The rate for the trans-Atlantic route of 70,000 mt US Gulf/UK Continent (TD25) improved more than the shorter hauls, rising 113 points to over WS557.5, which gives a round trip TCE basis Houston/Rotterdam of almost US$165,100.
On the Vancouver exports, TD28 (80,000 mt crude oil Vancouver to China) rose by over US$100,000 to just over US$7,800,000 (giving a round trip TCE of just under US$151,800/day) while TD29 (80,000 mt crude oil Vancouver to Pacific Area Lightering point off the US West Coast) gained a further 15 points to WS467.5.
LNG
LNG carrier rates strengthened throughout the week, with all three Baltic LNG benchmark routes ending higher as improving chartering activity and seasonal demand expectations supported sentiment. The strongest gains were recorded on the US Gulf export routes, reflecting firmer freight demand and tightening vessel availability. BLNG1 increased from US$28,050/day at the start of the week to US$33,200/day by Friday, while BLNG2 rose from US$24,700/day to US$32,400/day. BLNG3 posted the largest gain, climbing from US$51,900/day to US$66,000/day over the same period.
Market sentiment improved with activity most noticeable in the Atlantic Basin. Winter gas demand continues to provide support as Europe and Asia compete for LNG supplies ahead of the heating season. Strong US flows and healthy production levels from alternative export regions are also helping to maintain cargo availability and trading opportunities.
Period assessments were mixed. The six-month assessment softened to US$42,500/day, suggesting some caution over short-term market prospects, while the one-year and three-year assessments increased to US$55,167/day and US$73,000/day, respectively, reflecting continued confidence in longer-term LNG shipping fundamentals.
LPG
The LPG market strengthened this week, with freight rates most notably in the US Gulf climbing as available tonnage was reported to be thinning out, bolstered by short-term charters proving lucrative in the Middle East region keeping vessels there.
On the BLPG1 Ras Tanura–Chiba route, rate remained stable this week at US$242, with corresponding TCE earnings rising from US$231,500/day to US$234,700/day.
The BLPG2 Houston–Flushing route increased by US$2.17 week-on-week to settle at US$174.00. The corresponding TCE increased by US$5,300/day to US$202,700/day.
The BLPG3 Houston–Chiba route increased by US$3.29 to close at US$324.00, while TCE returns rose by US$5,700/day to US$199,200/day.
Container
The FBX index fell 2.3% this week to 3,367 due to weakness on the Asia-Europe trades contrasting with a firmer transpacific market. China/East Asia-North Europe recorded the largest fall, down 9.7% to US$3,293/FEU, while China/East Asia-Mediterranean declined 8.7% to US$3,571/FEU. The declines come amid signs of increasing effective capacity on the Asia-Europe trades as more vessels transit the Suez Canal, while carriers continue to use blank sailings to manage available tonnage. With China’s Golden Week approaching, further downward pressure on rates is anticipated in the near term.
Transpacific remained comparatively resilient, with China/East Asia-US West Coast increasing 1.2% to US$8,446/FEU and the US East Coast route unchanged at US$9,606/FEU as carriers continued to manage capacity.
Europe-South America East Coast rose 8.1% to US$1,205/FEU, while Europe-South America West Coast declined 3.5% to US$2,372/FEU. The wider market continues to reflect a divergence between trades, with available capacity and its deployment playing an increasingly important role in rate direction, while the substantial container vessel orderbook remains a longer-term consideration for the supply-demand balance.
Disclaimer:
While reasonable care has been taken by the Baltic Exchange Information Services Limited (BEISL) and The Baltic Exchange (Asia) Pte. Ltd. (BEA, and together with BEISL being Baltic) in providing this information, all such information is for general use, provided without warranty or representation, is not designed to be used for or relied upon for any specific purpose, and does not infringe upon the legitimate rights and interests of any third party including intellectual property. The Baltic will not accept any liability for any loss incurred in any way whatsoever by any person who seeks to rely on the information contained herein.
All intellectual property and related rights in this information are owned by the Baltic. Any form of copying, distribution, extraction or re-utilisation of this information by any means, whether electronic or otherwise, is expressly prohibited. Persons wishing to do so must first obtain a licence to do so from the Baltic.