

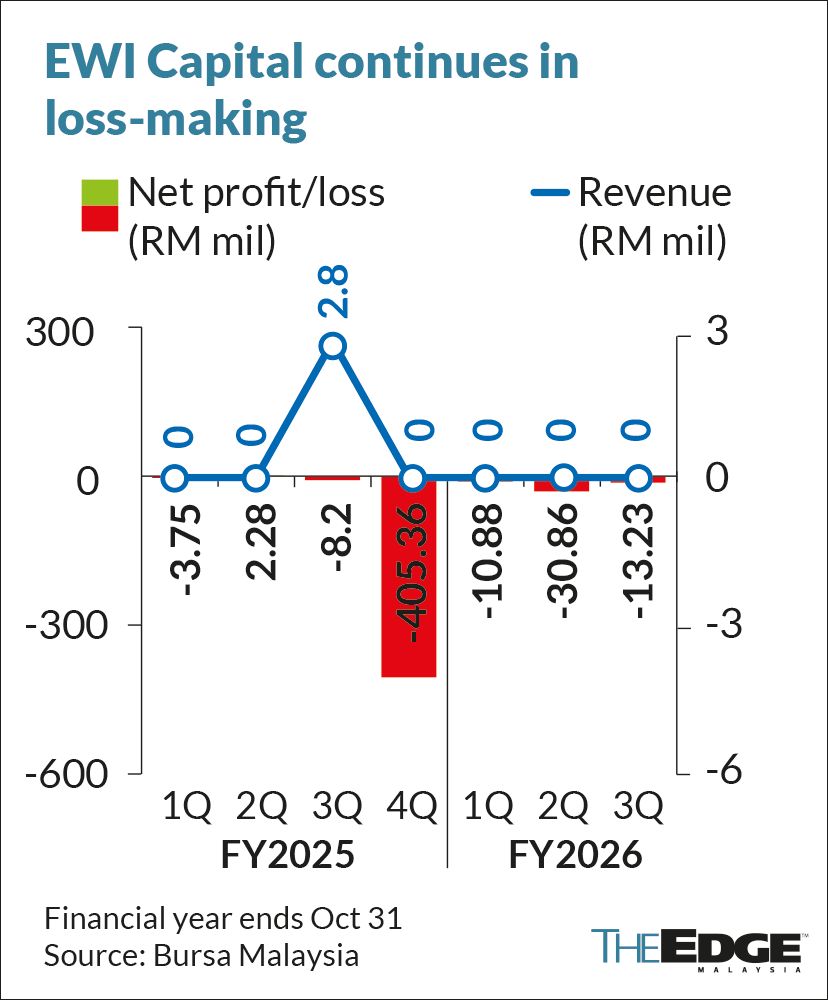
KUALA LUMPUR (Sept 25): EWI Capital Bhd’s (KL:EWICAP), formerly known as Eco-World International Bhd, reported a wider net loss of RM13.23 million in the third quarter, from RM8.18 million a year ago, weighed down by higher impairment and finance costs.
The latest quarterly net loss also marked EWI Capital’s fifth straight quarter in the red. The loss streak began in 3QFY2025. No revenue was recognised during the three months ended July 31, 2026 (3QFY2026).
The group said the higher loss was mainly due to a RM6.57 million impairment loss owing by its joint ventures, more than double the RM3.02 million recorded a year earlier, and lower sales activities with fixed overheads incurred on ongoing projects and progress in obtaining planning approvals across its existing undeveloped sites.
The quarterly loss was also due to a finance cost of RM3.71 million on the borrowing, following the investment in TrustCapital Australian Office Fund No 3 (AOF3).
EWI Capital invested A$100 million in AOF3, which had completed the acquisition of a property located at 750 Collins Street in Melbourne in May this year. The property, comprising about 41,000 square metres of net lettable area, is leased to Monash University under a long-term lease expiring in 2035.
The group said the assets provide AOF3 with an immediate source of recurring income, which will in turn be distributed to EWI Capital, forming an integral part of the group’s strategy to establish recurring income and chart a return to profitability.
For the nine months of FY2026 (9MFY2026), the group’s net loss also widened to RM54.97 million, from RM9.7 million a year before.
Looking ahead, EWI Capital said it recorded RM34.7 million in sales based on contracts exchanged during the first 10 months of FY2026. Including reservations of RM9.8 million, total sales achieved to date stood at RM44.5 million.
As at Aug 31, 2026, 99% of launched units had been sold. The value of completed units currently available for sale was approximately RM92 million, of which about 60% comprised commercial units, with the balance comprising residential units.
On its prospects, EWI Capital said the London residential market continues to face headwinds for developers as housing prices remain on the decline while construction costs remain elevated, placing pressure on development margins.
“With regards to the four remaining UK projects in the group’s portfolio, the development plan for Griffin Park site at Kew Bridge has been approved, while the Duffy site is expected to receive planning permission in FY2027,” said the group.
“The board is currently evaluating the feasibility of proceeding with the development of Griffin Park, while also exploring potential disposal options to accelerate monetisation,” it added.
Looking to Australia, the group said, notwithstanding near-term impact from higher interest rates, the condition for the Australian office market continues to improve for well-located, high quality assets.
Overall, the board expects the operating environment to remain challenging, with heightened geopolitical uncertainties, particularly the ongoing conflict in the Middle East, contributing to inflationary pressures and broader economic uncertainty.
With that, the group will remain disciplined in its capital allocation, continue to assess the feasibility of its existing projects, pursue the monetisation of its remaining development assets, strengthen recurring income streams and preserve financial flexibility as it navigates the evolving market environment, it added.
Shares of EWI Capital ended unchanged at 18.5 sen on Friday (Sept 25), valuing the group at RM444 million.