

This article first appeared in Capital, The Edge Malaysia Weekly on September 21, 2026 - September 27, 2026
Oil and gas
OVERWEIGHT
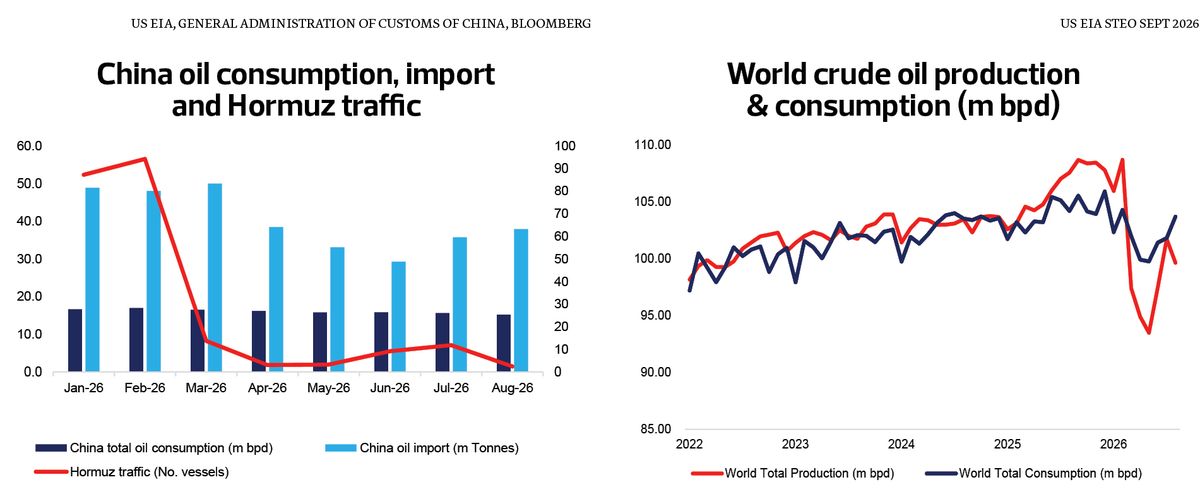
HONG LEONG INVESTMENT BANK RESEARCH (SEPT 14): Brent has returned above US$100 per barrel as risks rise across Hormuz, Bab el-Mandeb and Saudi’s East-West Pipeline, while Middle East supply disruptions have widened the global oil deficit. China crude imports are also recovering, adding further upside risk to prices. We now expect Brent at US$95-US$100 per barrel towards end-2026 and raise our 2026 assumption to US$90 per barrel from US$80 per barrel.
While we retain “buy” calls on most names, we remain selective and favour companies with earnings drivers that can sustain beyond near-term Brent volatility.
We advocate positioning for our 2027 thesis of a recovery in Petroliam Nasional Bhd’s (PETRONAS) upstream capital expenditure (capex) alongside rising regional energy-security investments. We believe the sector remains supported by a recovery in offshore support vessel-related names such as Dayang Enterprise Holdings Bhd (KL:DAYANG), Keyfield International Bhd (KL:KEYFIELD) and Perdana Petroleum Bhd (KL:PERDANA), while improving oil and gas services and equipment order flows and longer-term demand for storage, pipelines and broader energy infrastructure should continue to support Dialog Group Bhd (KL:DIALOG) and Wasco Bhd (KL:WASCO).
Dialog remains our top pick. We expect Dialog’s earnings to remain well supported in FY27-FY28 by growth across its three key segments. Upstream will be supported by the new Cendramas production sharing contract and Baram Junior Cluster (both commencing from 2QFY27), which are expected to shift the upstream earnings mix higher to 30% to 40%. Meanwhile, Dialog’s downstream earnings visibility remains well supported by several ongoing engineering, procurement, construction and commissioning projects.
PETRONAS Chemicals Group Bhd’s (KL:PCHEM) (PetChem) share price has risen around 25% after we upgraded it to “buy” in our end-June report. We are seeing early signs of stabilisation in key product prices, while elevated Brent prices could support further improvement in overall average selling prices in 4QFY26. We expect utilisation rates to improve with minimal turnaround activities at Methanol 2 for 60 days and Fertiliser Sabah for 10 days in 3QFY26, while no scheduled plant turnaround is expected in 4QFY26. PetChem remains attractive, with recovery of urea prices in 2HFY27 as seasonal planting demand returns, and potential divestment of its Pengerang Petrochemical Co Sdn Bhd stake, which could remove significant earnings drag and reduce the group’s foreign exchange (forex) exposure.
We view Dayang as a key beneficiary of a potential PETRONAS upstream capex recovery in 2027. Dayang delivered a stronger performance in 2024, when PETRONAS’ upstream spending was relatively elevated at around RM21.5 billion across 2023-2024, while upstream capex remained subdued at only RM9 billion in 1HFY26.
Sorento Capital Bhd
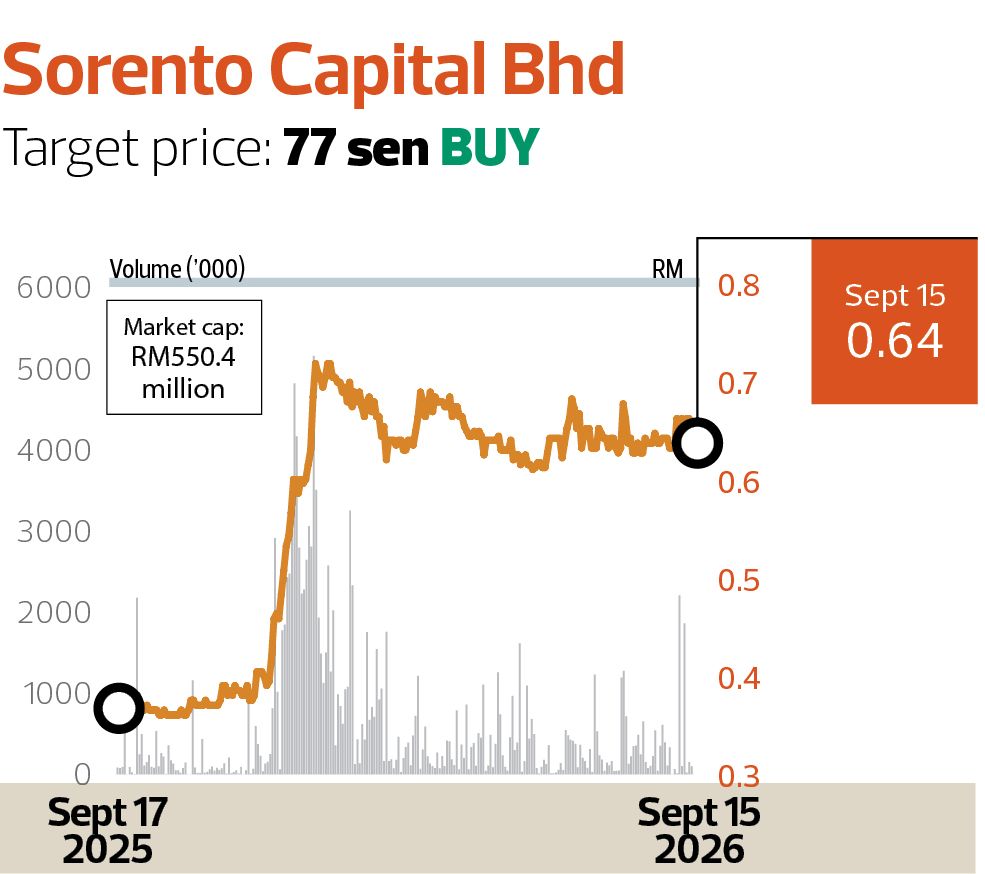
Target price: 77 sen BUY
TA SECURITIES (SEPT 14): Sorento Capital Bhd’s (KL:SORENTO) FY26 gross profit margin reached 45.2%, the highest in the company’s history, despite challenging market conditions arising from the US-Iran war. Management attributes the margin expansion to a reduction in original equipment manufacturing cost in China late last year, which contributed to a stronger 47% gross profit margin in 4QFY26.
According to management, global brass prices rose by 50% following the onset of the US-Iran war, leading to higher production cost for bathroom and kitchen taps. However, prices of ceramic bathroom products have been undergoing price cutting. As China’s exports of ceramic products to the Middle East has been disrupted by the war, these products have been redirected to Asian markets, creating downward price pressure. As such, management is confident of sustaining its gross profit margin above 40% for FY27.
As far as project sales are concerned, the group has seen an uptick in orders for its Sorento-series sanitary ware. It order book has increased to RM150 million from RM120 million, and we expect the company to secure new orders of RM80 million each in FY27 and FY28.
Bermaz Auto Bhd
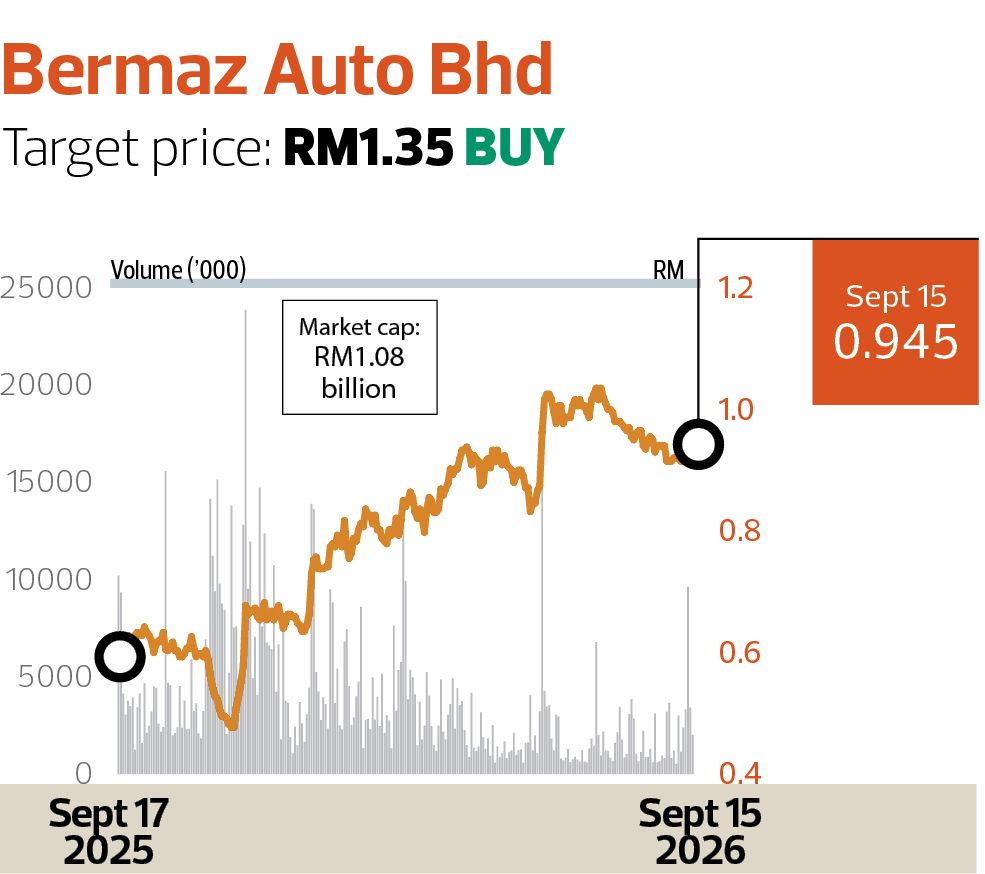
Target price: RM1.35 BUY
MAYBANK INVESTMENT BANK RESEARCH (SEPT 14): Bermaz Auto Bhd’s (KL:BAUTO) recovery trajectory continues to outperform market expectations, and we see further upside should the momentum sustain.
Near-term margins should improve with stronger support from XPeng China, while Mazda volumes remain resilient. Key considerations include completely built-up (CBU) supply and evolving earnings mix as completely knocked-down (CKD) ramps up.
Mazda CBU volume now contributes about two-thirds of sales, which we expect to sustain over the next few quarters until the all-new CX-5 CKD is launched in mid-2027. We expect 5,000 CBU units by year-end, while forex hedging should support CBU margins in FY27.
Overall, BAuto’s outlook is underpinned by new Mazda and XPeng model launches, supporting its FY27 sales target of 16,000 units (+23% y-o-y, ex-Kia sales in FY26). Associate earnings are also improving, with Inokom Corp Sdn Bhd returning to profitability and further supported by potential additional assembly contracts. Mazda Malaysia should benefit from CKD expansion, with export volume for the new CX-5 from 2027 (targeting 7,000 units per annum) providing an additional volume boost, while Kia exposure is now minimal. Near-term earnings visibility remains solid, combined with an attractive dividend yield of more than 9%.
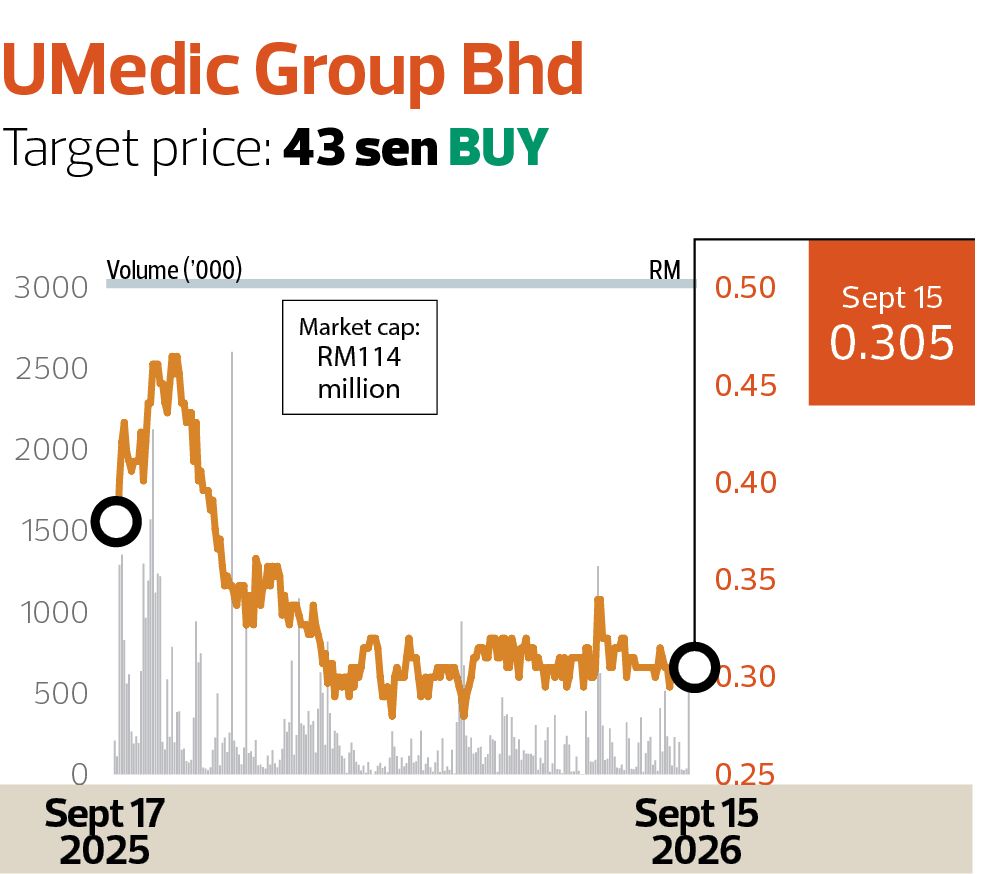
UMedic Group Bhd
Target price: 43 sen BUY
MBSB RESEARCH (SEPT 15): The RM47 billion allocated under Budget 2026 and the 13th Malaysia Plan promise of RM40 billion until 2030 continue to support UMedic Group Bhd (KL:UMC).
We believe with the upcoming Budget 2027 — which is expected to continue prioritising citizens’ welfare — UMC is positioned for sustained long-term growth by leveraging key industry tailwinds, including hospital overcrowding, medical tourism and an ageing population projected to reach 21% by 2044.
To capitalise on these trends, UMC is expected to further expand into ambulatory care by growing its ambulance fleet, scaling its integrated learning and community health centres, and diversifying into the laboratory market and specialised verticals via its Akiteck and Ateria subsidiaries.
Additionally, UMC is reinforcing its manufacturing foundation by acquiring three acres of industrial land, expanding clean room capacity and adopting advanced automation to meet rising domestic and global demand across its product portfolio.
By incorporating UMC’s FY26 results into our valuation, we revised FY27-FY28 earnings forecasts upwards by 2%. We like UMC for its stable distribution business, paired with its high-margin proprietary manufacturing operations. UMC’s key drivers remain the government’s fiscal support and long-term demographic tailwinds in terms of care demand and medical tourism.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.