

KUALA LUMPUR (Sept 21): Tenaga Nasional Bhd (KL:TENAGA) extended its decline as investors and analysts weigh the impact of additional subsidy on the national electric utility’s earnings.
At least two downgraded Tenaga on Monday though the stock still has ‘buy’ calls from a large majority of the research houses. The additional cost is expected to shave 2%-3% off Tenaga’s earnings this year, according to TA Securities, UOB Kay Hian and RHB Research.
“The latest development came as a negative surprise,” TA Securities said, noting that unlike during the Ukraine War when the government stepped in with subsidies to shield domestic consumers from electricity cost volatility, it appears that Tenaga is shouldering the burden this time around.
The house lowered its rating to ‘hold’ and target price to RM13.80 from RM18.00 after cutting earnings forecasts.
Tenaga fell as much as 16 sen or 1% to RM12.88 in Monday trading, adding to the 2% loss in the previous session after agreeing to absorb the expanded electricity subsidy for households for an estimated RM120 million to RM150 million.
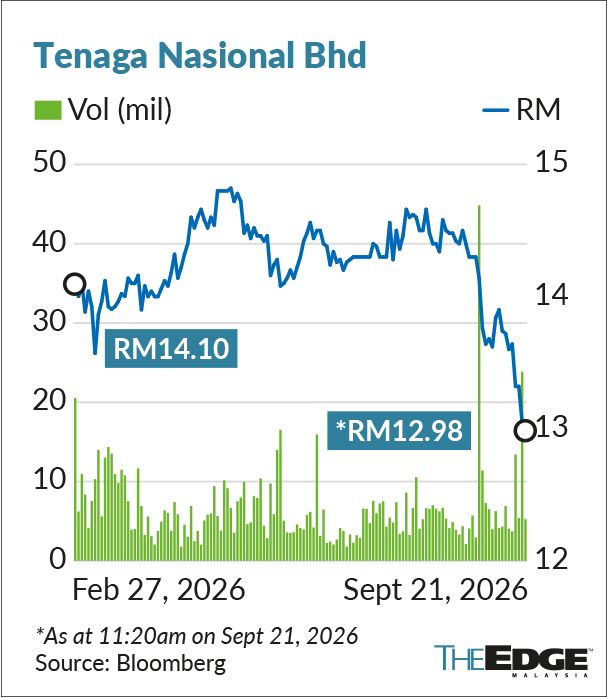
Shares of Tenaga have lost all of the gains made earlier this year when investors were betting on rapidly-booming data centres and the stock also emerged relatively unscathed when the Iran War broke out.
However, analysts are now concerned that Tenaga is absorbing costs that would normally be passed through under the existing electricity tariff framework, raising uncertainty over whether the utility will be asked to shoulder similar costs again if fuel prices remain elevated.
“We expect investors to gradually discount the sanctity of the incentive based regulation and cost pass-through framework,” UOB Kay Hian said, flagging that “we cannot say with certainty that this is a one-off” and downgraded the stock to ‘hold’.
Still, 18 of 22 analysts covering Tenaga and tracked by Bloomberg have ‘buy’ calls, four have ‘hold’ and none have a ‘sell’ recommendation. The average 12-month target price stood at RM16.17.
For RHB Research still bullish on the stock, the additional cost that Tenaga will have to bear is manageable as earnings will improve in the second half of the year.
A lower effective tax rate in the fourth quarter will help and should more than offset the additional subsidy cost, the house said in keeping its ‘buy’ call on Tenaga. Further, coal and gas prices have moderated from recent peaks, easing some of the pressure on fuel costs, RHB Research added.
On Friday, the company stated that it will take on the impact from the electricity tariff fuel surcharge exemption that has been expanded to more households up until the end of this year.
Households consuming 800 kilowatt-hour of power or less monthly will now be spared from the surcharge under the automatic fuel adjustment as part of a move to address the rising cost of living. The exemption is previously provided only to those using under 600 kilowatt-hour each month.