

A weekly round-up of tanker and dry bulk market (Sept 18, 2026)
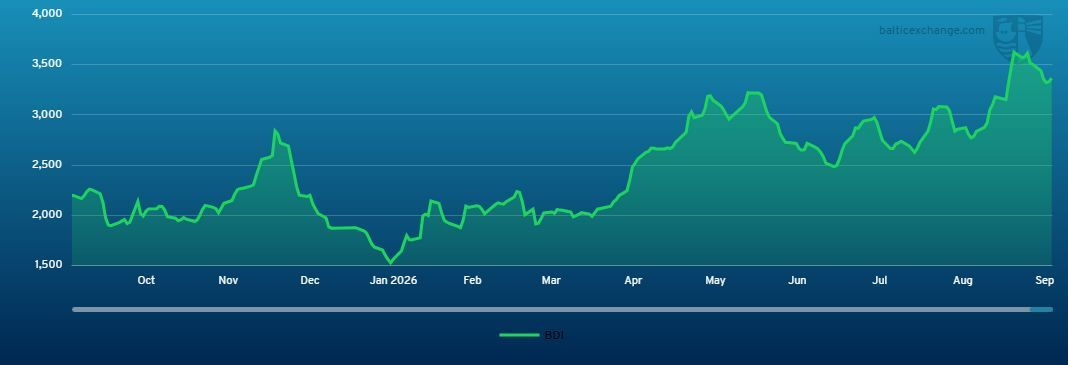
The Baltic Exchange, a wholly-owned subsidiary of Singapore Exchange, is the world's only independent source of maritime market information for the trading and settlement of physical and derivative contracts.
Its international community of over 650 members encompasses the majority of world shipping interests and commits to a code of business conduct overseen by the Baltic.
For daily freight market reports and assessments, please visit www.balticexchange.com.
Capesize
The market exhibited a generally softer tone through the first half of the week, with the Pacific bearing the brunt of the weakness as prompt tonnage continued to outweigh fresh cargo demand. C5 rates fell from the low US$17s at the start of the week into the mid-US$16s before sentiment began to stabilise towards the close. In contrast, the Atlantic proved increasingly resilient, with South Brazil and West Africa to China gaining momentum as fixing activity picked up, particularly in the latter part of the week. A series of C3 fixtures for October dates emerged in the low-to-mid US$42s, with stronger levels approaching US$43 as sustained fixing reduced both cargo availability and the number of ballasters. The North Atlantic also recovered some ground, with firmer fronthaul fixtures reported, although trans-Atlantic activity remained relatively limited. Overall, the BCI 182 5TC ended the week at US$52,315, down US$1,307 from Monday's US$53,622, although sentiment improved towards the close as Atlantic demand strengthened and Pacific rates appeared to find a floor.
Panamax-Kamsarmax
The Panamax market experienced a generally softer week, with sentiment under pressure across both the Atlantic and Pacific basins, reflected in the steady decline of the P5TC. Early in the week, participants adopted a cautious approach, resulting in limited activity and wide bid-offer spreads. While fronthaul demand provided some support, overall momentum remained subdued. Notable Atlantic fixtures included an 82,000-dwt open in the North Continent fixing for a North Coast South America trip to China at US$34,750 while an 82,000-dwt open in West Africa fixed a trans-Atlantic round at US$23,500. As the week progressed, increased grain and mineral enquiry supported activity on both trans-Atlantic and fronthaul routes. An 82,000-dwt vessel fixed basis delivery East Coast India for a fronthaul trip via East Coast South America at US$24,000, while a 76,000-dwt vessel secured US$20,500 for a similar trade. However, ample vessel availability continued to weigh on rates. In the Pacific, demand from Australia, Indonesia and the North Pacific remained evident, although expanding tonnage lists and slower cargo activity pressured fundamentals. Indian mineral import demand generated several fixtures, including an 84,000-dwt vessel fixing at US$22,500 for a trip via Indonesia. Activity in the North Pacific also remained healthy, with a 78,000-dwt vessel fixing a grains cargo to the Singapore-Japan range at US$20,500, while an 82,000-dwt vessel secured US$19,000 for a similar trip. Period activity was also reported, with one 82,000-dwt vessel fixing for one year at US$22,500 and another securing US$17,000.
Ultramax/Supramax
Slow steady gains to the index again this week, with the Asian market posting the increases this week. The North Pacific was active with grains, potash and soda ash stems aplenty, supported from a busy backhaul market with several vessels fixed via the Gulf of Aden to the Mediterranean in the low US$20,000s. Indonesian coal demand saw rates jump from a 60,000-dwt fixed delivery Chittagong via Indonesia to India at US$19,500 on Monday, to several Ultramaxes fixed at US$22,000 towards the end of the week, albeit with slightly larger deadweights. The highlight from South Africa was a 58,000-dwt being covered at US$26,750 plus US$270,000 ballast bonus for a trip to Pakistan-India. The positive sentiment resulted in more period trades, with a 63,000-dwt fixed for five to seven months at US$23,000 and a 66,000-dwt fixed for six to eight months at US$23,500, with many of these trades involving backhaul business as first employment. In the Atlantic, the US Gulf remained flat with 63,000-dwt fixed at US$33,000 to Vietnam. The Mediterranean was active all week with small gains, but the Continent suddenly found itself bereft of tonnage after various fertiliser and grain stems were covered, so the scrap market scrambled for tonnage, with talk of rates being discussed in the mid to upper US$30,000s for trips to Türkiye on Ultramaxes.
Handysize
The Handysize market strengthened over the week, with the Atlantic remaining the main source of support again. The Continent and Mediterranean remained balanced to firm, underpinned by healthy scrap demand and several strong fixtures, including a 33,000-dwt was placed on subjects at US$29,000 for a trip from Aalborg to the East Mediterranean. The US Gulf maintained strong upward momentum as tight tonnage and healthy demand lifted rates, highlighted by a 40,000-dwt reported fixed from the Mississippi River to Türkiye at US$28,000. The South Atlantic also remained well supported, with a 38,000-dwt reported fixed from Vila do Conde to Norway at around US$25,000. In contrast, the Pacific was largely steady to subdued, with limited fresh enquiry and rates generally holding around last-done levels. A 39,000-dwt open Yokohama was fixed via Japan to Malaysia with slag at the mid-US$17,000s. Period activity remained evident, including a 40,000-dwt fixed for one year at US$17,250.
Clean
LR2
The TC1 75kt MEG/Japan index continued to gently climb this week by 25 points to WS82. A voyage west also saw the TC20 90kt MEG/UK-Continent index drop from US$16.5 million to US$16.35 million. The TC15 80kt Mediterranean/East index firmed a little over a million dollars this week to US$7.2 million, with the corresponding TCE up to US$50,300/day on Baltic description round trip.
LR1
The TC5 55kt MEG/Japan index has been assessed up another 21.5 points this week to WS842. A run west on TC8 65kt MEG/UK-Continent ended the week with the index US$457,000 higher at US$11.14 million.
MR
The TC17 35kt MEG/East Africa index climbed early this week by around 15 points before stabilising for the remainder at just over WS740, generating circa US$90,500/day on Baltic description round trip TCE.
On the UK-Continent, MR freight levels managed to pick themselves up of the WS100 deck this week. The TC2 37kt ARA/US-Atlantic Coast index was assessed 41 points higher than last week at WS141. This brought the Baltic TCE for the round trip up from -US$6,500 to now just -US$477/day.
In the US Gulf, MR freight levels modestly pushed up this week. The TC14 38kt US Gulf/UK-Continent run is currently publishing at WS232, up 15 points from where is started the week, with the Baltic round trip TCE for the run is now at US$20,400/day. The Caribbean voyage on TC21, 38kt US-Gulf/Caribbean, mirrored this direction and currently sits at US$682,000 with the corresponding TCE now at US$14,200/day on Baltic description.
The MR Atlantic Triangulation Basket TCE rose from US$21,000/day to US$27,200/day.
Handymax
In the Mediterranean, Handymax rates remained relatively level this week in the mid WS180s for the TC6, 30kt Cross-Mediterranean index, translating to US$9,200/day on Baltic TCE round trip. The TC23 30kt Cross UK-Continent route strengthened 38 points to WS221 this week, which generates US$16,300/day on Baltic TCE round trip, up 135% from last week.
VLCC
The rates for the Middle East routes increased dramatically again this week. The TD3C route (270,000 mt Middle East Gulf to China) rose from WS929.44 last Friday to WS1,140 on Thursday. This gives a daily round-trip TCE of US$1,212,503 for the standard Baltic VLCC.
TD34 (Gulf of Oman/China) gained 263 points to WS806.43 in the same period, meaning a round-trip TCE of US$870,947/day.
In the Atlantic market, further gains were made. The rate for the 260,000mt West Africa to China route (TD15) climbed 108 points to WS531.25, giving a round voyage TCE of US$524,575/day, while the US Gulf to China route (TD22) made another large step up, rising over US$14,100,000 to over US$50,775,000, which gives a TCE of just over US$388,400/day.
Suezmax
The market was again firmer across all the Baltic routes. The rate for the 130,000 mt Nigeria/UK Continent voyage (TD20) rose three points to WS454.44, which translates into a daily round-trip TCE of about US$238,500. The TD27 route (Guyana to UK Continent basis 130,000 mt) was boosted by another 42 points to WS461.67, giving a daily round trip TCE of just shy of US$246,400. The 145,000 mt USG/UKC (TD33) gained another 52 points to WS385.83, which gives a round-trip TCE of just over US$238,450/day.
In the Black Sea, the market strengthened again. For the TD6 route of 135,000 mt CPC/Augusta, the rate has had five points added and setline at just over the WS500 mark, which shows a daily round-trip TCE of about US$366,750.
Aframax
In the North Sea, the rate for the 80,000 mt Cross-UK Continent route (TD7) gained 42.5 points to WS301.67, showing a daily round-trip TCE of just over US$186,000 basis Hound Point to Wilhelmshaven.
In the Mediterranean, the rate for 80,000 mt Cross-Mediterranean (TD19) climbed 46 points this week to WS435, basis Ceyhan to Lavera, showing a daily round trip TCE of just over US$169,700.
Across the Atlantic, the owners’ grip had loosened earlier this week, but by Thursday was constricting charterers again. The 70,000 mt East Coast Mexico/US Gulf route (TD26) dropped to WS440 by Wednesday and then rose to just over WS447.5 on Thursday, which is down 41 points week-on-week, which is a daily round-trip TCE of just shy of US$134,800. The 70,000 mt Covenas/US Gulf route (TD9) lost 30 points this week bottoming out at WS438, translating into a daily round trip TCE of about US$125,200.
The rate for the trans-Atlantic route of 70,000 mt US Gulf/UK Continent (TD25) fell back by Wednesday to about WS450, and then advanced to WS458.89 on Thursday, a weekly fall of 36 points, which gives a round trip TCE basis Houston/Rotterdam of almost US$128,100.
On the Vancouver exports, the TD28 (80,000 mt crude oil Vancouver to China) rose by over US$500,000 to US$7,650,000 (giving a round trip TCE of just under US$145,400/day) while TD29 (80,000 mt crude oil Vancouver to Pacific Area Lightering point off the USWC) gained a further 60 points to WS440.
LNG
The LNG freight market experienced a volatile but generally firmer week, supported by stronger LNG commodity prices, ongoing geopolitical uncertainty in the Middle East, and increased market activity. Market sentiment improved as concerns over the Strait of Hormuz and low European gas storage levels boosted LNG price expectations, although this did not translate fully into physical shipping demand due to ample vessel availability.
Baltic LNG assessments strengthened significantly through the first half of the week before easing slightly on Thursday. BLNG1 (Australia-Japan) increased from US$26,800/day at the start of the week to finish at US$27,200/day. BLNG2 (US Gulf-Continent) climbed from US$21,500/day to a peak of US$26,900/day before ending the week at US$23,900/day. BLNG3 (US Gulf-Japan) posted the strongest gains, rising from US$40,400/day on Monday to US$53,400/day by Friday.
Chartering activity was concentrated around Australian and Qalhat requirements in the Pacific, while US Gulf export opportunities dominated Atlantic basin enquiries. Winter cover interest remained evident, with some charterers opting to secure spot tonnage amid still-competitive freight levels. However, it was reported that plentiful vessel availability continued to limit upward momentum in rates.
In the period market, the six-month assessment declined to US$45,600/day, while one-year and three-year rates remained broadly stable at US$52,533/day and US$72,350/day respectively.
LPG
The LPG market continued to strengthen this week, supported by strong arbitrage economics and exceptionally tight vessel availability. VLGC freight ex-US reached fresh highs, with several fixtures concluded above US$300/mt HCvP and only a handful of vessels remain available for prompt October requirements.
On the BLPG1 Ras Tanura–Chiba route, rates settled at US$242.00, with TCE earnings closing at US$231,509/day.
The BLPG2 Houston–Flushing route increased by US$15.50 week-on-week to settle at US$171.83, with TCE earnings rising by US$20,123 to US$197,444/day. Tight vessel availability and continued cargo demand supported rates throughout the week.
Similarly, the BLPG3 Houston–Chiba route gained US$32.71 to close at US$320.71, while TCE returns increased by US$23,524 to US$193,696/day. The route saw the strongest increase, supported by strong eastbound economics and the limited number of available vessels for October loading.
Container
Another week of ongoing tensions in the Middle East Gulf, with no end in sight, is going to keep bunker fuel prices high for now and have a knock-on effect on the container lines price per box movement worldwide. With the Houthis claiming that they control the Bab el-Mandeb Strait, this could further cause problems for container lines who use the Suez Canal if they were to try and block vessels from transiting the strait.
The cross Pacific trade loop FBX01 (China/East Asia – US West Coast) gained US$633 from last Friday ending the week at US$8,348 and is up US$2,254 since the start of August. Rates from the Far East to the USEC FBX03 (China/East Asia – US East Coast) lost US$173 from last Friday ending at US$9,606, which is up US$464 since the start of last month. Containers into the North Continent from the Far East FBX11 (China/East Asia – North Europe) decreased by US$692 week on week, ending the week at US$3,646 and is down US$1,873 since the start of August. Trade into the Mediterranean from the Far East FBX13 (China/East Asia – Mediterranean) lost just US$16 from the end of last week, ending the week at US$3,913 and is down US$2,603 from the start of August.
Disclaimer:
While reasonable care has been taken by the Baltic Exchange Information Services Limited (BEISL) and The Baltic Exchange (Asia) Pte. Ltd. (BEA, and together with BEISL being Baltic) in providing this information, all such information is for general use, provided without warranty or representation, is not designed to be used for or relied upon for any specific purpose, and does not infringe upon the legitimate rights and interests of any third party including intellectual property. The Baltic will not accept any liability for any loss incurred in any way whatsoever by any person who seeks to rely on the information contained herein.
All intellectual property and related rights in this information are owned by the Baltic. Any form of copying, distribution, extraction or re-utilisation of this information by any means, whether electronic or otherwise, is expressly prohibited. Persons wishing to do so must first obtain a licence to do so from the Baltic.