

KUALA LUMPUR (Sept 18): Tenaga Nasional Bhd (KL:TENAGA) saw RM1.63 billion wiped off its market value in late-session selling on Friday, following the national utility's announcement it would absorb the government's expanded electricity subsidy for households until the year-end.
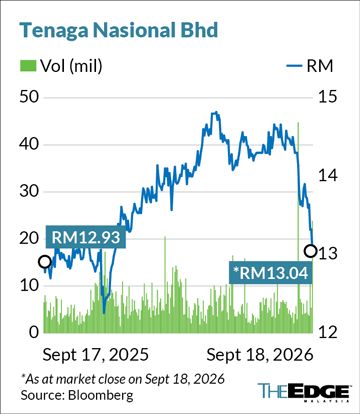
Tenaga Nasional’s share price fell to an intraday low of RM12.80 at 4.42 pm, before recovering to close at RM13.04 – its lowest in nine months since December 2025 – leaving the group with a market capitalisation of RM76.01 billion.
Friday's closing price was down 28 sen, or 2.1%, from the previous day's RM13.32, which valued the group at RM77.64 billion.
Some 23.86 million shares changed hands on Friday, more than four times the 5.40 million shares traded the previous day.
The late-session selling comes a day after the government announced it will raise the threshold for subsidised electricity from 600 kilowatt-hours a month to 800kWh. Households with power consumption below this level will also be exempt from from the automatic fuel adjustment (AFA) surcharge, retail charges and sales and services tax until the end of the year.
The Energy Commission had in April warned that the surcharge would rise as conflict in the Middle East had sent the price of fuel spriralling.
Tenaga Nasional said earlier on Friday it would absorb the electricity tariff fuel surcharge exemption, which is estimated to cost RM150 million.
The company said 20% of households used more than 600kWh of energy in July and were subject to the additional charges, up from from 13% in January.
When contacted, Rakuten Trade's vice-president of equity research Thong Pak Leng said the RM120 million to RM150 million additional cost to absorb the electricity subsidy would amount to only about 2% to 3% of Tenaga Nasional's FY2026 net earnings, based on the group's first-half net profit of RM1.99 billion, suggesting that the financial impact should be manageable.
Thong, nevertheless, said Friday's decline was justified given the estimated earnings impact.
The additional cost comes as TNB faces higher fuel costs amid the prolonged Middle East conflict. TNB said the AFA surcharge could rise above five sen per kWh in December from 3.67 sen in September, while coal prices are expected to reach US$120 per tonne in December.
At the time of writing, analysts are optimistic about the stock with 20 “buy” calls among the research houses and one “hold” recommendation. The average 12-month target price is RM16.67.
The consensus target implies potential upside of about 27.8% from Friday's closing price of RM13.04.
TNB reported a 10.37% decline in net profit to RM1.99 billion for the first half ended June 30, 2026 (1HFY2026), despite a 7.5% increase in revenue to RM32.87 billion, as higher operating expenses and lower foreign exchange gains weighed on earnings.