

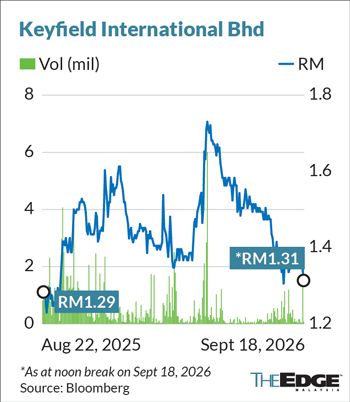
KUALA LUMPUR (Sept 18): Keyfield International Bhd (KL:KEYFIELD) slid to a one-year low amid softer accommodation workboat demand and charter rates.
However, Kenanga Research in a note on Friday said the selldown was unjustified, given Keyfield's strong cash flow and potential realisable value of its assets.
Keyfield's shares were thinly traded in the early session, slipping to two sen or 1.5% to RM1.32, valuing the group at just over RM1 billion.
"The market currently prices the stock at a 30% discount. We believe that this is unjustified as the secondary market has been active in recent years indicating strong demand for offshore support vessels even for those at old age," the house said.
Kenanga also said Keyfield's earnings may be bottoming in the financial year ending Dec 31, 2026 (FY2026), after reporting a steep 65% drop in second-quarter net profit.
The consensus now expects the oil-and-gas services firm to report a net profit of RM92 million this year, a steeper-than-previously-projected 36% fall from 2025.
Keyfield would have sunk into a net loss in the first six months of 2026 without extraordinary gains from disposals and foreign exchange.
"If we were to just look at the company’s price-to-book valuation for FY2026 at 1.4 times, the company might appear to be at the pricier end versus its peers that are trading at below-book valuations.
"However, we decided to take a more market-driven approach of examining the company’s vessel fleet by comparing its property, plant and equipment (PPE) value to a reasonable realisable market value. This is done via comparing recent transactions although we are cognisant of the fact that the estimations may not be fully accurate due to slight vessel age differences," said Kenanga.
The research house said after adding up all the realizable values in its vessels, it arrived at RM1.4 billion compared to the PPE value of RM962 million.
Kenanga further said as the company is still receiving healthy cash flows from its charters, it believes that the current market price overly punishes the stock for its current earnings downcycle.
"That aside, we believe that the discount to realisable value was also due to the group’s ability to purchase the majority of its vessels during distressed market conditions (2021-2023) allowing for a significant margin of safety. Based on our FY2026 earnings forecast of RM72 million (which we believe is downcycle earnings), the group would be able to break even on its PPE value in 12 years," it added.
Meanwhile, Kenanga believes that the second half of the year will be stronger in terms of potential vessel utilisation due to client scheduling requirements.
"That aside, our target price also has not factored in the potential upside from its new builds to be delivered in 2028 (one DP2 AWB and two 90MT DP2 AHTS) while we have only assumed 1Q's worth of contributions in FY2027 for its dredger," said the house, which kept its 'outperform' call on the stock with a target price of RM1.88.